This guide explains how Square Payroll supports contractor reporting when you need Square Payroll 1099 handling for independent workers. It provides objective background on 1099 forms, typical compliance considerations, and how to prepare payment records. You’ll also find practical requirements, a comparison-style checklist, and FAQs focused on accurate documentation and responsible payroll workflows.
Square Payroll 1099 processes the documentation trail that many businesses need when paying independent contractors. If you’re using Square to manage payments and payroll-adjacent workflows, the core challenge is consistent recordkeeping: defining who is a contractor, tracking payments made during the tax year, and ensuring your year-end reporting matches IRS expectations. Below, you’ll find an expert, objective breakdown of what 1099 reporting generally involves, how Square Payroll 1099-related workflows typically fit into day-to-day operations, and what you should verify to reduce filing errors.
This guide uses “Square Payroll 1099” as a practical shorthand for a set of operational tasks: collecting contractor details, capturing and categorizing payments during the tax year, reconciling records so totals are accurate, and preparing or supporting year-end information returns that correspond to those totals. It does not replace legal or tax advice. Instead, it’s written to help you build repeatable processes that make compliance less stressful and more reliable—especially when you have multiple departments touching contractor payments.
Many organizations distribute work through a mix of employees and independent contractors. That mix creates an accounting and compliance burden: contractors are commonly reported using IRS Form 1099 series forms, while employees are handled through W-2 reporting. Square Payroll 1099 workflows are relevant when your business relies on contract labor—designers, consultants, delivery partners, event staff, or specialized services—paid through payment systems managed in part via Square tools.
From an operational standpoint, the key is not just “generating” a tax document—it is ensuring the underlying classification and payment totals reflect the correct reporting category. A small mismatch (for example, including reimbursements or excluding certain adjustments) can cause a contractor to see discrepancies, which later become a reconciliation headache for your finance team.
In real businesses, the problems rarely begin at year-end. They begin earlier—when contractor onboarding data is incomplete, when payment categories are inconsistent across months, when refunds are recorded without linking them back to the original transaction, or when there’s no clear definition of what counts as reportable compensation. Square can help with structure and exports, but it cannot automatically solve classification decisions or accounting policy choices.
In common business usage, “Square Payroll 1099” refers to the family of IRS information returns used to report certain types of income paid to non-employees. Very frequently, businesses think of Form 1099-NEC (Nonemployee Compensation), but the exact form depends on the payment type and reporting rules. The IRS provides authoritative guidance on whether and when to file information returns, including Forms 1099-NEC and related forms.
Primary reference (IRS): IRS official pages covering information returns and 1099 filing requirements, including instructions for Form 1099-NEC and general guidance for reporting nonemployee compensation.
Source: Internal Revenue Service (IRS), “Form 1099-NEC” instructions and related 1099 information return guidance (IRS.gov).
It’s also important to understand that “1099” is not one single checkbox. The IRS has many information returns (1099 series and others) that apply to different payment categories, different thresholds, and different conditions. Your organization’s specific mix of contractor services, types of payments, and contractual arrangements will determine which forms—if any—apply.
Even when a platform supports “1099-ready” workflows, reporting quality still depends on upstream decisions: contractor onboarding, payment method handling, and what transactions count toward reportable compensation. Square Payroll 1099 handling is top understood as a system-assisted process that helps you capture totals and provide documentation, rather than a substitute for legal classification and tax judgment.
Square-like tools typically help with operational consistency: they provide payment records, can segment customers vs vendors, can allow contractor-specific identifiers, and can produce exports used for reconciliation. But the underlying compliance work still rests on accurate data and consistent policy.
Industry professionals typically see fewer problems when businesses focus on these areas early:
There’s also a fourth “quiet” failure point that appears in many organizations: uncontrolled changes. For example, someone updates an internal mapping or category rule after the fact, but doesn’t rerun reconciliations or document the changes. Even when the total seems correct, the lack of traceability can make it difficult to explain a discrepancy during a review or audit.
The following approach is designed to be practical for finance and operations teams. Use it as a workflow model, then adapt it to your organization’s tools, policies, and compliance review process. The goal is to make 1099 preparation feel like a natural byproduct of good operations rather than an emergency process at year-end.
Before worrying about forms, confirm whether your worker should be reported as a nonemployee for the payment type you issued. If you are unsure, consult qualified tax counsel or a professional familiar with U.S. worker classification rules. Keep your decision rationale documented.
In practice, classification decisions often involve multiple signals: behavioral control, financial control, and the nature of the work relationship. Your process should also consider whether your contract terms match the real-world working arrangement. If your contracts say “independent contractor” but your operations manage the work like an employee relationship (including detailed instructions, scheduling control, and performance monitoring), the classification risk increases.
Beyond federal tax considerations, some states also apply their own tests and reporting requirements. Even if federal treatment supports contractor status, state-level rules may differ. Therefore, classification confirmation should be treated as an ongoing process rather than a one-time review.
For Square Payroll 1099 workflows to be accurate, contractor profiles should be complete and consistent. Ensure names and tax details (where collected) are accurate and retained through your internal document retention policy.
Contractor onboarding should include a standardized data checklist. Consider assigning a single owner for contractor profile creation and updates, such as a finance operations specialist or onboarding coordinator. Avoid a scenario where different departments create contractor records using different naming conventions (for example, using “Legal Name” vs “Business Name” inconsistently).
Good profile management usually includes:
Create a written rule-set for your team: which payments are considered contractor compensation for reporting purposes, and which are excluded (for example, certain reimbursements depending on your treatment). Then, apply that rule consistently transaction by transaction.
This step is often where organizations struggle. Without a clear internal definition of “compensation” vs “reimbursement” vs “other charges,” teams interpret transactions differently across time and departments. Over the course of a year, this can cause totals to drift away from what you intend to report.
To make this step operational, you can convert tax concepts into practical accounting actions. For example, create internal categories or tags in Square that align with your reporting policy. Then document how each category is treated.
Common policy examples (conceptually; not legal advice):
Instead of waiting until year-end, reconcile at least monthly: compare system outputs to bank statements, payment exports, or accounting records. This reduces the chance that a small mismatch becomes a large year-end problem.
A monthly reconciliation routine improves data quality because errors are caught while the underlying transactions are still fresh and while teams can access documentation quickly. It also gives you time to correct contractor data for the relevant reporting period.
When building your routine, set a consistent reconciliation structure. For instance:
It’s also helpful to set thresholds for what requires investigation. For example, small rounding differences might be explained easily, while large category-level variances trigger a deeper review.
Perform a “reasonableness check” on totals and identities. Spot-check a sample of contractors, verify payment totals for the reporting period, and confirm the contact details needed to deliver information returns.
A robust pre-filing review can be structured like a lightweight internal audit. It should include both accuracy and completeness checks. Accuracy checks confirm that totals per contractor are correct. Completeness checks confirm that required fields exist and that you didn’t inadvertently omit a contractor who meets the reporting criteria.
Consider implementing:
If an error is found after submission, corrections generally require careful handling. Keep a documented process for identifying errors, communicating changes to contractors, and making updates in your system.
Correction processes should include version control and traceability. For example, if you discover that a category mapping caused a portion of payments to be excluded, you need to:
The operational aim is to avoid “silent fixes” that change totals without a documented rationale. Silent fixes may leave your team unable to explain why totals changed and may complicate reconciliation if another review is needed.
Regardless of whether your reporting is supported by Square tools, maintain backups of: payment exports, contractor agreements, internal classification notes, reconciliation worksheets, and copies of final filings.
Think of your recordkeeping as two layers: operational records and compliance records. Operational records include transaction exports and reconciliation logs that explain how totals were computed. Compliance records include the final forms, supporting documentation, and any communications required for corrections.
A common best practice is to store a “reporting package” for each tax year. This package might include:
Because platform pricing can vary by plan, region, feature set, and contract terms, this guide avoids quoting a single universal “price.” Instead, you should evaluate the cost structure you are actually on, including fees related to payroll processing, contractor support features, reporting exports, and any add-on services required for 1099 workflows. If you are comparing vendors or plans, request a written pricing schedule and clarify which services affect year-end reporting preparation.
Practical recommendation: When assessing “Square Payroll 1099” readiness, treat pricing as part of a total cost of ownership: time saved in reconciliations, fewer corrections, and improved audit readiness can outweigh small differences in tool fees.
In many organizations, the hidden cost of “cheaper” tools is rework. If the platform makes it harder to consistently categorize transactions, or if exports are limited, you may end up using manual spreadsheets to reconstruct totals—introducing both error risk and labor cost. Therefore, when comparing options, ask questions about:
For finance teams, “supplier” can include the payroll platform provider, your accounting software vendor, and any tax preparation or compliance provider you may use. Since tax rules and system capabilities can change, rely on official sources for the reporting requirements and the platform’s documentation for feature behavior.
Recommended source types:
Source: Internal Revenue Service (IRS.gov) and official product documentation from the relevant provider(s).
It’s also wise to treat “tribal knowledge” cautiously. If your team relies on memory (for example, “we’ve always excluded reimbursements like X”), document it. Formal documentation reduces the risk that a new team member will interpret your policies incorrectly.
| Category | What to Verify for Square Payroll 1099 Readiness | What “Good” Looks Like |
|---|---|---|
| Worker classification | Whether the worker is treated as an independent contractor vs employee, based on facts and applicable rules. | Documented classification rationale and consistent treatment across the tax year. |
| Contractor profile completeness | Whether required identifying details are present and current for each contractor. | No missing fields for active contractors; consistent identity formatting. |
| Payment mapping | Which payment categories in your system are included in reportable totals. | A written rule-set and consistent transaction tagging. |
| Adjustments handling | How reversals, refunds, partial payouts, and corrections impact totals. | Totals reconcile after adjustments; corrections are traceable. |
| Monthly reconciliation | Whether system records match accounting records and bank statements. | Documented reconciliations with clear variance explanations. |
| Pre-filing review | Whether totals and identities are reviewed before final submission. | Sample checks performed; exception list resolved. |
| Record retention | Whether you maintain audit-friendly records supporting your totals. | Stable storage of exports, agreements, and reconciliation evidence. |
No. “Square Payroll 1099” typically refers to the platform-assisted workflow for preparing or organizing information relevant to 1099 reporting. Filing obligations depend on IRS rules, the nature of payments, and correct worker classification. Always confirm requirements using IRS guidance and/or qualified tax professionals.
At minimum, you need consistent contractor identity information and correct payment totals for the relevant reporting period. Additionally, you should maintain documentation supporting how you determined what counts as reportable compensation and how you handled adjustments like refunds or reversals.
Reconcile monthly, standardize how transactions are categorized, and run pre-filing checks that include spot verification of totals and contractor profiles. A documented exception workflow (e.g., missing data, mismatched totals) is usually more effective than a last-minute scramble.
It depends on the circumstances and how those amounts are treated in your records and payment arrangements. Because treatment can vary, the top practice is to define your policy for what is reimbursable versus compensation and apply it consistently. Consult IRS instructions and professional guidance for your specific scenario.
Fix data as early as possible using a documented correction process. Incomplete or incorrect information can lead to delays and the need for corrections. Keep evidence of updates and the timeline of changes for internal audit readiness.
Platform tools can improve accuracy and organization, but they do not replace compliance judgment. You remain responsible for correct classification, correct totals, and adherence to filing and reporting rules.
Yes. Beyond federal IRS rules, states may have additional requirements related to reporting, withholding, or business compliance. If your contractor base spans multiple states, you should consult qualified advice and review your obligations at both federal and state levels.
While many teams focus on the year-end moment—downloading a report, preparing forms, and sending copies—seasoned practitioners know the real work occurs earlier. “Square Payroll 1099” should be treated as a downstream outcome of a disciplined operating model: onboarding rigor, transaction categorization, reconciliation routines, and controlled change management.
To make this effective, you should design your workflow so that each month naturally produces “reporting-quality” data. The year-end step should then resemble a validation and packaging step, not a discovery phase.
Start by connecting onboarding steps to reporting needs. If your business hires independent contractors, you should have a repeatable onboarding flow that collects and validates the data you will later use for information returns. Even if a system provides a convenient export, missing fields and inconsistent naming conventions will eventually create friction.
Operational design also includes defining roles and responsibilities. For example:
When these roles are unclear, the process becomes “whoever is free at the end of the year,” and that is where mistakes happen.
Another key design element is validation timing. Instead of waiting until late in the tax year to confirm data completeness, validate at onboarding and then re-validate periodically for active contractors. For example, run a quarterly audit of contractor profiles to identify missing identifiers early.
One of the very subtle issues in 1099 preparation is deciding what constitutes reportable compensation. A mature process includes a boundary definition and a practical rule-set. For example:
This is where finance collaboration matters. Operations teams often see “what the customer paid,” while accounting teams see “what belongs in compensation totals.” When these perspectives converge on an agreed definition, reporting accuracy improves.
To operationalize this boundary, you can implement “category governance.” Category governance includes:
It can also help to build a “transaction type library.” For example, create internal examples for:
Even if your team is small, a library reduces confusion and keeps category usage consistent.
Systems like Square can reduce friction, but they also magnify inconsistency if your team codes transactions differently across months. If you treat similar contractor payments differently (e.g., one recorded as a service payment and another recorded as something else), your year-end totals may diverge from what you intended.
The antidote is simple but requires follow-through: standard transaction categories, periodic audits of category usage, and clear guidance for how refunds and reversals should be recorded.
System discipline also includes consistent handling of:
When you treat these cases inconsistently, the “total by contractor” can still look plausible, but the underlying composition will be wrong—creating risk for corrections or disputes.
In many organizations, reporting errors are discovered late because reconciliations happen too infrequently. A monthly reconciliation rhythm creates a “quiet month” advantage: variance becomes manageable, and exceptions are resolved while the relevant context is still fresh.
Exception management should be documented. For instance:
Exception management also requires clear definitions of ownership and escalation. Who fixes the category mapping? Who contacts the contractor? Who approves a correction? Without escalation pathways, exceptions linger, and by the time you reach year-end the list is longer and more complex than expected.
Many teams also benefit from a formal “exception register.” An exception register is a living list of issues—missing data, mismatched totals, category anomalies—along with:
This creates accountability and reduces the risk of losing track of problems.
Pre-filing reviews work top when they are structured. A typical control set includes:
This approach is aligned with how audit-minded teams reduce downstream filing corrections.
To strengthen quality control, include both “top-down” and “bottom-up” tests:
Top-down and bottom-up tests help you catch errors that “balance” out by accident.
Because tax rules evolve and details depend on your payment structure, the very reliable approach is to anchor your process in official guidance and instructions. For U.S. 1099 reporting, the IRS is the authoritative source for thresholds, applicability, form instructions, and filing mechanics.
Source: Internal Revenue Service (IRS.gov), including Form 1099-NEC instructions and guidance for information returns.
Even if your process is mature, tax rules can change, and your business model can change. For example, if you start paying more contractors, expand to new states, introduce new payment types, or shift from one accounting practice to another, you should revisit your policy rules and ensure your mapping remains correct.
In many workplaces, the practical experience of managing contractor payments tends to be local to the team’s operating rhythm—whether you’re handling seasonal projects near your community, supporting events around local neighborhoods, or coordinating contract labor in a business corridor. The operational reality is consistent: teams need predictable documentation, clear ownership, and a disciplined reconciliation routine. Even when vendors and tools change, the process principles remain stable “nearby.”
In practice, local differences show up as variations in how contractors communicate, how quickly you receive onboarding documentation, and how you handle reimbursements tied to travel or local expenses. Therefore, even if your compliance logic is uniform, your operational execution may need localized adjustments—while still preserving consistent reporting category treatment in your system.
To supplement the comparison table above, here are conditions and requirements you should treat as non-negotiable controls for reliable Square Payroll 1099 workflows:
To strengthen this checklist, you can add internal evidence standards. For example:
From an industry perspective, the strongest predictor of year-end reporting quality is not the sophistication of the tool—it’s the maturity of the workflow. When companies design their contractor-pay process with reporting as a first-class outcome, they reduce corrections, improve contractor relationships, and create audit-friendly records.
In that sense, Square Payroll 1099 is less about a single feature and more about the discipline behind it: correct classification decisions, consistent transaction coding, and reconciliation that catches anomalies early.
Experts also emphasize the human element. Contractor reporting involves communications, timing, and data quality that depend on external parties. If contractors provide incomplete tax information late in the year, your process should have a contingency plan. That plan might include:
Another emphasis is clarity of documentation. Many filing mistakes are not purely mathematical—they are definitional. For instance, a team may have misunderstood what should be included in reportable totals for your specific arrangement. Clear internal policy documentation prevents repeated misunderstandings.
Square Payroll 1099 workflows can support more organized reporting, but the foundation is still your operational controls: correct contractor identification, consistent payment categorization, accurate reconciliation, and a documented review process. By approaching 1099 preparation as an ongoing system—starting at onboarding and continuing through monthly reconciliations—you position your business to handle reporting with confidence and professionalism.
If you implement the steps above—classification confirmation, consistent contractor profiles, a clear boundary for reportable compensation, disciplined monthly reconciliation, and structured pre-filing review—you reduce the likelihood of corrections and contractor confusion. Even if your toolset evolves, these operational principles remain stable. They are what transform 1099 reporting from a year-end scramble into a reliable workflow outcome.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

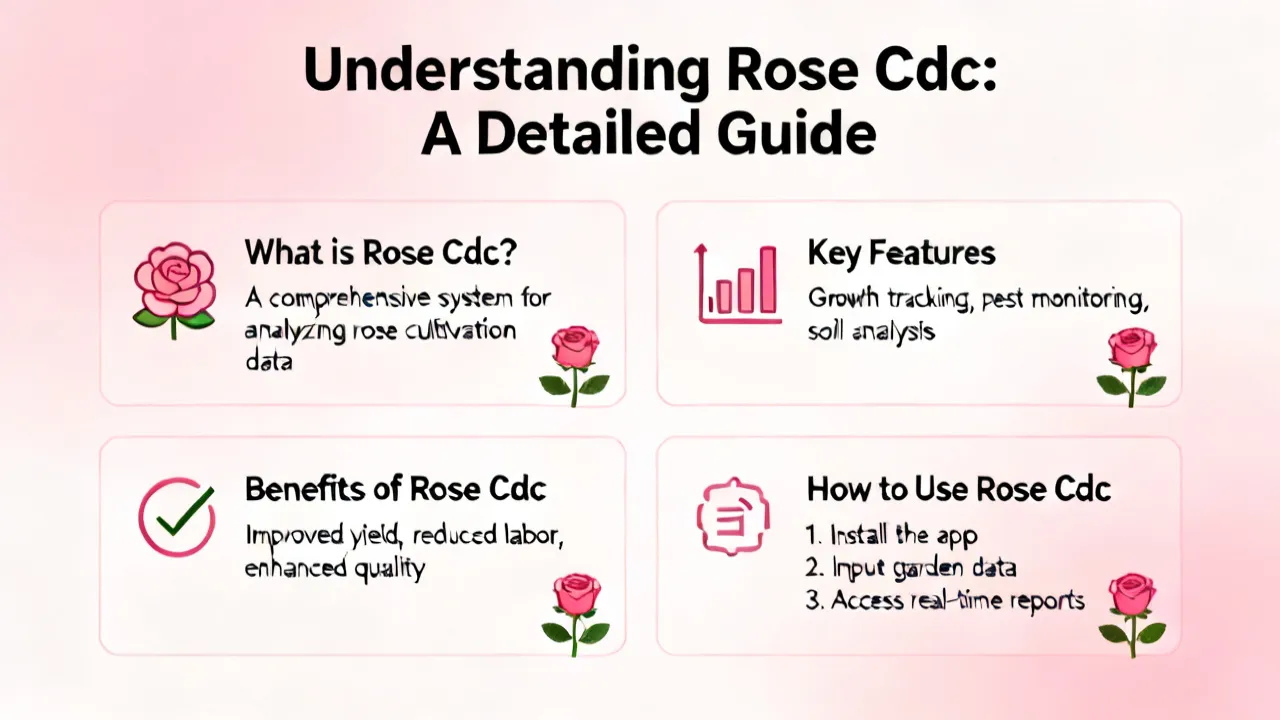
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.
