This guide explains how Intuit Payroll supports payroll processing, tax reporting, and pay-run accuracy for growing businesses. It provides objective background on payroll fundamentals and key terms—like deductions, filings, and employee records—then moves into practical selection and implementation considerations, including operational steps, risks to avoid, and readiness requirements.
Intuit Payroll is designed to help businesses run payroll with a structured workflow that connects employee data, pay calculations, pay stubs, and payroll reporting. For organizations aiming to reduce manual effort and improve consistency, it typically serves as a centralized system that supports pay processing and helps align payroll outputs with required tax documentation. The real value comes from disciplined setup: once employee details, pay schedules, and deduction rules are configured correctly, the software can streamline recurring payroll tasks while making it easier for managers to audit what happened during each pay period.
From an industry standpoint, payroll is rarely “just” payment processing. It is a compliance-heavy cycle involving wage calculations, withholding rules, employer obligations, documentation retention, and timely filings. Intuit Payroll fits into that operational reality by focusing on repeatability—helping businesses establish a predictable process for each payroll run rather than treating every month as a new spreadsheet exercise.
Below, you’ll find an expert, practical overview of how to evaluate Intuit Payroll, how to implement it responsibly, and what conditions you should verify before going live—especially if you’re integrating payroll into your existing HR and accounting workflows.
Payroll platforms (including Intuit Payroll) typically coordinate several interconnected functions:
Because the payroll cycle can create downstream accounting impacts, payroll output consistency is critical. Systems that make it easy to correct errors after the fact can reduce operational disruption, but the top outcomes come from careful initial configuration and disciplined change control (e.g., ensuring employee changes are entered before the payroll cutoff).
Before selecting or implementing any payroll solution, it helps to understand that requirements vary by jurisdiction and business type. Therefore, businesses should validate their obligations with qualified professionals and use official government guidance as the reference point for compliance decisions.
When comparing payroll platforms, it’s tempting to focus only on user experience. However, the operational “fit” is determined by control, data integrity, and reporting traceability. An expert evaluation typically asks:
For many teams, the very important factor is not whether the software can run payroll, but whether it helps the organization maintain consistency month after month—especially when staff changes, new hires occur, or pay rules evolve. A payroll system becomes “critical infrastructure” when it stops being a one-off project and becomes a repeatable operating rhythm.
In practical terms, you can think of evaluation as three layers: (1) functional ability, (2) operational safety, and (3) compliance reliability. A tool may appear capable on the surface but still fail your needs if it doesn’t make it easy to prevent errors, capture evidence, or produce filing-ready documentation.
Even when payroll software automates calculations, organizations must provide accurate inputs. A strong implementation plan treats payroll setup like a compliance project with clear owners and verification steps.
Typical planning milestones include:
These steps reduce avoidable rework. They also improve employee trust because pay outcomes are more stable and easier to explain. When employees notice fewer discrepancies—missed deductions, wrong pay rates, inaccurate overtime calculations—that trust compounds over time and reduces manager escalations.
It’s also helpful to design the workflow around the realities of the organization. For example, if time tracking data arrives at different times from different departments, you may need a consistent “data freeze” time. If approvals require leadership sign-off, you may need time buffers so payroll isn’t pushed into last-minute decision-making.
In other words: software reduces manual effort, but it doesn’t remove the need for operational discipline.
Pricing for payroll solutions commonly depends on factors such as number of employees, pay frequency, and additional features (reporting depth, integrations, or add-ons). Because pricing can change and may differ by plan and region, businesses should confirm current rates directly with the official vendor documentation or authorized channels before committing.
As a supplier context, Intuit is a major business software provider known for productivity and finance tools used by many organizations. In payroll evaluation, the practical question is whether the payroll offering aligns with your finance workflow and whether the implementation process is supported with clear guidance.
Recommendation: If you are preparing internal budgeting, gather quotes or plan details from official Intuit materials and incorporate any implementation or administrative costs (training time, data cleanup, and potential integration work) into the total cost of ownership.
When teams treat “price” as only a monthly fee, they often miss cost drivers that show up later: employee data cleanup, mapping payroll outputs into accounting entries, and training managers or finance staff for approval processes. Those costs vary widely based on data readiness.
To keep cost evaluation realistic, consider building a simple total cost of ownership model that includes:
This approach helps ensure that you’re not surprised by hidden costs later and that the payroll system you choose actually reduces the time burden on the people who run payroll.
Payroll errors can be expensive and stressful. While payroll tools reduce manual effort, they don’t remove responsibility. Common pitfalls include:
As an industry top practice, treat payroll “go-live” as the start of an ongoing control cycle: review, reconcile, correct, and document. Automation should improve accuracy, but governance makes accuracy sustainable.
It’s also useful to distinguish between “calculation errors” and “configuration errors.” Calculation errors occur when the system computes incorrectly based on the inputs; configuration errors occur when the system was set up wrongly in the first place (e.g., a deduction category mapped to the wrong type of withholding). The second category is often more dangerous because it can affect multiple pay periods before anyone notices. Good testing, monitoring, and early validation reduce the chance of discovering configuration mistakes only after employees complain.
Another common pitfall is failing to plan for edge cases. Payroll isn’t only for standard employees who work consistent hours. Consider how you handle:
If your organization has these scenarios, your implementation plan should include testing and documented guidance for each, so the payroll process remains stable even when exceptions occur.
The following checklist is a practical supplement—meant to help you move from evaluation to a controlled production workflow. Replace placeholders with your internal process names and approvals.
| Stage | What to do | Key conditions/requirements |
|---|---|---|
| 1. Readiness check | Confirm employee data sources (HR records, hire forms, compensation spreadsheets) and identify gaps. | You have reliable employee records and a defined data owner. |
| 2. Define pay rules | Set pay schedules, earnings types, overtime/adjustment logic (if applicable), and recurring deductions. | Pay rules match your policies and are verified against official guidance or expert advice. |
| 3. Configure employee profiles | Enter or import employee master data and withholding-relevant information. | Cutoff timeline is established; changes will be submitted before payroll runs. |
| 4. Build a review workflow | Assign reviewers and set acceptance criteria (e.g., paycheck preview checks, summary reconciliations). | At least one independent review step exists before processing. |
| 5. Run a test pay cycle | Perform a test payroll (or equivalent preview workflow) for a subset or a controlled period. | Test scenarios reflect real pay structures; results are documented. |
| 6. Confirm reporting outputs | Validate payroll summaries, pay stubs, and any report views needed for internal and filing workflows. | Reports can be exported/archived according to your retention policy. |
| 7. Go live with controls | Process the first production payroll following the documented review and approval steps. | Emergency correction process is defined (who authorizes changes and how). |
| 8. Post-run reconciliation | Reconcile payroll results to accounting entries and confirm totals match internal expectations. | Reconciliation owner and timeline are specified. |
To make the checklist even more actionable, you can expand it into “evidence requirements.” In regulated operations—or simply in mature finance teams—each stage produces evidence. Evidence doesn’t have to be complicated; it just needs to be retrievable. For example:
This evidence-driven approach reduces the likelihood that problems are handled informally. Informal handling might feel faster, but it often increases risk and makes future audits harder.
Instead of assuming “one size fits all,” use this comparison table to align software capabilities with your internal needs. This table is conceptual and does not replace vendor plan comparisons.
| Operational need | What to look for in Intuit Payroll | Why it matters |
|---|---|---|
| Recurring pay processing | Repeatable workflow for each pay period, stable calculation logic, clear previews. | Reduces variability and mistakes across months. |
| Employee changes | Structured updates for pay rates, status, and deductions; clear cutoff behavior. | Prevents last-minute errors and inconsistent pay outcomes. |
| Deduction management | Configurable recurring deductions and straightforward adjustments. | Improves accuracy for benefit and policy-driven deductions. |
| Manager review | Clear payroll summaries that support review and sign-off. | Improves governance and audit readiness. |
| Reporting for filing | Outputs that reflect payroll history in an organized manner for tax reporting workflows. | Supports timely and consistent compliance activities. |
| Accounting alignment | Integration paths or export options that match how your accounting team records payroll. | Reduces reconciliation effort and month-end confusion. |
It’s worth emphasizing that a payroll platform’s “feature list” is not the same thing as operational fit. Two teams can both “run payroll” successfully but experience different outcomes. One team might have strong internal controls and produce filing-ready reports on time; another might struggle with reconciliation, repeated corrections, and last-minute approvals.
So when you evaluate Intuit Payroll, tie each capability back to a control objective. For example:
This control framing connects software functions to business governance—making evaluation more reliable than relying on subjective impressions.
Payroll compliance is jurisdiction-specific. For authoritative requirements (such as reporting timelines and withholding rules), rely on official government resources and, when needed, licensed tax professionals. For general context on payroll reporting and employer obligations, businesses commonly reference:
As a general benchmark for industry practices (not a substitute for legal advice), many organizations also consult recognized HR and payroll industry materials from reputable research firms and professional associations.
Note: The article avoids specific claims about pricing amounts, guarantees, or performance metrics unless confirmed by official sources. For exact pricing and plan features, verify the current offer details via Intuit’s official documentation or authorized reseller information.
Compliance framing also means adopting the mindset that payroll systems don’t “create compliance.” Instead, they help you produce accurate calculations and consistent records that you can support during audits or employee disputes.
Therefore, even with a strong tool, your internal compliance readiness still depends on how you manage:
If your organization operates in a regional model—where teams are distributed but managed under a single payroll governance approach—you may find that payroll administration benefits from standardized processes. A “nearby” staffing pattern often means:
In practical terms, even if employees are spread across a “nearby” area, your payroll system should enforce uniform data standards and approval controls so that pay outcomes do not vary by which office or manager enters data.
To support this kind of distributed operation, many organizations implement a “single source of truth” policy for payroll-related data. That could mean one HR team owns the master employee records, while local managers submit changes via a defined request process. The key is to avoid having multiple versions of the employee record circulating in email threads or separate spreadsheets.
When adopting uniform payroll governance, you can also create local “operating instructions” that translate the payroll workflow into everyday steps for managers:
This reduces friction, improves data quality, and ensures the payroll system is used consistently across locations.
Payroll accuracy is strongly correlated with data quality. That means your implementation should include explicit strategies for detecting anomalies before a payroll run. Even if the payroll software calculates correctly, poor inputs can still lead to incorrect outputs.
Here are practical data quality controls you can design around Intuit Payroll (and any payroll platform):
When these checks are not explicit, teams often discover data issues only after pay stubs look wrong or employees report problems. Creating a pre-run verification stage shifts detection earlier in the process.
To make the controls easier to operate, you can define what “pass” looks like. For example, a “completeness pass” might require that 100% of active employees have a valid pay schedule and a valid deduction profile. A “range pass” might require that pay rate values fall within a predefined tolerance set by HR and finance policy.
Once defined, you can assign ownership for these checks to a payroll administrator or reviewer role. The payoff is not only fewer errors, but also clearer accountability if something goes wrong.
Approval workflow is where payroll control either becomes reliable—or stays informal and reactive. Even with robust payroll tools, if the organization does not set consistent review criteria, errors will slip through.
An effective approval workflow is typically built on three principles: separation of duties, structured review criteria, and documented sign-off. Separation of duties means the person entering data is not the same person approving the final payroll run (or at least not without a second review step). Structured review criteria means reviewers don’t only look at totals; they also verify key items likely to cause discrepancies.
Structured review criteria often includes:
In distributed operations (or high-volume recruiting), reviewers may need a sampling strategy rather than full review. A sampling strategy is still a control as long as it’s consistent and based on risk. For example, you might always review all employees who:
When you define these rules ahead of time, the workflow becomes more predictable under pressure. It also makes it easier to train new reviewers because the checklist is stable.
Finally, documented sign-off matters. Even if the payroll tool stores payroll run records, storing reviewer sign-off evidence supports internal accountability and can accelerate audits or employee dispute resolution.
One of the most overlooked aspects of payroll implementation is the reconciliation process between payroll results and accounting entries. Payroll outputs create transactions that must be reflected in the general ledger. If the integration is manual or semi-manual, reconciliation is where discrepancies surface.
A robust reconciliation approach typically includes:
If payroll and accounting are not aligned, teams often see “mystery” differences at month-end: numbers don’t tie out, journal entries feel like guesswork, and corrections become frequent. Those problems are operational—not just technical—and are preventable with clear reconciliation steps.
To reduce confusion during the first few months after go-live, you can adopt an intensified reconciliation period. That might include verifying every payroll run’s totals against accounting entries, then gradually reducing frequency once confidence increases.
Additionally, reconciliation should be assigned to a specific owner with a timeline. When reconciliation is nobody’s job, errors persist longer, and you lose the opportunity to fix them quickly.
Test cycles are essential, but not all test cycles are equal. Some organizations run a test payroll and then assume everything is fine. A better approach is to structure testing around real-world scenarios that are likely to occur.
Testing scenarios can include:
Another important testing principle is to test reporting outputs, not only pay stubs. Many teams verify employee pay but fail to validate that the reporting used for filings matches the payroll history correctly. If the output is wrong, compliance risk increases.
When you plan the test-to-production rollout, ensure you also plan for how you will “cut over” historical data. If you are importing history or switching from a legacy payroll process, define what history will be carried into the new system, what will be archived, and how you will reference old payroll records if needed.
Finally, have a rollback plan for configuration mistakes. Rollback doesn’t always mean reversing everything; it might mean pausing production payroll, correcting configuration, and re-running the payroll with an agreed correction process. The key is to define what “pause and fix” means so decisions are not made ad hoc.
Even with strong controls, corrections are sometimes necessary. The critical question is not whether corrections will happen, but how the organization handles them. A good correction workflow reduces the time employees spend waiting for corrected pay and helps the organization maintain audit-ready records.
A mature correction workflow includes:
When you build correction workflows during implementation rather than after problems occur, you avoid improvisation under stress. Improvisation often leads to incomplete documentation, inconsistent accounting treatment, and confusion about which pay period is “correct.”
A practical approach is to create an “exception log” template used whenever corrections occur. The template might include employee identifier, payroll period, original issue, correction type, approval evidence, and final resolution confirmation. Over time, this log becomes a useful internal control artifact and can reveal patterns (e.g., a particular deduction mapping error that recurs).
Payroll systems process sensitive personal information and compute tax-related outputs. Therefore, access control is part of operational risk management.
While this article does not attempt to provide vendor-specific security settings, you should plan governance in a way that aligns with standard internal controls:
When distributed teams are involved, you should also plan for training and consistent access practices. Many payroll incidents happen not because the calculation engine is wrong, but because someone had access they didn’t need or lacked training on how to safely submit changes.
Security and governance are part of compliance indirectly: if you can’t trace what happened and who changed what, your organization becomes more vulnerable to disputes and audit friction.
Integration is where many payroll implementations become complex. The goal is not only technical connectivity; the goal is workflow alignment. If HR, time tracking, and accounting all operate on different schedules and data definitions, the payroll process can become a patchwork of reconciliations and manual fixes.
To integrate effectively, define the “system of record” for each type of data:
Then define how each system sends and receives data, and how you manage timing. Timing matters: if HR changes are entered after payroll cutoff, those changes may not reflect correctly for the payroll period. If time data arrives late, you may need a policy for how to handle late hours (e.g., process next payroll or create an off-cycle adjustment).
To avoid workflow breakage, you can create a “handoff checklist” that defines what must be completed before each payroll run. For example:
This checklist becomes especially valuable in busy periods (end-of-month, holiday seasons, or times of rapid hiring).
Accurate payroll isn’t just an internal control issue—it’s a trust issue. Employees compare their expected pay to what they receive and want clarity when something changes.
While payroll software generates pay stubs and payroll outputs, communication practices determine whether employees perceive payroll as reliable. Many organizations reduce payroll inquiries by standardizing the explanation of common scenarios:
A helpful practice is to create an internal “FAQ for managers” and a separate “employee-facing guidance” document that explains how to read pay stubs. When employees understand the structure of earnings and deductions, they are more likely to ask precise questions rather than general complaints.
Transparent communication also supports governance. If employees know the company has clear cutoffs and correction timelines, they are less likely to pressure managers for last-minute changes outside the defined process.
Intuit Payroll is used to help businesses process payroll runs, calculate pay based on configured employee data, generate pay stubs or payroll documentation, and support reporting workflows related to payroll history. Its effectiveness depends heavily on accurate employee setup, well-defined pay rules, and a controlled approval process before each payroll run.
Start by verifying that employee master records are complete and consistent: names, addresses, compensation details, pay schedule, and any deduction-related inputs your organization applies. Then confirm that your internal process captures changes before the payroll cutoff. If your team imports data, perform a reconciliation check after import and before production processing.
Many businesses coordinate payroll results with accounting workflows. The key is to ensure payroll totals can be reconciled with your accounting entries. If your business requires exports or integrations, define your chart-of-accounts mapping and reconcile after each payroll run, especially during the first month of operation.
Common reasons include incorrect pay rates, missing or late employee updates, deduction misconfiguration, or data entry errors. Corrections are usually smoother when the business has a documented correction workflow and performs structured payroll review steps before processing.
Use a written payroll calendar that specifies cutoff times, who can submit employee changes, who reviews payroll previews, and when final approval is due. Consistent deadlines reduce “rush” entries and help prevent late changes from being processed incorrectly.
Payroll software supports calculation and reporting workflows, but the business retains responsibility for ensuring correct compliance. Organizations should validate obligations using official government guidance and consult qualified tax or legal professionals when needed.
Payroll pricing typically varies with plan type and business size, often factoring in employee count and feature requirements. Because pricing can change, confirm current options from official Intuit documentation or authorized channels before budgeting.
Expect a heightened control period: run payroll previews carefully, complete post-run reconciliations, document any corrections, and refine your internal processes (data entry standards and approval steps). Many organizations find that tightening these controls in month one prevents recurring issues later.
Retention needs vary by jurisdiction and company policy. Generally, businesses should keep payroll summaries and supporting documentation sufficient to address employee inquiries and potential audit requests. Use your organization’s retention schedule and consult official guidance where required.
Implement a structured review: compare pay previews against expectations (hours, rates, deductions), reconcile totals to internal records, and spot-check employee pay stubs for common errors. Doing this before you process reduces corrections after the fact.
Intuit Payroll can streamline payroll administration by organizing employee data, pay calculations, and reporting workflows into a consistent operational cycle. However, the software’s benefits depend on disciplined setup—accurate employee inputs, clear pay rules, defined approval steps, and a reliable correction process when exceptions occur. Businesses that treat payroll like a governed process—rather than an ad-hoc task—typically experience fewer disruptions and clearer reporting outcomes.
If you’re considering Intuit Payroll for your organization, focus your next actions on readiness assessment, data quality, and a test-to-production rollout plan. Those fundamentals often determine whether payroll automation becomes an efficiency advantage or a source of avoidable rework.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

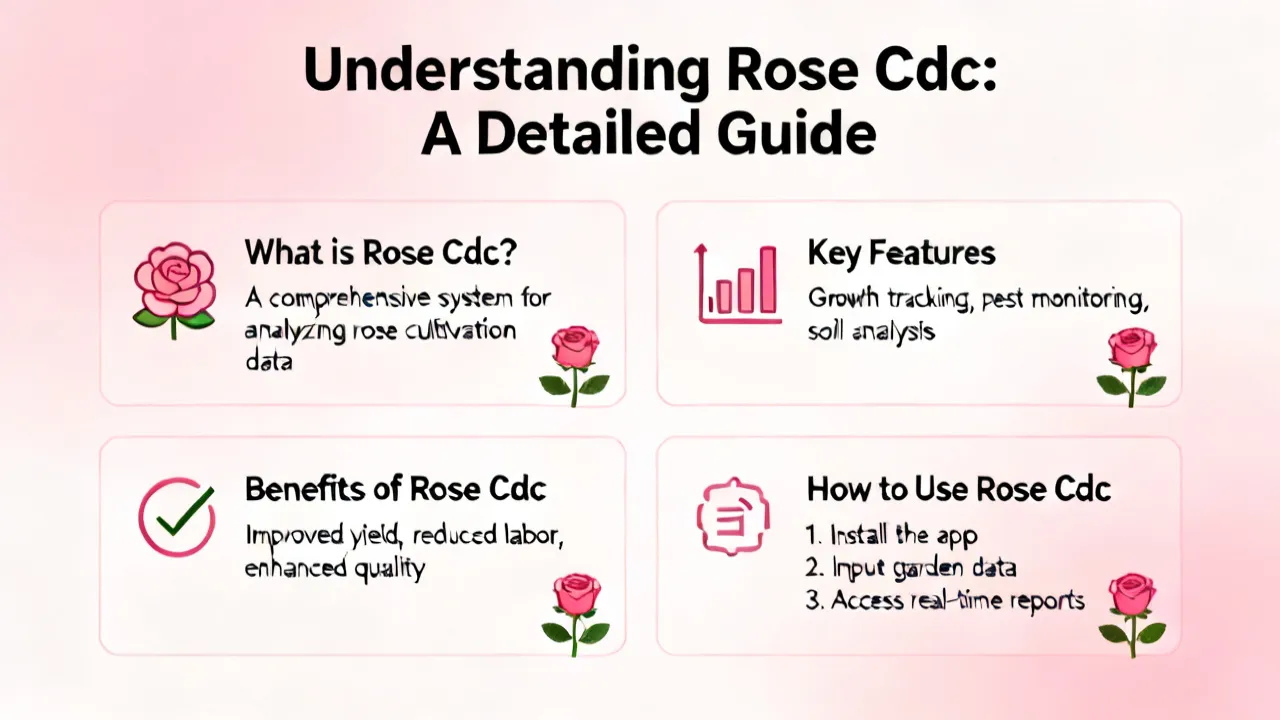
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.
