This guide explains how to evaluate Intuit Payroll for your organization, focusing on setup workflow, compliance considerations, and practical decision criteria. It provides objective background on payroll administration, the role of payroll systems in managing wages and taxes, and how buyers typically assess vendors. A comparison table and requirements checklist follow.
Choosing Intuit Payroll is usually less about novelty and more about reducing operational friction. Payroll is not a one-time setup task; it is a repeatable operating cycle that depends on data accuracy, consistent processing rules, and dependable outputs. For many organizations, the “pain” isn’t only that payroll has to be processed—it’s that payroll must be processed reliably, in a way that supports internal controls, produces audit-ready records, and adapts to real-world changes like new hires, changing pay rates, bonus payments, off-cycle corrections, and shifting deductions.
In practice, selecting the right payroll solution influences multiple daily or near-daily realities: how employee pay details are organized, how tax calculations are triggered, how deductions and benefits are maintained, how payroll changes are recorded, and how quickly the team can troubleshoot when something doesn’t look right. For organizations that run weekly cycles, handle variable hours, or manage multiple pay items (such as commissions, reimbursements, or recurring deductions), a payroll platform that standardizes inputs and calculations can significantly reduce manual workarounds.
From an industry-expert perspective, the critical question is rarely “Can payroll be processed?” It is instead “Can payroll be processed reliably, with traceable decisions, and with controls that align with your jurisdiction’s requirements?” That’s where feature evaluation and implementation planning determine outcomes. Even the best payroll configuration can fail if the organization does not enforce consistent input standards, clearly assigns ownership, or lacks a disciplined way to handle corrections and approvals.
Intuit Payroll matters operationally because payroll systems often become the system of record for compensation-related events. Once a payroll system is adopted, teams tend to rely on it for recurring computations, payroll summaries, and employee-facing documentation. When that system is stable and well-governed, payroll becomes predictable: the payroll team can focus on exceptions rather than fighting daily inconsistencies. When governance is weak, the organization may end up compensating with spreadsheets, manual rekeying, or ad hoc fixes that make payroll harder—not easier—to manage.
Payroll software generally supports a structured lifecycle. While the exact capabilities differ by vendor and subscription plan, payroll platforms commonly follow a flow that looks like this: collect employee inputs (hours, pay rates, deductions, benefits, and any applicable adjustments), validate those inputs, compute gross pay and deductions, calculate taxes and statutory withholdings, generate net pay results, and produce statutory and internal records (payslips, audit logs, historical payroll information, and reporting exports).
Because payroll touches wages, taxes, and employee documentation, buyers should treat payroll software as a controlled system rather than a simple calculator. In a controlled system, configuration and processing decisions need to be consistent, traceable, and auditable. In many organizations, the success of payroll software depends as much on operational rules and implementation quality as it does on core calculation features.
While no two companies structure their payroll operations exactly the same way, payroll platforms commonly assist with:
To evaluate payroll solutions objectively, buyers often compare how each vendor supports the operational lifecycle end-to-end: not only calculations, but also how the system behaves when something changes late. The strongest payroll implementations include clear handling of edge cases: retroactive pay adjustments, corrected tax settings, terminations, rehires, and off-cycle payments that occur when payroll is already “locked.”
Because payroll is a compliance-adjacent domain, software should also preserve the reasoning behind outcomes. For example, when net pay is different from what an employee expected, the organization needs to be able to show what inputs and rules produced that outcome. This is why audit-ready reporting and edit traceability are so important for payroll buyers.
Even when a vendor is widely used, your organization’s structure and payroll rules determine whether the fit is strong. A “good” payroll solution is one that matches your pay model, your compliance obligations, your data sources, and your internal operating style. The evaluation categories below highlight issues that frequently affect total operational effort after go-live—meaning the true “cost” of payroll is often the time and risk created by misfit, not only the subscription price.
Configuration fit is about whether the payroll system can model your real pay practices without heavy workarounds. Many payroll difficulties arise when organizations adopt a payroll product and then discover that their pay rules cannot be expressed cleanly.
Compliance isn’t only about generating tax figures; it’s also about repeatable, reliable workflows that produce records you can defend in an internal review or in the event of an external inquiry. Many organizations learn this the hard way after go-live, when they discover they cannot easily reconstruct what happened during a given payroll.
Payroll accuracy depends heavily on upstream data quality. If you rely on HR systems for employee details and time tracking tools for hours, then payroll either becomes the receiving system of clean data—or a place where inconsistent data has to be corrected repeatedly.
Many teams evaluate whether Intuit Payroll can work with their HR records, time tracking systems, and accounting practices. When integration is strong, teams often reduce manual re-entry and the risk of inconsistent pay rates or outdated employee details. Integration also influences how quickly you can respond to payroll corrections and how reliably you can reconcile payroll data with timekeeping data.
In evaluation, ask:
Even if a vendor offers integration capabilities, practical fit matters. For example, some organizations experience issues when the time system records hours differently (e.g., rounding rules, approval statuses, time-off categorization) and payroll expects a different structure. You want a workflow that clearly defines how approved time becomes pay inputs.
An industry pattern is that payroll systems fail not because core calculations are wrong, but because process breakdowns occur. Causes include unclear ownership, insufficient training, or inconsistent input standards. During evaluation, focus on usability in real conditions—peak workload, late changes, and emergency corrections.
Ask operationally:
Additionally, evaluate whether the payroll platform supports role-based separation. If payroll clerks can freely change pay rules without approval, the risk profile increases. Conversely, if managers can request changes but payroll admins control configuration and final approvals, the organization can maintain controlled governance.
Payroll includes sensitive information: employee identifiers, compensation, deductions, and sometimes bank or payment details. Security and access control are therefore operational requirements, not “nice to have” features.
Before adopting, confirm:
From a governance standpoint, access control reduces fraud risk and reduces mistakes by limiting who can change what.
Payroll systems must support your near-term plan: new departments, new geographies, seasonal workers, acquisitions, or simply increased headcount. Evaluation should consider how the system scales operationally.
Consider:
Scaling isn’t only about technology capacity; it’s about whether your team can continue processing payroll with the same quality as you grow.
You asked for price information, supplier details, and location-specific content. However, the prompt does not include explicit price figures, specific supplier names beyond “Intuit Payroll,” or a specific location to localize. Because payroll costs can change by plan, region, employee count, and feature bundle—and because sharing unverified pricing would be unreliable—this section focuses on a responsible pricing evaluation framework rather than inventing or guessing numbers.
Industry-standard approach to pricing evaluation:
Supplier details: In this guide, the supplier referenced is Intuit Payroll. For exact plan structure and any regional variations, you would typically confirm the latest offering details directly from the vendor’s official materials, your authorized reseller/partner, or your account representative. Plan structures and included features can change over time, so it’s best to validate the current subscription details for your region and intended employee count.
Practical buyer tip: Ask for a written quote that itemizes what you are paying for—base plan, number of employees, frequency of runs, and any add-ons. Then estimate internal effort for a 90-day period post-launch (setup, first payroll runs, reconciliation, and training). This gives you a more realistic total cost of ownership than software licensing alone.
Implementation success often comes down to disciplined preparation and a clear operating model. Below is a practical workflow aligned with how payroll operations are commonly structured in professional services, small-to-mid businesses, and multi-department environments. Even if your organization already has payroll experience, this kind of structured approach helps reduce avoidable errors during go-live.
Document which team owns which inputs. Examples include employee onboarding fields (HR ownership), pay rates (HR/Finance ownership), deductions and benefits enrollment (Finance/HR ownership), and time data (timekeeping system ownership). Also define ownership for payroll approvals and corrections.
This step reduces the “spread-out spreadsheet” problem where payroll details exist in multiple tools and humans manually reconcile discrepancies. When ownership is clear, the team can enforce data entry quality at the source.
Before you run the first payroll, ensure employee records include correct employment details, pay rates, and deduction configurations. If your organization uses multiple pay rates or complex pay rules, validate edge cases such as:
If possible, reconcile your existing payroll output with your current process: compare what your old system would have produced for a sample scenario against what the new system produces. This is often where misconfigurations appear.
Set payroll schedules: pay periods, cutoff dates, processing dates, and when data is considered locked. Then define who can edit payroll data and who approves changes—especially for corrections after cutoff.
Approval rules should reflect your internal control philosophy. For example:
Clear cutoff and approval logic is essential. Without it, you often end up with conflicting versions of payroll inputs, and the organization cannot confidently explain why payroll outcomes changed.
Payroll tax behavior is jurisdiction-specific and can be sensitive to employee work location and employment status. Confirm that jurisdictional settings match where employees work and where withholding rules apply.
For best outcomes, verify that reporting outputs can be reconciled with your accounting workflow or your advisor’s filing process. This includes not only the numbers, but also the formats and categories used in reporting exports.
Practical validation tasks often include:
If you have employees in multiple jurisdictions, create a test matrix: one or more scenarios per jurisdiction. A common mistake is to test only the “main office” state or country and assume others are similar.
Conduct a test payroll in an environment that supports it (where available) and verify:
Test the scenarios that represent the real world in your organization—not only the simplest case. For many payroll teams, the most valuable test scenarios include:
During testing, record issues in a structured way: scenario description, expected result, actual result, severity, and the remediation path (configuration change, data change, or process change). This helps prevent the “fix it and forget it” pattern that creates future surprises.
Training is a risk mitigation tool. Provide role-based training:
Keep standard operating procedures (SOPs) concise but complete. SOPs should include:
Also ensure training covers not just “how to click,” but “how to verify.” Payroll staff should know what checks to perform before submission—especially around pay types, deductions, and approvals.
For the first one or two cycles, run enhanced checks and reconciliation. Compare payroll results to your expected outcomes, and verify:
Capture lessons learned. For example, you might notice recurring data entry errors (such as incorrect pay type selection), misunderstandings of how deductions are calculated, or confusion over eligibility dates. After go-live, refine your SOPs and data validation rules. If you have frequent exceptions, consider adding pre-payroll checklists or a “preflight” step that catches errors early.
You requested a comparison table that rephrases additional important information into structured decision-making guidance. The table below serves as a supplement that compares common evaluation decisions during Intuit Payroll selection. Because your prompt did not provide external pricing figures, no numerical pricing data is displayed. Instead, the table focuses on decision points that affect implementation quality and ongoing operational effort.
| Category | What to compare | Why it affects outcomes | Buyer condition / requirement |
|---|---|---|---|
| Configuration depth | Pay types, deductions, recurring adjustments, one-time payments | Reduces manual workarounds and payroll corrections | Confirm your real pay rules can be modeled before first payroll |
| Audit trail | Change history, edit logs, approval workflow | Supports internal reviews and compliance readiness | Define who can edit and who must approve changes |
| Reporting and recordkeeping | Export formats, payroll reports, historical data access | Speeds reconciliation and advisor/accountant workflows | Test outputs against your current accounting/reporting needs |
| Data integrity | Employee onboarding fields, time data handling, imports | Improves accuracy and reduces rework | Require validation checks for rates, dates, and deductions |
| Operational support | Training resources, admin permissions, help documentation | Shortens onboarding time and lowers error rates | Assign internal champions to manage the transition |
| Exception handling | Off-cycle runs, corrections after cutoff, retro adjustments | Prevents chaos when real-world events don’t align with payroll windows | Document correction workflows and test them during implementation |
| Integration & data flow | HR/time synchronization, refresh logic, mapping rules | Reduces duplicate entry and improves upstream data quality | Validate data mapping end-to-end with sample employees |
Before you switch payroll systems, professional payroll operators typically require a short list of conditions. These are not vendor claims; they are operational requirements that help you avoid preventable errors. Use this checklist as a governance-oriented readiness assessment.
One practical way to improve rollout safety is to treat the first payroll run as an “audit rehearsal.” That means you perform deeper checks than normal and document the reasoning behind final outputs. After two or three cycles, you can reduce the frequency of checks once confidence is established.
Payroll and payroll tax requirements are governed by jurisdiction-specific regulations, which can change. For objective context, organizations often rely on official guidance from government tax authorities and recognized labor or accounting frameworks. Examples of reliable source categories include:
If you share your country or region—and whether employees are in one location or multiple jurisdictions—the requirements checklist and reporting workflow context can be localized around the relevant official requirements and reporting cadence.
Even with payroll software, vendors rarely know your internal accounting workflow, your organizational policies, or the exact operational controls you must satisfy. That’s why source-based guidance and an internal compliance review remain important, especially for organizations with complex pay arrangements or multi-jurisdiction employment.
Intuit Payroll is typically used to streamline payroll processing tasks such as calculating pay based on configured rules, supporting payroll recordkeeping, and producing payroll-related outputs for administration and reporting. The top fit depends on how closely your organization’s pay and deduction structures match the system’s configuration model, and how well its workflows align with your internal approval and cutoff practices.
For example, if your organization has recurring deductions and consistent pay schedules, a payroll platform can reduce manual work. If your organization has variable hours, complex earnings components, and frequent corrections, you will want to validate the system’s exception handling and reporting traceability features during evaluation.
Most organizations reduce payroll errors by running a controlled test cycle, validating employee pay profiles, enforcing clear cutoffs, and using role-based permissions. They also write a short SOP that covers who enters time/pay changes, who approves them, and how corrections are documented.
Additional error-reduction techniques include building a preflight checklist for each payroll cycle and running “sample payroll scenarios” that include common edge cases (retroactive rate changes, termination/final pay, and special deductions). The key theme is to validate not only calculations but also workflows: approvals, audit logs, and reconciliation outputs.
You should confirm that the system provides consistent payroll reports, historical access, and an audit trail of key changes. From an expert operations view, audit readiness is less about having “more reports” and more about being able to explain how pay outcomes were reached.
When you review audit trails, look for the practical attributes you need during troubleshooting:
If those answers are unclear, you may need to adjust internal workflows even if the calculations are correct.
Pricing structures commonly reflect employee count and selected feature bundles, but the exact model varies by plan and region. Because the prompt did not provide specific numbers, the recommended approach is to request the current plan quote and compare total cost of ownership, including implementation effort and internal time.
When comparing quotes, consider asking for:
Integration capabilities depend on the exact configuration and tools used. In practice, the goal is to avoid duplicate data entry and to ensure that timekeeping and HR changes flow cleanly into payroll. During evaluation, validate how employee data and time inputs flow into payroll and whether adjustments can be traced and corrected cleanly.
Even if integrations exist, you should test them with real or representative data. A common risk is that mappings are technically possible but operationally confusing, leading staff to bypass integration and re-enter data manually—defeating the purpose of integration.
At minimum, ensure employee records are complete and accurate, cutoffs are defined, approvals are assigned, and a reconciliation plan exists. If any pay items are complex (commissions, variable hours, retro adjustments), allocate additional validation time.
A “minimum” requirement list is useful, but you should also consider “minimum sufficient confidence.” If your organization is adopting new workflows, you may need extra time for training, scenario testing, and reconciliation rehearsal during early cycles.
For organizations assessing Intuit Payroll, the decision should be guided by operational fit: pay rule coverage, audit trail clarity, reporting reliability, and a rollout process that emphasizes data integrity and controlled testing. When implementation is treated as a governance exercise—not merely a software install—payroll becomes more predictable, easier to reconcile, and simpler to explain during internal reviews.
The most successful payroll transitions often share a few behaviors: they invest in understanding real payroll scenarios; they define ownership for inputs and approvals; they test high-risk edge cases before processing; and they use reconciliation and feedback loops during the first few payroll cycles. That operational discipline turns payroll software into a dependable system of record rather than a source of recurring friction.
If you want localization: share the relevant country/region and whether your employees are in one location or multiple jurisdictions, and the requirements checklist and reporting workflow context can be tailored accordingly, while keeping the guidance objective and source-based.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

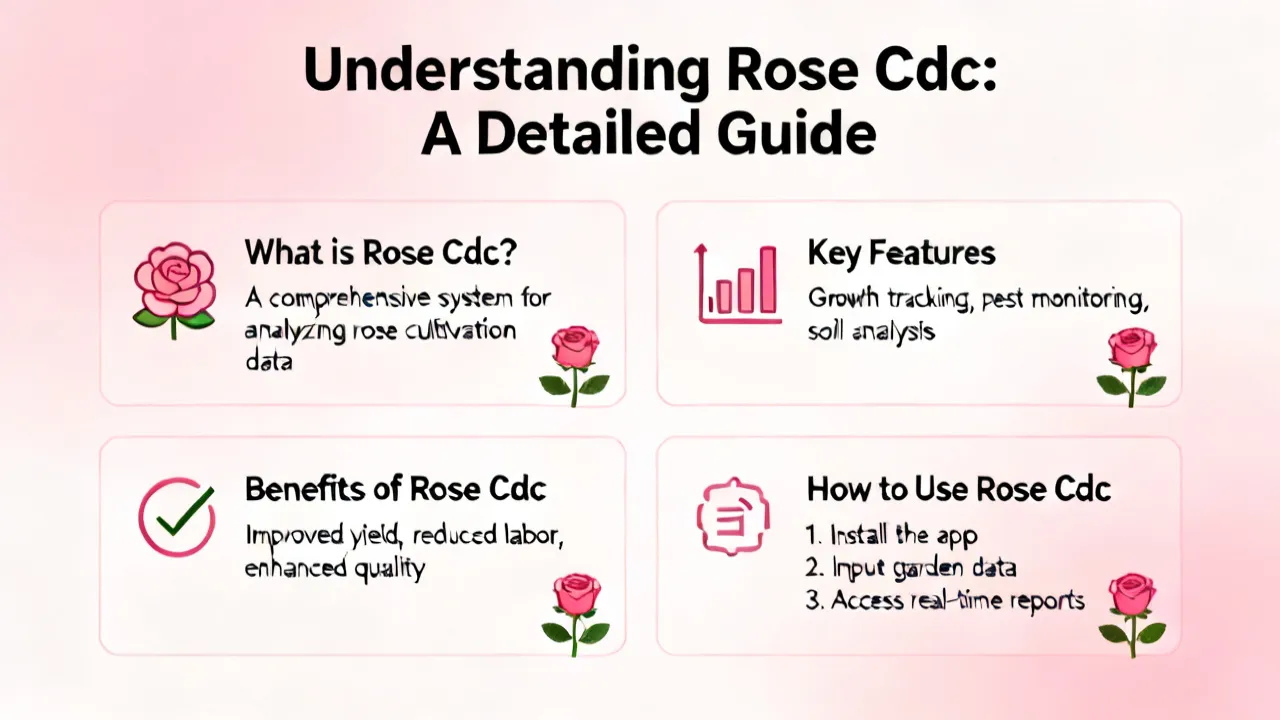
Understanding Rose Cdc: A Comprehensive Guide
This article provides an in-depth exploration of Rose Cdc, a term rapidly gaining attention in specific industries. Our discussion delves into the significance and application of Rose Cdc, its potential impact on various sectors, and expert insights into its future developments. This comprehensive analysis is designed to inform readers about the multifaceted aspects of Rose Cdc, its current applications, and potential advancements.
Understanding Compliance and AML Strategies
This article delves into the intricate realm of Compliance and Anti-Money Laundering (AML) strategies, highlighting their significance in the corporate world. Compliance AML refers to the organizational adherence to legal standards and regulations to deter financial crimes, ensuring transparent and ethical financial practices. This comprehensive guide examines these strategies' complexities and their pivotal role in safeguarding economic integrity.
Mastering Inbound B2B Strategies
The foundation of successful B2B strategies often lies in the effective implementation of inbound marketing techniques. In today's globally connected business environment, inbound B2B strategies have become critical for companies seeking to engage target audiences, optimize lead generation, and establish long-lasting partnerships. Understanding these strategies is essential for companies aiming to thrive in competitive markets.
Exploring B2B MBA Opportunities
Dive into the dynamic world of B2B MBA programs, designed for professionals seeking to enhance their strategic and management skills in a business-to-business context. This comprehensive guide discusses the significance of B2B MBAs in today's market, highlighting how these programs equip leaders with the expertise to navigate complex B2B relationships and drive business success.
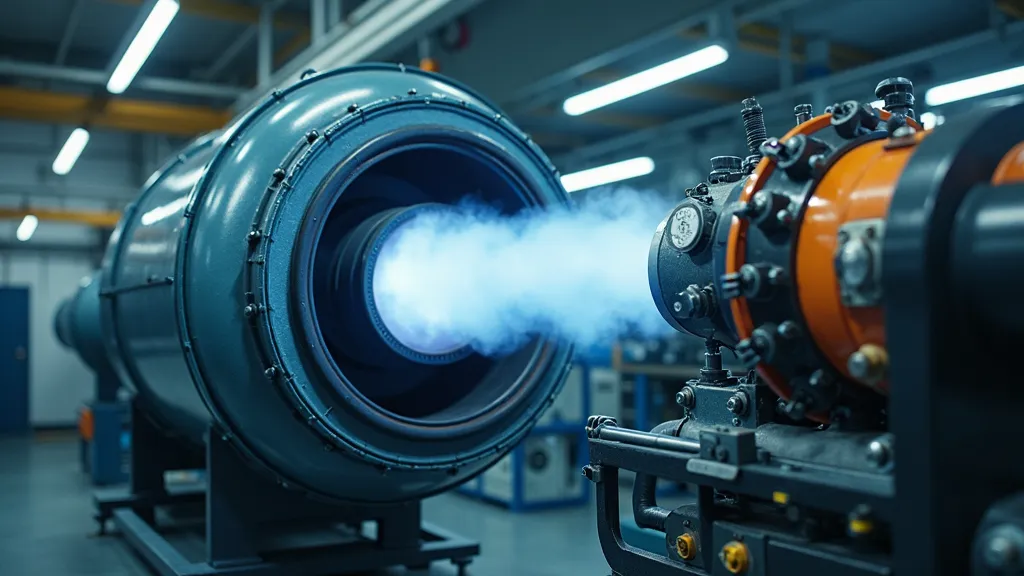
Understanding Whitewater Regenerative Blowers
Whitewater Regenerative Blowers are essential in various industrial applications for their efficiency in moving air and gases. These blowers are known for their durability and ability to operate continuously, making them a preferred choice for industries ranging from wastewater treatment to aquaculture. This article explores their features, benefits, and applications, offering readers a comprehensive understanding of their importance in modern industry.
Mastering Employee Retention Strategies
Employee retention has become a critical aspect of organizational success, particularly in the dynamic landscape of 2020. As businesses strive to maintain a stable and productive workforce, understanding effective retention strategies is essential. This article delves into key methods for enhancing employee satisfaction and retention, offering a comprehensive guide for HR professionals and business leaders alike.
