This guide explains how to manage Square Payroll 1099 reporting for independent contractors, focusing on compliant workflows, accurate recordkeeping, and practical verification steps. Objectively, “1099” requirements are federal tax forms used to report certain payments. Proper classification, contractor onboarding, and timely data checks reduce filing risk and improve audit readiness across payment processors and payroll tools.
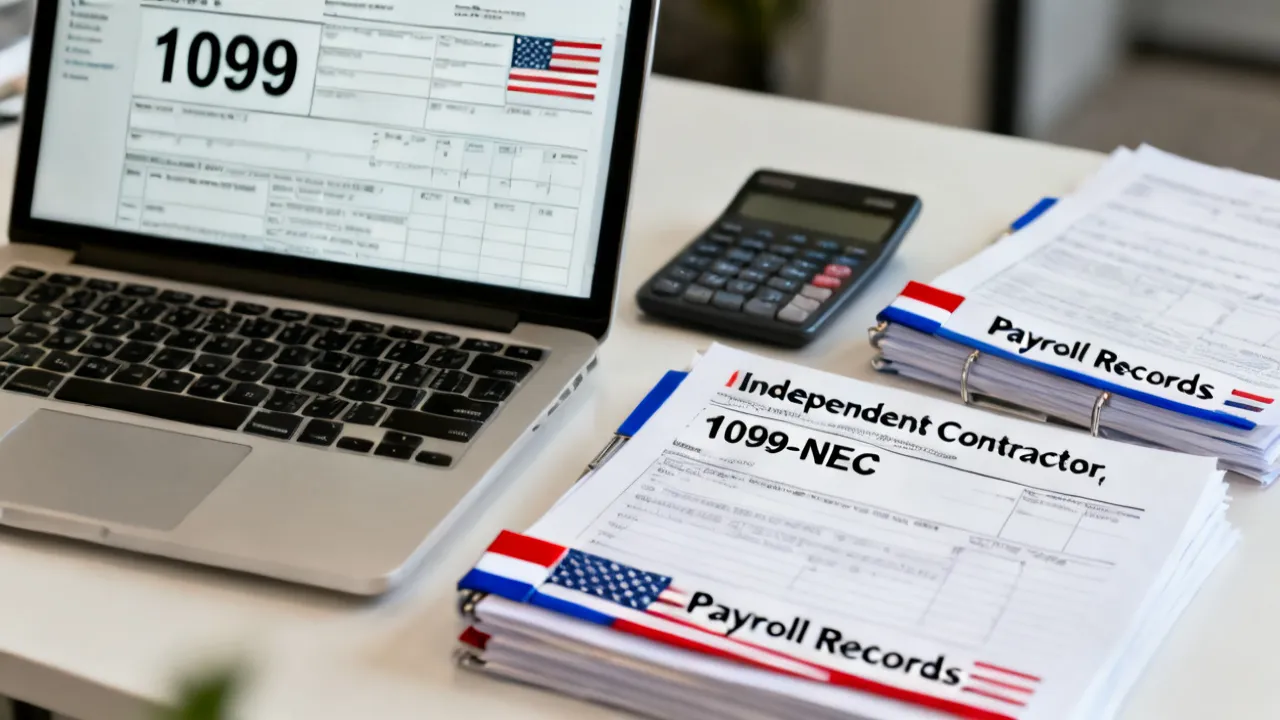
When you use Square Payroll 1099 workflows, the core goal is simple: ensure the payments you report align with how your contractors are classified and how the data is captured. From a compliance and operations perspective, the biggest failure points aren’t usually “software bugs”—they’re mismatches between contract status, tax forms, and the underlying payment records you rely on when preparing 1099 reporting.
In practice, a strong 1099 process means you can answer, quickly and objectively: Who was paid? How were they classified? Which payments count? What amounts were captured? What documentation supports the totals? Then, you can reconcile what your contractors received against what your records indicate—without relying on assumptions.
That “without assumptions” point matters, because IRS notices and contractor disputes often come from exactly the kinds of gaps you can avoid with a disciplined workflow. If your numbers are correct but your documentation is missing, you may still struggle to respond. If your documentation is good but the workflow allowed last-minute edits, you may still file incorrect totals. The best systems prevent both.
Federal tax reporting for payments to independent contractors is primarily handled through IRS forms such as Form 1099-NEC (nonemployee compensation) and related variants depending on payment types. Businesses that pay nonemployees generally have reporting obligations under U.S. Internal Revenue Service rules, including requirements around when a contractor’s payments must be reported and what information must be captured.
Because classification and reporting are regulatory topics, very organizations treat 1099 reporting as a governance system: consistent data collection, controlled workflows, periodic reconciliation, and documentation retention. Payroll platforms and payment tools can support the workflow, but they cannot substitute for correct classification and complete contractor onboarding.
For baseline rules, consult the IRS guidance for information returns and Form 1099 filing requirements, including IRS resources on information reporting and Form 1099-NEC instructions. Those resources explain what the payer must do, when reporting is required, and how to handle errors or missing tax information.
One of the most common misconceptions is thinking that “1099 is only a finance task.” In reality, 1099 accuracy is often determined upstream by operations decisions: how you engage labor, how you pay, whether you reimburse expenses through the same payment mechanism as service fees, and how quickly you collect tax forms (and update them when wrong). Square Payroll-related tooling can help centralize or export data, but it can’t decide whether a given payment category is reportable. That decision lives in your process.
The phrase Square Payroll 1099 usually points to how a business can use Square’s payroll-related capabilities (and associated data outputs) to support contractor payments and the information needed to prepare 1099 reporting. In an expert workflow, the value isn’t merely generating a form—it’s building confidence in the inputs.
From an operational standpoint, the process normally includes:
Even when a tool provides the reporting structure, the business remains responsible for correct reporting. Therefore, quality checks matter as much as the platform settings.
Additionally, in real organizations, “Square Payroll 1099” often intersects with other systems: accounting software, time-tracking tools, payment processors, expense management systems, and document repositories. The more systems you involve, the greater the need for a clear mapping between “where the data comes from” and “how it becomes the number you report.”
It’s helpful to think of your 1099 pipeline as a chain. If any link is weak—like using inconsistent contractor names, coding payments incorrectly, or failing to account for reversals—errors can propagate. A strong workflow includes checks at each link so you can detect where the chain breaks.
In compliance reviews and operational audits, the very common issues tend to fall into a few categories. Treat these as your checklist, because they are the places where companies lose accuracy:
Each of these issues is solvable with process design—documentation, controlled entry points, and scheduled reconciliation—rather than last-minute form generation.
To make these failure modes actionable, here’s how they typically show up in the field:
An industry-standard approach is to treat 1099 reporting like financial close: establish inputs, standardize rules for what counts, and then verify outputs against independent sources.
That means you’re not only asking “does the report run,” but also “can we trust the numbers under scrutiny.” A close process is designed for precisely this: catching errors early enough to correct them and preserving a trail of evidence.
Confirm that each contractor’s legal name and tax classification details are current and consistent. If you rely on contractor-provided information, set a workflow for review and correction before filing deadlines.
In practice, “validate identity” should include more than checking for blank fields. A strong workflow looks for:
Also, implement a procedure for documenting when you receive corrections. If a contractor updates their information, you should capture “what changed,” “when it changed,” and “how it affected reported totals.” Even small improvements in auditability can prevent major trouble if questions arise later.
Independent contractor agreements often outline scope, payment terms, and control expectations. But agreements alone do not determine tax classification; they are evidence. Your operational reality—how work is directed and controlled—should align with your classification approach.
While classification is a broader topic than 1099 reporting alone, your workflow should still incorporate a practical check: are you consistently treating the contractor type the same way across all operational touchpoints?
For example, you can reduce risk by ensuring that operational processes align with contractor expectations, such as:
Even if you ultimately rely on a tax professional for classification determinations, your internal workflow should ensure classification is not accidentally overridden by how the contractor is set up in Square (e.g., using employee-like settings, mixing roles, or storing them in a different category without a clear purpose).
Different payment types can be treated differently for reporting. Establish internal rules for what gets included in your 1099 calculations and ensure those rules match IRS instructions applicable to the payment type.
Important: This guide is informational and does not replace professional tax advice. If your payment mix is complex, consult a qualified tax professional.
A practical “reportable payment” policy should answer questions such as:
Where Square-related setups can help is by allowing you to distinguish payment categories and track them consistently. Where it can fail is if you rely on manual overrides too often, or if you treat “everything that goes to a contractor” as automatically reportable. Automatic assumptions are the fastest path to inaccurate reporting.
Use a periodic reconciliation routine so your totals are not a surprise at year-end. Reconciliation should identify:
This is especially relevant when you change systems mid-year or adjust how contractors are paid.
To make reconciliation effective, don’t just reconcile totals—reconcile logic. For example:
A useful operating practice is to maintain a “reconciliation log” with notes: what you checked, when you checked it, what discrepancies you found, and how you resolved them. This turns year-end reconciliation from a panic exercise into a routine verification.
You didn’t provide specific numeric “price” values or a supplier name to reference directly (and the keywords also don’t include explicit cost figures). In a compliance-focused guide, it’s top to avoid speculative pricing claims. Instead, consider cost components that typically matter for 1099 operations:
If you share your expected volume of contractors and payment types, you can estimate operational workload more reliably than by using generic “per user” assumptions.
Cost also has a compliance dimension. Even if a tool seems “cheap,” the true cost can be hidden in rework. Rework includes:
In other words, “cost” in a 1099 workflow is not only a subscription bill. It’s the total operational and compliance effort required to produce accurate, defensible totals on time.
Below is a practical supplement you can use to align your Square Payroll 1099 process with an objective compliance workflow. Note: the comparison is process-focused and does not represent guarantees about any specific filing outcome.
| Process Stage | What to Check | Why It Matters for 1099 Reporting | Typical Conditions/Requirements |
|---|---|---|---|
| Contractor onboarding | Identity details, tax information completeness, and effective start date | Prevents missing-reporting and downstream form corrections | Maintain documentation and ensure data is captured before payments are processed |
| Payment capture | Whether payments are coded to the correct category for reporting | Reduces inclusion/exclusion errors in totals | Use consistent internal coding rules and review exceptions |
| Data reconciliation | Compare platform outputs to accounting records and bank/processor statements | Improves confidence and audit readiness | Perform periodic checks (e.g., monthly or quarterly) rather than only year-end |
| Pre-filing validation | Check names and tax identifiers for obvious formatting mismatches | Reduces rejection risk and correction cycles | Use a final review step and document any corrections |
| Filing and record retention | Confirm submission status and store support files | Enables response to notices and supports internal controls | Follow IRS retention and organizational policies; consult professional guidance for your situation |
Rather than treating 1099 as a year-end scramble, build a “steady-state” system. This is the approach that tends to work top for medium-sized teams and organizations with recurring contractor activity.
The objective is to reduce the number of moving parts at year-end. Instead of trying to understand your entire contractor universe in December, you want to already have clean onboarding records, consistent coding, and reconciliation results you can trust.
At the end of each quarter, pull a contractor payment list and reconcile it to your accounting entries. If your organization uses multiple payment methods, verify that all relevant payment streams are included in your reporting dataset.
Quarterly mini-close is also a strong time to review outliers. Examples of outliers you should investigate:
When you see mismatches (a contractor missing totals, an amount unusually high or low, or inconsistent identifiers), document the cause and correct it promptly. Your goal is to keep exceptions small and well-understood.
A helpful way to operationalize exception handling is to define severity levels:
Also, define who owns each exception type. For example, identity errors often involve onboarding/HR/contract management, while coding errors involve finance operations. Ownership clarity prevents exceptions from lingering.
Maintain a record of contractor onboarding updates and identity corrections. When disputes arise—whether from the contractor or from internal review—having timestamps and change notes makes resolution faster.
Version control can be lightweight. The key is consistency. At minimum, you want:
This supports a more accurate story if you later discover that a contractor had the wrong TIN on file for part of the year. You can then evaluate whether corrections are needed and what documentation supports your position.
One of the hardest problems for many businesses is separating contractor services from reimbursable expenses in the payment records. Even if your accounting categories are correct, your reporting dataset must reflect the correct treatment of those amounts.
Operationally, segregation can be achieved through:
When teams fail here, they often create totals that are inflated because expenses were coded as services. Inflated totals can trigger contractor confusion, disputes, or potential correction needs.
You didn’t specify a particular city or country in the provided keywords, so the guidance remains general to U.S. federal tax reporting norms. In many U.S. business contexts, teams often coordinate 1099 readiness across finance, operations, and HR/contract management—reflecting a shared understanding that onboarding data and payment categorization are intertwined. If you operate near regulatory hubs or have frequent contractor onboarding, the same principles apply, but the workflow may need more frequent data checks to match operational pace.
In addition to the U.S. federal angle, some organizations also manage state-level reporting or local labor compliance in parallel. Even when your question is about 1099-NEC, it’s wise to recognize that state requirements can exist. Where state filing differs, your internal workflow should still preserve the “source of truth” so you can adapt reporting outputs without redoing the entire dataset.
Another localization consideration is contractor onboarding speed. In certain industries—creative services, logistics, field services, gig-based labor—contractors may start work quickly. If your policy requires tax forms before payment, you might need an internal process that supports “start quickly but onboard correctly,” such as collecting tax info at contract signature and verifying identity early.
It generally refers to using Square payroll-related processes and outputs to support independent contractor payment reporting, typically related to IRS information returns like Form 1099-NEC. The exact scope depends on your payment setup and how you classify contractors in your operations.
Practically, it also includes everything around those outputs: onboarding data collection, coding rules, reconciliation, and documentation retention. “Square Payroll 1099” is rarely just “run a report.” It’s “run the right workflow so the report is trustworthy.”
No. Tools can help produce the data needed for filing, but the business remains responsible for classification, completeness, accuracy of contractor information, and correct inclusion/exclusion of reportable payments. Use reconciliations and validation checks to reduce errors.
Even if a tool has 1099 templates or export features, you still need to ensure the data mapping from your contractor records to your reporting fields is correct. Incorrect mapping can happen when contractor identities are duplicated or when different systems store slightly different versions of the same name.
Follow IRS instructions that correspond to the payment types you make and your business context. Then apply a consistent internal rule set so your reporting totals reflect what the IRS expects for your payments.
A practical way to operationalize this is to create a policy that maps payment categories to “reportable” or “not reportable” (or “requires review”). Then, whenever a new payment type appears in your operations (e.g., a new kind of service contract or a new method of reimbursement), you update the mapping rather than improvising at year-end.
Incorrect taxpayer identity information can lead to filing issues or notices. Your top practice is to identify and correct issues before submission, and to document any corrections. If problems are discovered after filing, follow IRS guidance and your tax professional’s recommendations for correction procedures.
To reduce the chance you discover problems too late, incorporate verification earlier. For example, do a pre-filing “data validation pass” that compares what’s on your file with what you expect formatting-wise. Also, consider communicating with contractors as part of your onboarding refresh workflow.
Yes. Reconciliation is a widely adopted internal control because it helps catch missing payments, duplicates, coding errors, and data mismatches. It also improves audit readiness if questions arise.
In a mature workflow, reconciliation is not a one-time task. It repeats on a schedule (often monthly or quarterly) and uses documented steps. The goal is to keep anomalies small enough that resolving them doesn’t require massive rewrites at year-end.
Absolutely. Misclassification is a major source of compliance risk. Ensure your classification approach aligns with applicable standards and your operational reality. If you’re unsure, seek guidance from a qualified professional.
Even if you intend to file 1099-NEC, you must be confident that the person is legitimately an independent contractor for tax purposes. If classification is wrong, the issue can extend beyond 1099 reporting into employment tax exposure.
Yes. IRS deadlines exist for furnishing statements to contractors and for filing information returns. Plan backward from your internal submission date so you can correct data issues well before the deadline.
Many teams build a timeline that includes: internal cutoff dates for contractor data updates, a pre-filing review window, a correction window, and a final export/validation stage. The earlier your process begins, the fewer “last mile” surprises you will face.
Use official IRS instructions and publications for Form 1099-NEC and information return requirements. If your situation involves complex contractor payment types or corrections, consult a qualified tax professional.
As you refine your process, you can also align your internal documentation with how the IRS expects payers to think: the responsibilities, the definitions, and the correction pathways. This helps your internal team stay consistent with official guidance.
Using Square Payroll 1099 is very effective when your organization builds an end-to-end workflow: accurate contractor onboarding, consistent payment categorization, ongoing reconciliation, and disciplined pre-filing validation. By focusing on the inputs and your internal controls, you reduce the risk of incorrect totals and improve confidence in each filing cycle.
If you want, share (1) whether your contractors are paid for services only or also receive reimbursements, (2) how many contractors you typically have, and (3) whether you use multiple payment streams. I can help you design a more tailored reconciliation checklist and data-quality workflow.
Ultimately, your best protection is not just “running the report,” but building a process where the reported totals are backed by clear evidence and consistent logic. When someone asks “how did you get that number,” your workflow should allow you to answer confidently—quickly, objectively, and with supporting records.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Understanding 60817674500: Pricing, Supplier Signals, Quality Steps
This guide explains how to interpret the numeric keyword 60817674500 in procurement contexts, how pricing is commonly structured, and what supplier information should be verified before ordering. Objectively, it discusses what such identifiers often represent, why supplier traceability matters, and which due-diligence steps reduce delivery and compliance risk.
822478979788877878878897979797 Buyer’s Guide
This guide explains how to evaluate 822478979788877878878878897979797 procurement decisions with an objective lens. It outlines what the code typically signals in supply-chain workflows, how to verify supplier readiness, and which due-diligence steps reduce risk. You’ll also find a comparison framework, requirements, and practical FAQs for informed purchasing.
PrismaJOY Buying Guide: Requirements, Suppliers, and Pricing
PrismaJOY is a structured solution-focused product guide aimed at helping buyers evaluate sourcing, pricing factors, and implementation readiness. Objectively, PrismaJOY is discussed in terms of how “JOY” features map to selection criteria, compatibility, and supplier support in day-to-day procurement and deployment workflows, emphasizing due diligence and documented requirements.
PrismaJOY Guide: Pricing, Suppliers, and Buying Conditions
This guide explains how to evaluate PrismaJOY for responsible purchasing decisions, focusing on pricing structure, supplier credibility, and practical requirements. Objectively, PrismaJOY is presented as a brand name associated with consumer products, while “supplier” refers to the distribution chain that impacts delivery, warranty handling, and service responsiveness.
How Multishop Streamlines Modern Multi-Vendor Selling
This guide explains how Multishop supports multi-vendor commerce by connecting catalogs, orders, and supplier workflows in a single operational view. In objective background terms, multi-vendor platforms exist to reduce duplication of product and fulfillment management, while improving governance through standardized pricing rules, inventory updates, and supplier controls.
Understanding Gordo9498416253t and Related Product Options
This guide explains how to evaluate Gordo9498416253t-type listings and nearby supply options, focusing on how buyers can verify pricing, supplier credibility, and compatibility before purchase. Objectively, the keyword “Gordo9498416253t” functions as a listing identifier-like term, while “related product options” reflects the broader need to compare sellers, documentation, and performance claims using reliable sourcing and practical checks.
