This guide explains how to manage Square Payroll 1099 reporting for independent contractors. It outlines what 1099 forms represent in U.S. tax administration and why accurate contractor data matters for employers and payers. The article provides an objective overview of operational steps, common pitfalls, and practical requirements to support compliant recordkeeping and year-end workflows.
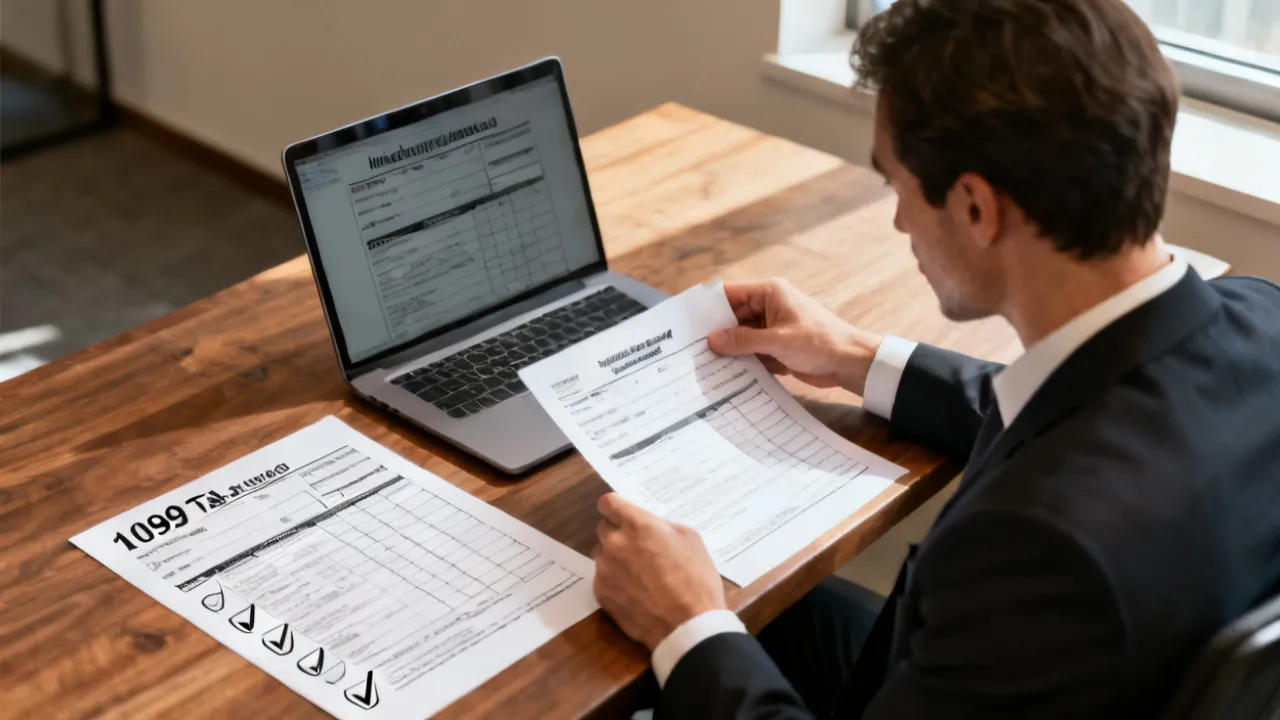
If you pay independent contractors through Square Payroll, your year-end workflow should focus on accurate contractor classification, correct payer/payee data, and timely tax-form preparation. Proper handling of Square Payroll 1099 information helps you reconcile payments to the underlying contractor records and support compliant year-end reporting.
In practical terms, your goal is not only to generate a form, but to ensure that the inputs—such as names, addresses, and tax identification details—are consistent with what the contractor provides and what your payment records reflect. When these elements align, the downstream process becomes far less error-prone during filing season.
Just as importantly, the workflow should be designed so you can explain the “why” behind each figure if you’re asked—by an internal reviewer, your accountant, or even the contractor. That means having a repeatable approach to mapping payments to categories, handling refunds/adjustments, and documenting corrections. In many organizations, the hardest part of 1099 readiness isn’t the technical form generation; it’s ensuring that the system of record and the tax reporting outputs are actually talking about the same underlying reality.
Square Payroll can streamline the operational side of tracking who was paid and how much across the year. Still, your compliance success depends on how you prepare, validate, and reconcile the data. Think of the platform as a data engine—your job is to ensure the engine is fed the right inputs, that the categories you use reflect how payments should be reported, and that the totals you generate match your accounting records once all timing differences and adjustments are accounted for.
The term “1099” is commonly used to refer to tax reporting forms used to document certain types of payments made to non-employees. Many businesses must issue one or more 1099-series forms depending on payment categories, recipient type, and applicable thresholds. While the exact requirements depend on the facts and on U.S. tax rules, the operational reality remains: businesses need a reliable method to track payments and recipient details throughout the year.
From an industry perspective, the very common breakdowns in 1099-related processes are rarely “math errors.” Instead, they tend to involve mismatched legal names, incorrect addresses, missing or inconsistent tax identification information, unclear contractor status, and weak internal controls around payment categorization.
Another reason 1099 becomes central operationally is that it touches multiple business functions at once. Accounts payable (or finance) needs to ensure vendor/contractor records and payment totals are correct. HR or operations may control onboarding and contractor classification policies. Customer success or project management may manage the “relationships” data—who did what for the business—while finance maps those relationships into reportable categories. When those functions don’t share a consistent process, mismatches become likely.
Additionally, 1099 workflows are time-sensitive. Even when you could technically file late, doing so can create practical problems: contractors may need time to plan their own tax filings; internal accounting close cycles may overlap with year-end; and the ability to resolve data problems can diminish as deadlines approach. A well-run Square Payroll 1099 program tends to start earlier than most teams expect—using interim checkpoints rather than a year-end scramble.
Finally, “1099 readiness” often becomes a data governance question. Many businesses discover that they have inconsistent naming conventions across systems (for example, abbreviations, punctuation differences, or “doing business as” names). The IRS matching expectations depend heavily on how information is presented. If your internal vendor master doesn’t align with the legal name and tax information the contractor provides, you can end up with forms that must be corrected or reissued—both costly and operationally disruptive.
When companies use Square Payroll to manage payments and contractor-related administration, they typically rely on the platform’s reporting and data outputs as part of year-end preparation. The phrase Square Payroll 1099 is top understood as a combined operational concept: “Square Payroll” represents the system capturing payment events and contractor metadata, while “1099” represents the year-end tax reporting deliverable tied to certain payment types and recipient categories.
An expert approach is to treat this as a data pipeline rather than a one-time export. In a compliant workflow, the steps include: (1) ensuring the payee is set up correctly, (2) ensuring payments are coded to the right reporting category, (3) reconciling totals at period-end, and (4) performing quality checks before final form generation and delivery.
When you treat the process like a pipeline, you design controls at multiple points. Early controls reduce downstream rework. For example, onboarding controls prevent missing tax IDs or incomplete addresses from entering your year-end dataset. Mid-year controls help keep payment coding consistent even if you change vendors, services, project scopes, or internal processes. Late-stage controls validate the final dataset to catch anomalies before the forms are furnished and filed.
It’s also useful to understand what “Square Payroll 1099” means in practice beyond the label. In many businesses, the platform may generate reports or exports that feed into your tax form workflow (either directly or through a tax filing service). If you rely on exports, you need to ensure your mapping between platform categories and the tax reporting categories is stable and well documented. When the mapping changes—perhaps because someone adjusted how a payment type is categorized in Square Payroll—your year-over-year totals may shift. That shift may be correct, but it still needs to be understood and reconciled.
Because of that, teams often establish a “1099 chart of accounts” mindset: defining which kinds of payments should flow into which reporting buckets. Whether you implement that in the platform through payment types, through internal accounting coding, or through spreadsheet mapping, the goal is the same: reproducibility. A future reviewer should be able to trace how a given payment was categorized and determine whether that categorization is intended for tax reporting.
Additionally, a disciplined workflow anticipates contractor updates. Contractors may change addresses, change legal names, or provide additional tax information during the year. The operational question becomes: which version of the contractor record should be used for 1099 reporting—initially captured data, updated data, or a version snapshot at specific points in time? The best approach is often to update the record in a controlled way and ensure that the tax reporting dataset uses the correct updated version, with documented evidence for changes.
Across payroll operations in SMB and mid-market environments, “good” 1099 readiness usually includes:
This approach reduces last-minute disruptions and improves your ability to respond to questions from contractors or internal stakeholders.
“Good” also tends to include a governance component: someone owns the process. Even if the mechanics are handled by Square Payroll reports, someone should own the checklist and the final reconciliation narrative. In practice, that owner sets interim deadlines, validates that fields are complete, and ensures correction procedures exist before a problem occurs.
In addition, good teams build a feedback loop with contractors. When contractors provide tax information (such as W-9 details), they sometimes make mistakes or use outdated addresses. If you have a procedure to quickly follow up and correct issues early, you avoid the compounding effect that occurs when issues go unnoticed until the tax-season peak. The more you can reduce the time between receiving information and updating your system, the fewer “last-minute corrections” you’ll face.
Finally, good teams run “sanity checks” beyond required fields. For example, they look for duplicate contractor entries with the same address or similar legal names, payment entries coded to the wrong category, unusually large payments that might indicate a mapping error, and “zero activity” contractors whose records might cause noise in reporting exports. These checks aren’t about perfection; they’re about catching patterns that suggest underlying issues.
Very 1099 issues start before tax forms are generated—during the moment a business decides how to pay a worker. In the U.S., contractor vs. employee status is governed by rules that evaluate behavioral control, financial control, and the relationship between the parties. Because misclassification can create tax and compliance consequences, a careful and well-documented determination matters.
For objective guidance, businesses typically consult official sources such as the IRS worker classification resources and, when appropriate, qualified tax professionals. For background, the IRS provides general information on distinguishing employees from independent contractors (see IRS guidance on worker classification for the very current framing).
While it’s tempting to treat classification as a checkbox—“I’ll put them in Square Payroll as a contractor, so they’ll get a 1099”—that approach can be risky. Classification is a facts-and-circumstances determination. In day-to-day operations, you can support the determination by documenting how work is managed. For example, you might document that the contractor controls how they perform the work, sets their own schedule (within agreed milestones), and uses their own tools or methods. Conversely, you might document the extent of your control to confirm whether it aligns with contractor rules or suggests employee-like behavior.
Even if your immediate goal is 1099 reporting compliance, classification and reporting are connected. Reporting outcomes often depend on whether the recipient is treated as a non-employee. That relationship between classification and reporting makes early alignment important: your onboarding forms, contract templates, and operational instructions should align with your classification policy.
Another operational point: classification is not always “final” at onboarding. Over time, the way work is performed may change. A person who starts as a contractor could become more employee-like if your business begins supervising tasks closely, requiring regular shift-like schedules, or dictating detailed process steps. Many businesses periodically review active contractor engagements to ensure their operational reality still matches their classification documentation.
If your workforce strategy uses a platform such as Square Payroll, you should ensure the platform’s setup reflects your classification policy and that your internal team understands the difference between “paid through payroll” and “classified as an employee.” Platforms can simplify payment processing, but they do not replace the tax-law determination of worker status.
A mature Square Payroll 1099 process emphasizes reconciliation. Even when a platform prepares reports, you should validate that:
Reconciliation is also your top defense against the very common “why is this amount different?” conversations. When you maintain clean records, you can explain variances using a clear audit trail.
Reconciliation is not one single activity; it’s typically a sequence of checks designed to ensure that each layer of the data pipeline agrees with the next. For example:
One common reconciliation challenge is time alignment. Payments may be initiated in one year but processed or settled in another. Some businesses record revenue or expenses based on invoice dates; others record based on payment settlement. For 1099 reporting, you generally report based on payment timing rules in the relevant instructions. Your reconciliation process should be designed to handle these timing differences and to explain them if you see differences between internal financial reporting and the 1099 reporting dataset.
Another common challenge is reversals. Refunds, chargebacks, and manual reversals can occur long after the original payment. If you don’t treat them consistently in your dataset, the annual totals can be inflated or deflated relative to what should be reported. A good workflow ensures there’s a consistent approach: reversals should reduce the original reportable amount according to the applicable instructions and your internal mapping rules.
Reconciliation also helps you manage operational changes. Suppose you change the way you categorize payments mid-year—maybe you introduced a new service type, or you adjusted how adjustments are coded. If reconciliation includes category and time analysis, you can detect where the mapping changed and ensure that your final totals reflect that change intentionally rather than accidentally.
Finally, reconciliation supports corrections. When you discover an error—such as a missing tax ID or a mis-coded payment—you need to determine the impact on totals. Reconciliation makes it easier to re-run only the impacted records and understand what changes in the final dataset. Without reconciliation, you can end up chasing errors blindly, reprocessing everything and risking further inconsistencies.
For 1099 reporting, recipient information must be accurate. Operationally, that means your data should reflect the payee’s legal name and current address, and your system should have tax identification information captured and maintained according to requirements.
From an expert lens, data quality is rarely a one-time cleanup. It is an ongoing discipline. If you correct a record after the year has ended, you may still need to manage downstream impacts such as re-issuance and version control. Therefore, establishing a reliable onboarding process and maintaining updates during the year can be more cost-effective than reactive corrections in filing season.
Recipient data quality is often where 1099 reporting processes fail operationally, because the “right” data depends on the contractor’s own documentation. For example, the name used in your payment record should generally match the legal name provided on the tax form documentation the contractor completed. Many errors occur when teams capture “display names” from customer accounts, nicknames, or variations of legal names instead of the legal name used for tax reporting.
Address quality can be similarly tricky. Contractors may move mid-year, may provide incomplete addresses (such as missing apartment numbers), or may change the address associated with their vendor payment profile. If you rely on outdated address data during the furnishing step, contractors may not receive their forms. If you rely on outdated address data for mailing, you can trigger delivery failures and potentially delay corrections.
Tax identification data quality also deserves attention. If your system stores tax IDs inconsistently—such as storing partial information, storing formatting differences, or failing to store tax IDs at all—the downstream tax form generation can either fail or produce forms requiring correction. In many organizations, the missing or incorrect tax ID issue is caught late because the earlier steps assume the platform will generate outputs correctly. But tax reporting typically requires that the data be complete and consistent according to the specific reporting form instructions.
To improve recipient data quality, many businesses implement an operational cadence:
Data quality also includes deduplication. Duplicate contractor records can cause fragmented totals and confusing outputs. For example, if you accidentally create two profiles for the same contractor—one with an old address and one with a new address—your annual totals might split across two records. That can lead to one record appearing below the threshold while the other record exceeds it. Depending on the instructions, the outcome could vary, but operationally it always creates additional work. Deduplication should be treated as a core control, not a “nice to have.”
Finally, version control matters. If you update a contractor’s name or address during the year, you should be able to explain what changed, when it changed, and which version was used for payment reporting and which version was used for tax reporting. Without this, if a contractor claims the wrong address was used, you may not be able to respond quickly.
Many organizations schedule a “closing checklist” for contractor payments. The checklist typically ensures that all payment events are recorded, adjustments are finalized, and reporting totals are locked before form preparation begins.
While deadlines can vary depending on filing and delivery mechanics, the general operational principle is consistent: you want sufficient time to validate data, resolve issues, and confirm delivery methods for recipients.
To keep your workflow grounded in official expectations, refer to IRS instructions relevant to the specific form type you are preparing and follow the latest guidance for filing and furnishing timing.
Year-end coordination is often the bridge between operational payment data and formal tax reporting deliverables. This bridge can fail if internal processes aren’t aligned. For example, if finance locks the accounting ledger at one point in time, but Square Payroll continues to record adjustments after the ledger lock, your reconciliation may show differences that aren’t actually errors—they’re timing and adjustment timing. A well-run year-end process anticipates these differences and clarifies which system is authoritative for 1099 reporting timing.
It’s also useful to coordinate with the operational team that handles contractor onboarding. If you only start chasing missing tax forms when year-end begins, you may not have enough time to get responses, validate data, and re-run outputs. Many organizations therefore set earlier internal deadlines such as “tax form data cutoff” or “data freeze” dates for the 1099 dataset.
Another coordination topic is contractor communication. If you furnish forms electronically, you need to ensure you meet furnishing standards and you have appropriate evidence. If you mail forms, you need to confirm addresses and printing timelines. If you furnish through a platform or tax service, you need to ensure the delivery method is configured correctly and that you can track deliveries or download copies.
Coordination also includes your correction workflow. Before finalizing, define how you will handle changes after forms are drafted. Some organizations find it helpful to establish a “draft-only correction window”—a period where corrections are made and a final dataset is produced, minimizing the chance of last-minute modifications after approval steps.
Finally, year-end coordination includes internal approvals. Even if the technical generation is automated, you typically want an approval step where someone validates totals, checks for missing fields, and ensures the final output matches reconciled numbers. This approval step helps prevent “silent failures” where a report exports incorrectly or where a contractor record is missing required fields but the system still produces an output that later fails validation.
Below are practical controls that professionals often use to reduce errors in 1099-related workflows (including those tied to Square Payroll 1099 reporting outputs):
In practice, quality controls become stronger when they are implemented as repeatable checks rather than ad hoc reviews. For example, you might use a checklist that is run on a fixed schedule and stored with the year-end records. If you repeat the same controls each year, you can detect recurring issues—such as a particular department repeatedly mis-coding payment categories, or a certain subset of contractors repeatedly lacking complete tax IDs.
Field-level validation should not stop at “is it filled in.” It should check patterns. For example, you might check for obvious formatting issues, missing apartment/suite numbers, or “placeholder” values such as “N/A” entered into fields that should contain actual data. Many systems accept values even if they are wrong or incomplete; the quality control should enforce the rules you need for compliant reporting outputs.
Deduplication deserves additional emphasis because it can affect totals, thresholds, and contractor communications. A contractor might receive multiple forms, each showing a partial amount, which can confuse them. Additionally, duplicates can create reconciliation differences and complicate corrections if you later determine that two profiles refer to the same person or entity.
Threshold review is where policy and instructions meet operations. Even if a platform can generate reports, your internal process should confirm that it’s generating the correct subset of recipients based on the applicable reporting category. Threshold interpretation can vary depending on the form type and the payment facts. If your scenario includes unique payment structures—such as mixed services, reimbursements, or unusual contract arrangements—threshold review should be done carefully and, where appropriate, with professional guidance.
Audit trail documentation is a best practice because it reduces confusion. If a contractor claims a correction was needed, or if internal reviewers need to understand why totals changed, you can show the exact record changes, the dates changes were made, and what triggered the changes. This matters especially in environments where multiple people have access to payment and contractor master data.
Finally, final totals review should incorporate both directionality and reasonableness. Not only should the totals match, but you should also ensure the totals move in the expected direction when adjustments are introduced. For example, refunds should generally reduce reported amounts. If you see an increase after a reversal, you likely have a mapping or coding inconsistency.
| Process area | What to verify | Practical requirement | Condition that triggers extra review |
|---|---|---|---|
| Contractor setup | Legal name, address, and contractor identifiers | Records must be complete and consistent across the year | Name/address changes during the year or duplicate payee entries |
| Payment coding | Payment type aligned with reporting category | Transaction mapping must be intentional and documented | Refunds, chargebacks, or manual adjustments that alter totals |
| Annual totals | Aggregated totals per recipient | Reconciliation against payment ledgers is performed | Totals mismatch after platform exports or internal ledger review |
| Tax form preparation | Correct form selection and recipient threshold treatment | Use official form instructions for the applicable reporting type | Unclear categorization or incomplete recipient documentation |
| Delivery to contractors | Method and timing for furnishing recipient statements | Follow IRS furnishing guidance and internal approval workflow | Contractor requests copies, address discrepancies, or delivery failures |
| Record retention | Stored evidence for audit and corrections | Maintain consistent retention practices | Corrections require tracking “what changed” and when |
The steps below are written as a neutral operational plan. Exact requirements depend on the form type and the payment circumstances, so align each step with the official instructions relevant to your situation.
Ensure your classification approach is documented and defensible. If a worker’s status is uncertain, pause and seek professional guidance. A robust internal policy is especially important when you rely on a platform workflow like Square Payroll 1099.
Operationally, this step includes more than labeling a worker as a contractor. It also includes confirming that your contracts and day-to-day management practices support that classification. For example, you may want your contractor agreements to reflect independent status and to define how deliverables are handled. Additionally, you may want internal guidance explaining what is considered acceptable supervision versus prohibited control that could shift worker status.
To reduce risk, you can implement a “pre-onboarding classification check” where relevant stakeholders—such as finance, operations, and legal/compliance—review the engagement type before payments begin. If classification is already established, this step still helps because it captures the rationale for why the worker is in the contractor population used for 1099 reporting.
If you ever change your classification policy or refine your interpretation during the year, document that change. A change in policy may affect whether certain payments should be included in 1099 reporting. You should ensure the platform setup and the payment mapping logic reflect the current policy for the relevant period.
Review each contractor’s profile used for reporting: legal name, address, and tax identification details. Correct obvious issues early in the year or as soon as updates are received.
This step is often where you separate “data entry” problems from “tax documentation” problems. Data entry problems include misspellings, formatting inconsistencies, and incomplete addresses. Tax documentation problems include missing tax IDs or tax IDs that don’t match the contractor’s legal name as provided. Both require correction, but they may require different follow-up actions.
To make this step more effective, many teams create a “master data audit list” for each contractor category. For example, you might track contractors by engagement type, location, or payment category. Then you run a completeness check and capture the missing fields and their severity. Contractors with incomplete data are prioritized because they will be the hardest to fix near year-end.
When correcting data, ensure your changes are applied consistently across the platform and any connected systems (such as accounting software, vendor management tools, or tax filing services). If you update only one system, the tax reporting output may still use the old values, leading to contradictions and possible re-issuance needs.
Also, pay attention to “name control” issues. The legal name used should generally follow the name structure the contractor provided in their tax documentation. Variations like “John A Smith” vs “John Smith” can matter depending on matching expectations. While minor differences might not always cause issues, building a habit of consistent legal-name capture reduces the likelihood of mismatches.
As payments are processed, confirm that the payment events you intend to report are coded consistently. If you use multiple payment types (for example, standard services vs. adjustments), ensure your mapping logic remains stable.
Payment event categorization is where operational intent needs to be translated into system setup. For example, you might treat “service payments” differently than “expense reimbursements” or “platform adjustments.” If a platform records different kinds of events with different metadata, you need a mapping strategy: which event types contribute to which reporting totals?
One way to implement this is to create a classification guide for your finance team. The guide might include examples: “If this payment is for deliverables under the consulting agreement, code it as service; if it’s for reimbursement of approved expenses, code it as reimbursement; if it’s a reversal/refund, code it as reversal/adjustment.” The guide should be reviewed when new payment types or new use cases arise.
When you validate categorization throughout the year, you reduce the chance that a late-year workflow change will affect year-end totals unexpectedly. For instance, if someone updated a category mapping without telling finance, your final totals could be wrong. Ongoing validation helps detect those changes early.
Finally, validation should include unusual transactions. If a payment is unusually large or is associated with an unusual event type, you should investigate why it was coded differently. Anomalies can indicate mis-keyed transaction details or miscategorized payment types.
Don’t wait for year-end alone. Monthly or quarterly spot checks help detect drifting categories, duplicate recipients, or unusual payment types before totals get large.
Interim reconciliations are a practical way to keep “1099 readiness” from becoming a year-end crisis. In many environments, the volume of contractors and transactions increases toward the end of the year (or sometimes decreases due to scheduling). Interim checks help you account for those changes and understand whether totals are trending correctly.
A quarterly reconciliation might include:
Interim reconciliation also improves your ability to handle contractor updates. If you discover in Q3 that a set of contractors is missing tax IDs, you have time in Q4 to follow up, correct records, and rerun exports. Waiting until early Q1 might still be possible, but it increases the risk of delays.
In organizations with multiple people entering contractor data, interim reconciliations provide feedback. If a particular user’s entries repeatedly create duplicate records or missing fields, you can provide targeted training or adjust the workflow and prevent recurrence.
At year-end, export the platform’s relevant totals and reconcile them to your internal accounting records. Any variance should be explained by a known adjustment (refunds, reversals, or corrections).
This step should produce a clear reconciliation narrative. Rather than just stating “totals don’t match,” you want to identify where they differ. For example, differences might come from:
To keep reconciliation manageable, you can structure the comparison by reporting category and by major contractor groups. If the totals differ by thousands of dollars, you can quickly narrow down which category or which time period likely caused the difference. Then you drill down transaction-level to confirm the specific cause.
Another helpful tactic is to freeze the year-end dataset. Once you export year-end totals and begin draft preparation, you should limit changes to the underlying records unless they are required and tracked. This reduces the risk of totals shifting during draft generation.
When you do need to change records (for example, to add missing tax IDs), treat it as a controlled change. Record the reason, note the date the change was made, and rerun the necessary exports so the dataset remains consistent with the updated data.
Determine which recipients are subject to reporting for the relevant form category. Apply the logic consistently and document the rationale. If your scenario is complex, consult a tax professional to avoid assumptions.
Threshold review is conceptually simple but operationally nuanced. The operational nuance comes from the fact that different payment categories have different inclusion rules and sometimes different handling for partial-year activity, reimbursements, or special payment structures.
To conduct threshold review effectively, many teams do the following:
Even if the platform suggests which contractors are reportable, threshold review is still valuable. It can catch data issues such as duplicates or mis-coded payment categories that would affect whether the contractor appears above the threshold.
For teams with many contractors, an additional control is to produce a “reportability list” that includes reason codes such as “exceeds threshold based on service payments,” “included due to adjustments,” “excluded due to insufficient reportable category total,” or “excluded due to missing required tax ID” (where applicable operationally). A reason-coded list helps auditors and internal reviewers understand your inclusion/exclusion decisions.
Before finalizing, verify that each recipient’s details match the contractor record used for furnishing. Confirm that totals per recipient match your reconciled totals.
Quality assurance checks at this stage focus on “form output correctness.” That means validating that the draft forms reflect:
One common operational issue at draft stage is misalignment between “which record is used for tax reporting” and “which record is used for payment reconciliation.” For instance, if reconciliation identifies a contractor using one internal profile ID, but form generation uses a different identifier or another profile version, totals and identity fields may not match.
QA should catch this by comparing outputs back to your dataset and by performing targeted spot checks on a sample of recipients—especially those with large totals or those flagged for missing/incomplete data.
In addition, QA should include “exception review.” Exceptions might include missing fields, contractor profiles flagged as duplicates, contractors with unusual payment patterns, or contractors with significant refund activity. These exceptions should not automatically be assumed correct or incorrect; they should be reviewed to confirm whether the output is correct.
Follow the IRS furnishing guidance and your internal approval workflow. Maintain evidence of delivery method and retention of final copies.
Furnishing is a deliverable step that turns reporting data into contractor communication. Operationally, furnishing requires:
Furnishing also creates an opportunity for contractor feedback. Contractors may respond with correction requests if they notice mismatched names, addresses, or amounts. A well-run process captures these requests, verifies them against your records, and implements corrections via a controlled correction workflow.
To reduce furnishing-related errors, some teams pre-send communication to contractors with instructions on how to review their reportable information and how to request corrections. While you typically can’t replace official reporting requirements with informal communications, clear communication can reduce confusion and speed up resolution when issues are identified.
Evidence retention is important for operational assurance. Keep records such as mailing proofs, electronic furnishing confirmations, and internal approval logs. If a contractor claims they never received their form, you should be able to check your evidence quickly.
Filing steps and deadlines depend on the specific form and filing method. Use the latest IRS instructions and confirm how your selected mechanism processes transmissions or submissions.
Filing is not just “send the forms.” Operationally, filing includes verifying that:
Because the IRS instructions may change by tax year, it’s important to use the most current documentation for the tax year you are reporting. Teams often build a habit of storing the latest IRS instructions and referencing them in their internal checklist so that the process is aligned with the current year requirements.
It’s also a good practice to perform a final data integrity check before submission. Even if you ran QA earlier, final integrity checks can catch issues that arise from export-to-file transformations, such as formatting conversions, truncation, or invalid characters.
If you use a tax filing service, coordinate with that service to confirm how they expect the dataset to be prepared, and verify that any corrections requested are reflected in the final submission version.
Even with strong controls, issues can surface. Establish an internal procedure for corrections, including tracking the “original vs. corrected” outputs, documenting changes, and communicating with contractors when necessary.
A correction workflow should be designed before you need it. The biggest operational mistake is to wait until there’s a problem and then invent the process under time pressure. Instead, define:
Correction procedures are also about maintaining “auditability.” If you later need to explain why a contractor received a corrected form, you should be able to point to the data change, the reason it was changed, and the date and evidence supporting the correction.
Additionally, corrections can create secondary effects. Correcting a contractor’s name or address might also require rechecking that the correct tax ID is associated with the correct name. Similarly, correcting a payment coding error might change a contractor’s amount reported and could affect whether they are reportable under thresholds. Your correction workflow should account for these cascading impacts.
Because 1099 workflows involve multiple data layers, a correction should generally include a re-run of the impacted portion of the dataset rather than a manual patch. That helps prevent new inconsistencies.
Understanding pitfalls helps you design better controls. Here are issues that often arise:
These pitfalls are common because they are operational rather than purely mathematical. A duplicate record might not change the total amount you paid overall, but it changes how amounts are distributed across recipient forms. That distribution affects thresholds and creates confusion for contractors. The contractor may receive two partial forms and may not understand why totals appear split.
Out-of-date address data can be especially problematic for furnishing. If you mail to an old address, the contractor may not receive the form. Even if you later correct the address, you may still need to take additional steps to furnish the corrected information. If you furnish electronically, address issues might manifest differently, but they can still affect communication and documentation.
Misinterpreted payment categories often occur when your operational team uses payment types for internal convenience rather than for reporting logic. For example, a payment category might be “adjustment” or “other,” but your tax reporting logic might require mapping “adjustment payments” into the reporting category of the original service payment. If your mapping logic is unclear, refunds and adjustments might be included incorrectly.
Late onboarding is a practical reality for many businesses. New contractors may be added close to year-end due to project needs. If onboarding is rushed, tax ID collection and data validation might be incomplete. Late onboarding therefore increases the probability of missing fields at the moment you need them.
Unclear handling of refunds is another common issue. Refunds can be processed long after the initial payment, sometimes even after the year ended. If your system includes refunds in the year they were processed rather than the year they relate to for tax reporting purposes, you could see unexpected totals. A good reconciliation process helps identify and resolve these differences.
Another pitfall that often emerges is a weak change-control environment. If multiple people can update contractor profiles and payment categories without a documented workflow, errors can slip in between interim checks. When that happens, you can lose track of what changed and why totals shifted. Implementing approval steps and audit trail documentation reduces that risk.
Finally, some teams overlook deduplication and identity alignment across systems. Square Payroll might store the contractor profile in one way, while your accounting ledger or tax filing service might store or export in another way. Identity alignment—ensuring the same legal name and tax ID are used consistently—is essential to ensure the outputs are coherent and defensible.
For accuracy and alignment with official standards, businesses typically rely on the IRS for tax form instructions and worker classification resources. As a reference point, the IRS explains worker classification concepts and provides guidance on employee vs. independent contractor considerations. Additionally, IRS instructions for the specific 1099-series form clarify threshold concepts, reporting categories, and filing/furnishing procedures.
Reference sources: IRS guidance on worker classification and IRS instructions for applicable 1099-series forms (consult the very current IRS publications and instructions for your tax year and form type).
Operationally, it is helpful to store these references in your internal documentation folder and to tie them to your workflow checklist. For example, when you run threshold reviews, you should reference the specific instructions for the form type you are using and capture them as part of your “decision log.” This helps ensure consistency from year to year, especially when team members change.
Additionally, you can consult official IRS resources when you need to interpret specific edge cases, such as how to handle particular transaction types, how to manage corrections, and what evidence to retain for audit purposes. Even if your platform provides reports, you still need to ensure that the platform’s categorization aligns with the IRS instructions for your specific reporting type.
For worker classification, consult the IRS worker classification resources and, where appropriate, professional guidance. Your classification approach should be supported by documentation and reflect the actual facts of how work is performed.
It generally refers to the operational process of using Square Payroll to manage contractor payment data and then preparing 1099-series reporting for qualifying independent contractors, based on the relevant IRS form instructions and your business’s payment scenarios.
Depending on your setup, this can include exporting reports from Square Payroll, reconciling payment totals, validating recipient data, generating draft forms, furnishing statements to contractors, and filing with the IRS using the required method for your form type.
Not necessarily. Whether a contractor must receive a 1099 depends on the type of payments, recipient circumstances, and the applicable thresholds and instructions for the specific 1099 form category. Review the official IRS instructions for your form type.
Operationally, this means your workflow should include a recipient threshold review step, rather than assuming that every independent contractor included in your payroll system automatically results in a reportable form.
Common causes include refunds or reversals, adjustments coded to different categories, duplicate contractor records, or reconciliation gaps between your accounting ledger and platform-exported totals. Performing a structured reconciliation usually identifies the exact reason.
In other cases, the mismatch comes from timing differences—payments might be initiated, reversed, or finalized across different dates. A good year-end process accounts for those differences and maintains a reconciliation narrative so totals differences can be explained.
Correct the contractor’s master record and document when and why the change occurred. Then ensure that the corrected details are used for draft validation and the final furnished/ filed forms, following your internal approval and version-control process.
If the error is discovered after furnishing or filing, follow your correction and re-issuance procedure, including tracking “original vs. corrected” outputs and maintaining evidence of changes.
No. Classification (employee vs. independent contractor) is a broader determination under tax and compliance rules, while tax form reporting relates to specific payment types and reporting categories. Both matter, but they address different compliance questions.
A single business might correctly classify a worker as an independent contractor but still not report that worker on a specific 1099 form if the particular payment types or thresholds do not trigger reporting under the applicable form instructions.
From an operational standpoint, starting early helps you resolve missing data, reconcile payment totals, and address contractor record updates. Many businesses perform interim checks during the year rather than waiting for year-end.
A common operational model is to implement quarterly reconciliation checks, to run a pre-filing data audit in the final quarter, and to set internal deadlines for tax ID and address updates so you can complete draft generation and QA without rushing.
Platform outputs are valuable, but an expert approach typically includes reconciliation and quality assurance. Treat the output as a starting point and validate the figures and recipient details against your internal records and the applicable official instructions.
Platforms can reduce manual work, but compliance still depends on whether your inputs are correct and whether the reporting outputs reflect the correct reporting categories and recipient identities.
Use the latest IRS instructions for the specific 1099-series form(s) relevant to your situation, and consult IRS worker classification resources if you need guidance on contractor status.
If your situation includes complex payment structures or classification uncertainty, consider consulting qualified tax professionals to ensure your approach is consistent with current guidance.
Managing Square Payroll 1099 reporting effectively is less about pressing a final button and more about running a disciplined workflow: correct classification logic, strong contractor onboarding, consistent payment categorization, timely updates to recipient data, and systematic reconciliation at year-end. When these elements align, you reduce avoidable errors and build an auditable record that stands up to questions from internal stakeholders and contractors alike.
The best outcomes come from treating 1099 reporting as a continuous operational process rather than a seasonal scramble. When you implement interim reconciliation checks, enforce recipient data quality, maintain clear mapping logic between payment events and reporting categories, and document your corrections, you create stability for both your finance team and your contractors.
Square Payroll can support that stability by capturing payment data and contractor metadata in a centralized workflow. But the compliance quality is still determined by your operational discipline—how accurately your system reflects the contractor’s legal documentation, how consistently you categorize payments, how carefully you reconcile totals, and how thoroughly you validate your final outputs before furnishing and filing.
Ultimately, the goal is confidence: confidence that totals reconcile, that recipient data is correct, that the forms you deliver match the underlying payment reality, and that you have a clear audit trail to explain the numbers. When you reach that level of control, 1099 reporting becomes a predictable workflow that improves each year rather than a recurring stress event.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
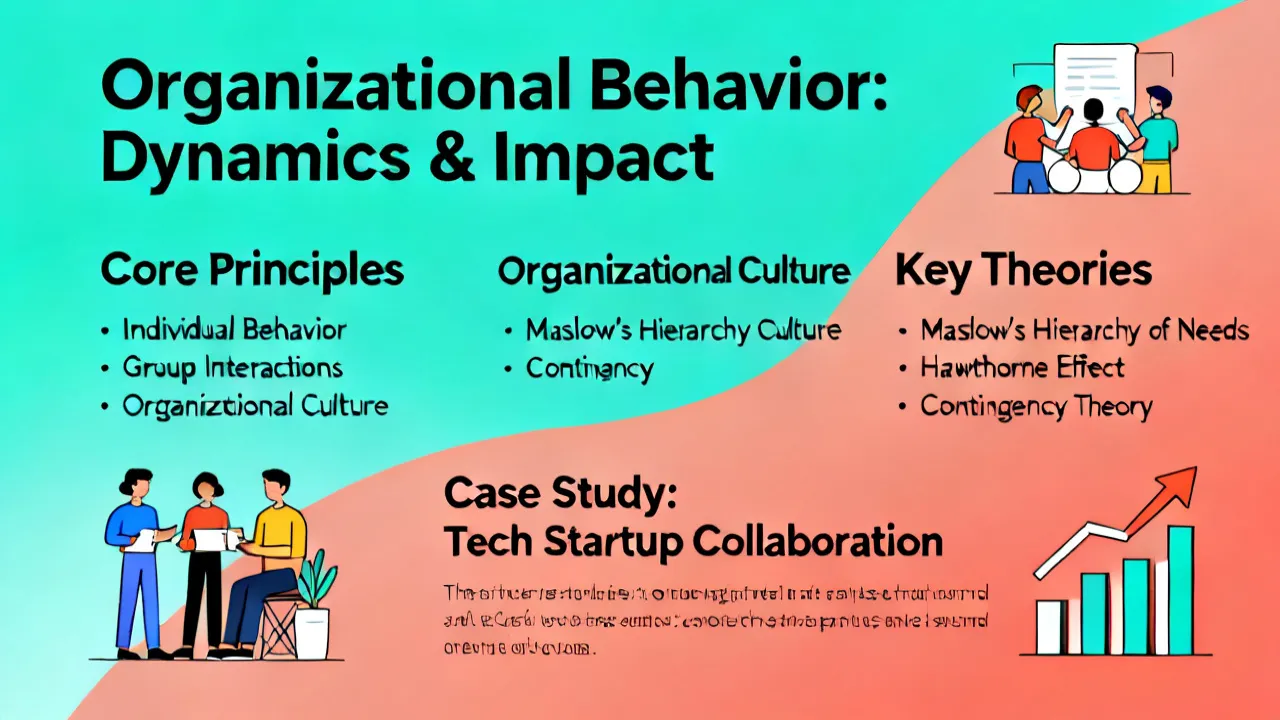
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
