This guide explains how Square Payroll 1099 reporting works, how to classify contractors, and how to prepare reliable records for 1099 forms. It provides objective background on 1099 requirements, contractor vs. employee distinctions, and recordkeeping top practices. The focus is practical: help you reduce submission errors by following a structured verification workflow.
If you use Square Payroll 1099 to support contractor payments reporting, the key to successful compliance is not just generating the form—it’s confirming who should be reported, what amounts count, and when information must be finalized. In this guide, you’ll find an objective, step-by-step approach for preparing for 1099-related workflows, validating data quality, and aligning your records with IRS expectations.
Because 1099 reporting is detail-driven, an “it looks right” assumption can lead to avoidable fixes later. Instead, treat the workflow like an audit trail: consistent contractor identity details, correct totals, clear documentation, and timely review. That mindset is particularly useful when your payment mix changes throughout the year or when multiple locations or departments submit payment data.
In the day-to-day language of many business owners, Square Payroll 1099 refers to the use of Square’s payroll and contractor-payment tooling (and related exports) to help produce year-end tax form outputs and reporting artifacts. Depending on your setup, this may involve generating or preparing information used for 1099 forms, such as 1099-NEC-style contractor reporting, along with supporting data exports.
However, the exact capabilities can differ by plan, configuration, and the types of workers you pay. Therefore, it’s top to frame Square Payroll 1099 as a workflow support system—a way to organize inputs, compute totals from payment records, and produce form-ready outputs—rather than a guarantee of compliance by itself.
In practice, many businesses use some combination of:
When people say “Square Payroll 1099,” they often mean, “I want a reliable way to gather contractor data and totals so I can file.” That is the right goal—but you’ll still want to ensure the inputs match the underlying tax reporting reality.
1099 reporting hinges on correctness of identity and amounts. The IRS generally expects you to report the proper payer/payee information and to categorize payments appropriately. Even a strong payroll system can’t fix conceptual issues like misclassification or missing legal-name details.
From an industry-expert perspective, the very common failure points are:
It helps to recognize that “contractor data” is more than a label in a software record. For tax reporting, you need the details that allow the IRS and the contractor to match records correctly. If the contractor’s name and TIN don’t align with tax records, your submission might lead to mismatches, follow-up questions, or correction processes.
There is also a practical business cost to errors: even if you can correct the forms later, rework diverts time from ongoing bookkeeping, month-end close, and planning. Therefore, the best approach is to invest early in data integrity and review discipline.
Very businesses that leverage platforms like Square Payroll 1099 try to bring structure to three areas:
Even if your platform supports exports or form-ready outputs, you still need internal controls—especially if multiple staff members handle onboarding, contractor setup, invoicing, or reconciliations.
A helpful way to think about the workflow is to separate what the software does from what your business must decide:
When those responsibilities are clear, it becomes easier to design a workflow that reduces mistakes and keeps people aligned on process.
The request you provided includes placeholders for “price information” and “supplier details,” but no concrete values were supplied in the prompt. Because this article must remain objective and avoid unverified claims, it does not invent pricing or supplier specifics. Instead, the practical approach for procurement and selection is to confirm:
For accuracy, businesses should consult Square’s official help documentation and your own plan agreement, rather than relying on secondhand summaries.
Procurement decisions also often extend beyond features. Teams typically evaluate:
These considerations help ensure the technology is not only capable on paper, but workable in your day-to-day operational reality.
The 1099 series of forms generally supports tax reporting for income that is not paid through standard payroll wage reporting. For many businesses, the relevant focus is reporting certain payments to nonemployees (often described as independent contractors). The IRS provides guidance on who must file, what must be reported, and what documentation is required.
Because requirements can vary depending on payment types and circumstances, your top practice is to align your worker classification policy and payment tracking with IRS instructions. For foundational reference, see:
These sources help you avoid “technology-led compliance,” where the platform’s output is treated as the compliance strategy instead of the beginning of it.
To keep this practical, you can frame the compliance objective like this: your 1099 reporting should allow the IRS and the contractor to reconcile income information with minimal mismatches. That generally requires accurate payee identity details, correct mapping of what payment types belong in the report, and proper year assignment.
When a system generates a Square Payroll 1099-related output, the critical question becomes: “Is the underlying data clean and consistent?” Consider validating these fields (as applicable in your workflow):
In many organizations, it’s the “edge” items—late invoices, reversed payments, reimbursements, or partial payments—that produce the very confusion. Establish a rule for how you handle those items during the year-end reconciliation.
Below are specific edge scenarios worth considering, because they often fail quietly until the year-end process forces the issue:
Data quality isn’t only about completing fields; it’s also about having consistent definitions across your team. For example, “contractor fee” should mean the same thing to every person who tags transactions.
Below is a structured approach designed to reduce errors and rework. It assumes you’re using Square tools (or exports derived from Square records) to help assemble 1099-related information.
Before you rely on any Square Payroll 1099 output, verify that the workers included are correctly classified as nonemployees under your policy and the applicable guidance. If your organization is uncertain, consider obtaining professional tax or legal advice.
This step matters because software totals are not a substitute for classification. A well-maintained database can still produce “perfectly wrong” reporting if the worker type is incorrect.
Operationally, classification policy usually includes more than a label. You may want to define internal documentation practices such as:
Even if classification is handled by an external adviser, your team must know which workers should appear in the 1099 workflow so you don’t omit reportable payees or include ineligible ones.
For contractor reporting workflows, businesses typically rely on collected forms such as W-9 information for payees. Confirm that each contractor record contains the necessary tax identification details and accurate name/address information required for your reporting process.
In practice, documentation collection is more than “we have a file somewhere.” You want to define where documentation lives, how it’s linked to the payee, and who verifies it.
Consider implementing a simple operational framework:
This avoids year-end surprises when a contractor record appears in the system but lacks tax identification data or contains outdated details.
If you do not collect W-9 information early, the year-end process becomes a rush. That rush often increases errors—particularly with legal names, spelling variations, and address formatting.
In Square-based systems, transaction and payout categories should be set up so that only the payments intended for 1099 reporting are included in the totals. Where your workflow includes multiple payment types, create clear internal definitions (e.g., “counts toward 1099 totals” versus “does not count”).
This is where many businesses discover that their transaction tagging practices were designed for bookkeeping reconciliation rather than tax reporting categorization. If you repurpose those categories without review, you may inadvertently include or exclude amounts incorrectly.
To handle this effectively, you can map your payment categories into three conceptual buckets:
Once those buckets exist, ensure your system categorization follows them. Then, at year-end, your totals come from transaction types aligned with the reportable definition.
Another practical factor: if you use multiple invoicing methods (for example, invoices for some contractors and direct payments for others), ensure all these flows tag transactions consistently.
Use an internal reconciliation method that compares:
If you find discrepancies, trace them to specific transactions or category settings rather than treating the difference as “close enough.” Small mismatches can compound when multiple contractors are involved.
Reconciliation can be as simple or as sophisticated as your organization’s operations allow. The important part is traceability: you should be able to point to exactly what makes the numbers differ.
A useful reconciliation checklist might include:
For many businesses, reconciliation becomes easiest when you treat the year-end process as a controlled data extraction: freeze the inputs, extract totals, and then validate the extraction before any final filing steps.
Review each contractor’s identity fields and totals. This is especially important if you onboarded contractors at different times during the year or if contractor details changed midyear.
Look for patterns like:
A “consistency review” also benefits from exception rules rather than only manual scanning. For example:
This kind of targeted review saves time and reduces the probability that a quiet error remains hidden in a long list.
Even if you trust your internal data entry process, inconsistencies can arise from contractors changing names, address formatting differences, or team members using slightly different category labels.
Keep records showing how inputs were collected and how totals were derived. This includes a snapshot of the data used for the forms and any notes about changes made during review.
From a professional operations standpoint, an audit trail shortens the time needed to correct issues if a contractor questions the reported amounts.
Audit trail practices typically include:
If you ever need to correct forms, an audit trail helps you move quickly and defend decisions with less guesswork.
From an organizational perspective, audit trails also improve consistency year over year. Instead of recreating everything from scratch, you can improve the workflow based on what went wrong in the past.
If you discover errors after submission or after distribution to contractors, follow the corrective steps required by your filing and distribution obligations. The exact action depends on what was wrong and when it’s discovered.
Because correcting tax forms can involve additional paperwork and potential reporting impacts, build a straightforward internal “corrections playbook” so you act consistently and quickly.
A corrections playbook typically addresses:
You don’t need to draft every detail upfront, but you should have a clear process for triage. A good process prevents panic and reduces the likelihood of compounding errors (for example, correcting an amount without correcting the underlying category mapping issue).
The following table compares common workflow elements involved in a Square Payroll 1099 process and the conditions under which each element is considered “ready.” (No external links are included, as requested.)
| Workflow Element | What “Ready” Typically Means | Common Requirement / Condition |
|---|---|---|
| Contractor record setup | Worker is clearly designated as a nonemployee in your process | Classification is supported by your internal policy and relevant guidance |
| Tax identification data | Taxpayer information is present and consistent | Collected from the contractor via the appropriate documentation workflow |
| Legal name and address | Payee identity fields match the documentation | Updates are captured if a contractor changes details before submission |
| Payment categorization | Only intended payments roll into the 1099-related totals | Transaction types are mapped to your reporting definitions |
| Year-end reconciliation | System totals reconcile to internal records | Discrepancies are investigated and resolved before final output |
| Final review and approval | Reviewed totals and payee data are approved by a responsible party | Two-step review recommended for organizations handling multiple contractors |
Tables are helpful, but many teams need a stronger mechanism: explicit “gate criteria” that define when you can move from one workflow step to the next. This prevents the process from drifting due to time pressure, staff turnover, or late-arriving contractor updates.
For example, you can define gates like:
These gates don’t have to be complicated; they just need to be followed. When they are, the workflow becomes predictable and less stressful.
Predictability matters because year-end tasks often happen under deadline pressure. A gate-based system reduces the temptation to bypass checks, especially when the list of contractors is long or when internal staff is juggling multiple responsibilities.
Industry teams that handle Square Payroll 1099 workflows effectively usually don’t rely on a single person’s memory. Instead, they implement controls that make errors less likely:
This kind of operational rigor is particularly valuable for businesses with multiple service lines, seasonal workers, or contractors who invoice irregularly.
To expand on each control:
These controls also help onboarding and training. New staff can follow the controls rather than relying on tribal knowledge.
It generally refers to using Square’s payroll/contractor-related functionality and associated reporting outputs to support year-end 1099 processes. The key point is that your tax obligations depend on the underlying facts—worker classification, payment types, and accurate payee data—not solely on what the software produces.
In other words, Square helps you organize and calculate certain pieces of the workflow, but the decision-making and verification steps remain your responsibility.
Yes. A professional workflow includes reconciliation and data validation. Software can compute totals correctly based on how transactions are categorized, but it can’t verify whether your contractor classification or payment mapping rules match your actual compliance requirements.
Reviewing totals is not busywork; it is part of ensuring that the workflow’s assumptions match your real-world operations. The most common reason for “system totals” being off is not a software bug—it’s miscategorized transactions or inconsistent definitions.
Review legal name spelling, address, and tax identification information. Also confirm that updates are reflected in your records before you finalize outputs. Inconsistencies are a frequent source of downstream corrections.
It’s also helpful to check consistency across time. For instance, if a contractor changed their name or address, ensure the reporting period’s finalized data reflects the correct information for the year being reported.
Not necessarily. Whether a payment is reportable can depend on the type of payment and your circumstances. Your internal definitions for “reportable vs. non-reportable” should align with IRS instructions applicable to your situation.
Many businesses discover this during reconciliation when they notice that certain categories—like certain reimbursements or fees—were tagged as “contractor payments” for bookkeeping but may not be treated the same for 1099 reporting.
Create a policy for how you treat posting dates versus service dates, consistent with your bookkeeping approach and the relevant instructions. Reconciliation is essential to prevent mis-year reporting.
Because posting timing can vary by billing and payout cycles, it’s important to define your approach early and apply it consistently. If your method differs across departments, you may unintentionally misstate the year allocation.
Step one: prepare the output and verify totals against payment records. Step two: review payee identity fields and exceptions (missing or unusual data). Approving the final output after both steps can reduce costly corrections.
A “two-step review” works best when each reviewer has a specific focus. For example, one person focuses on totals and reconciliation; the other focuses on identity details and completeness checks.
Platform outputs are helpful for organization and calculations, but compliance is ultimately a business responsibility based on accurate facts and adherence to applicable IRS rules. Consider professional guidance if your worker classification or reporting situation is complex.
It’s reasonable to use software outputs as a starting point. It’s not reasonable to skip validation steps, because compliance requires correct facts—not only correct math.
To keep your process grounded in authoritative guidance, rely on official IRS materials for the specific tax form instructions and classification rules that apply to your scenario. The IRS publishes:
These references are the appropriate baseline when confirming what “counts” toward reporting, what documentation is required, and what corrective actions are needed when errors occur.
Note: This article intentionally avoids quoting unverified or exaggerated statistics. For any performance or filing-rate metrics you may encounter elsewhere, prioritize official research and reputable industry reporting (e.g., IRS publications, government tax administration materials, or established accounting industry reports) and validate their methodology before citing.
Even for software capabilities, official documentation matters. Tools evolve, plan tiers change, and features may be added or refined. The most accurate source for “what Square can do for your specific plan” is Square’s own support documentation and release notes.
Using Square Payroll 1099 effectively comes down to governance: correct classification, complete payee data, accurate payment categorization, and disciplined reconciliation. When those elements are in place, the platform can serve its real purpose—helping you compile year-end information with less friction.
If you want a simple operational rule, use this: don’t trust the output until the inputs and totals reconcile. That principle keeps your process defensible, repeatable, and easier to correct if something changes late in the year.
Many businesses discover that the hardest part of 1099 reporting isn’t the final form generation. It’s organizing how data flows from day-to-day operations into the year-end reporting dataset. When you use Square for payroll or contractor-related payments, it becomes easier to extract data—but it doesn’t automatically create the operational discipline needed to ensure the dataset is reportable, complete, and consistent.
To make the workflow resilient, you can design it around the lifecycle of a contractor relationship: onboarding, payment activity, and end-of-year reporting. Each lifecycle stage has specific failure points and therefore specific controls that are worth adding.
Onboarding is where many problems originate. If a contractor is onboarded late, or if the required identity documentation is not collected promptly, year-end becomes a rush. If a contractor’s name or address is entered incorrectly at onboarding, corrections later can trigger downstream mismatches or require rework.
Consider implementing an onboarding checklist with minimum fields and minimum verification. The objective is not to create bureaucracy; it’s to create a reliable base for year-end reporting.
If multiple departments onboard contractors, the onboarding process should be consistent across the company. A frequent real-world issue is that one team uses different naming conventions or different categorization rules, producing inconsistent outputs when you aggregate data.
During the year, payments may arrive through different processes: manual invoices, scheduled work orders, adjustments, reimbursements, or corrections. If category discipline is weak during the year, year-end reconciliation will be difficult because the dataset will not align with your reporting definitions.
One useful approach is to implement an internal “transaction tagging standard.” The standard defines which transaction types count toward 1099 totals and which do not.
For example, your standard might specify:
The key is consistency. If people tag transactions differently, you lose the ability to rely on computed totals. And if you cannot rely on computed totals, you will end up manually recalculating or creating messy spreadsheets that are hard to audit.
A robust year-end workflow usually includes a “freeze” concept. While your systems may continue to process transactions after year-end, you need a clear snapshot of what data is considered part of the reporting year.
A freeze strategy can be defined in operational terms:
This is particularly helpful when multiple people are involved. If someone makes late edits to contractor categories or identity fields, you want to know whether those edits are included in the frozen dataset or not.
After extraction, validation should focus on both totals and identity fields. Totals validation ensures your computed numbers reflect correct reportable amounts. Identity validation ensures names and tax IDs are consistent and complete.
When you have many contractors, manual checking becomes impractical. Automation and exception-based review become essential. Even if Square provides exports or structured outputs, you still need review methods that scale.
Here are scalable review techniques that can be applied regardless of your reporting system:
If you don’t scale your review, you may spend too much time on low-risk records and not enough time catching the issues that matter.
Contractor information can change midyear. Contractors may update their addresses, legal names, or business names. Sometimes, they may also correct tax identification details.
A practical policy for midyear changes includes:
The purpose is to prevent the “moving target” problem. If the contractor’s identity data changes repeatedly, you need a consistent rule for what identity data is finalized for the report.
Identity errors are often subtle. A contractor may provide “legal name” in one format, while your system stores it in another. Even if the tax identification is correct, name formatting differences can lead to mismatches.
To reduce this risk, define internal formatting rules. For example:
When formatting is inconsistent, you may not immediately notice the issue until you see downstream validation errors or contractor questions. Catching these issues earlier is often much cheaper than fixing them after the fact.
It’s common for businesses to use multiple systems: Square for payments, an accounting system for bookkeeping, and maybe a spreadsheet for year-end reporting. Each system may treat categories differently.
To avoid reconciliation confusion, you can implement “category mapping documentation.” This documentation answers questions like:
When mapping logic is documented, it becomes easier to troubleshoot when totals don’t match. Without documentation, a reconciliation difference becomes a mystery that requires trial and error.
A recurring cause of year-end errors is unclear ownership. If no one owns the process end-to-end, then critical steps may be missed or duplicated. Clear accountability improves speed and accuracy.
Even if your business is small, assign roles for:
These roles can rotate across staff, but the process should remain consistent. When the same responsibilities are repeated each year, your workflow improves rather than resets.
Because contractor-payment workflows often involve multiple non-finance staff, you can improve outcomes by providing simple “do and don’t” rules.
For example, you might instruct staff:
Training reduces the likelihood that the database will become inconsistent over time, which is the root cause of many year-end issues.
A high-quality approach includes dry runs. Instead of waiting until year-end, you can test the workflow with smaller sets of transactions and a sample of contractors.
Testing can involve:
This makes the year-end process more predictable. When you test earlier, you fix the underlying logic rather than scrambling when the deadline is close.
The conclusion in this guide emphasizes a simple rule: don’t trust the output until the inputs and totals reconcile. It’s worth expanding on what that means in practice.
Trust isn’t binary. You can build trust in layers:
Only after these layers are validated should you treat the output as reliable. Otherwise, you may have a false sense of security based on the output’s neat formatting.
Near the final week of year-end reporting, you can follow a focused checklist that reflects the earlier steps in this guide. This is not about reinventing the process; it’s about executing the controls you already designed.
When you execute this checklist, you reduce the risk of costly errors and improve confidence in your final outputs.
Using Square Payroll 1099 effectively comes down to governance: correct classification, complete payee data, accurate payment categorization, and disciplined reconciliation. When those elements are in place, the platform can serve its real purpose—helping you compile year-end information with less friction.
If you want a simple operational rule, use this: don’t trust the output until the inputs and totals reconcile. That principle keeps your process defensible, repeatable, and easier to correct if something changes late in the year.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
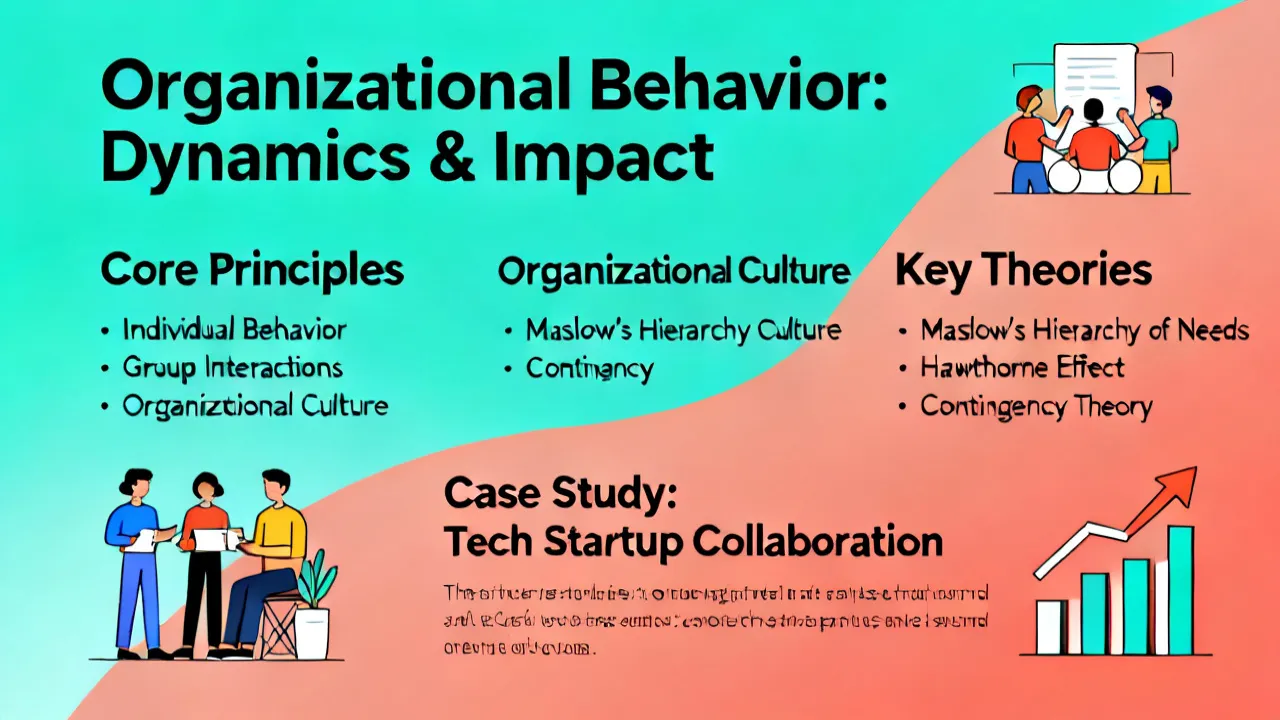
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
