Square Payroll 1099 helps businesses pay independent contractors while maintaining clear year-end documentation. This guide explains how 1099 reporting works at a practical level, what responsibilities employers typically have, and how Square Payroll-related workflows may support accurate records. It also provides a comparison table, a step-by-step process, conditions to watch, and objective FAQs.
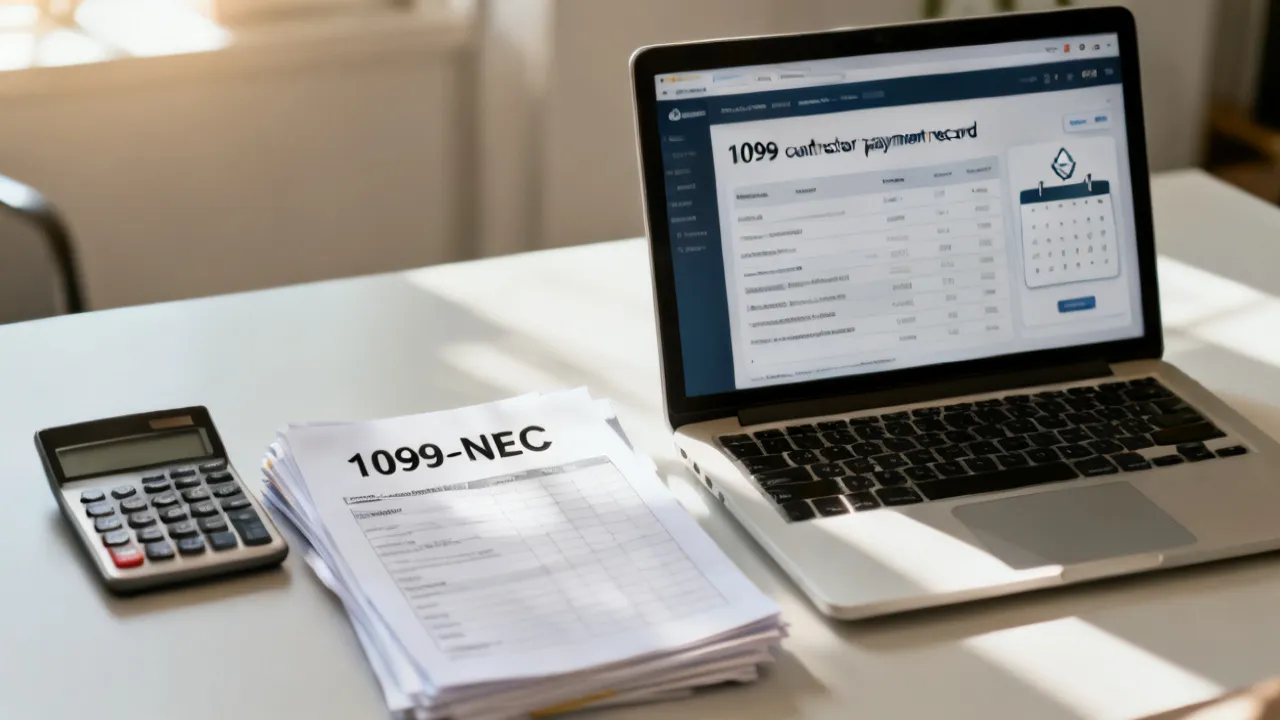
Using Square Payroll 1099 workflows can support organized contractor payment records, but the underlying responsibility for accurate 1099-NEC reporting still rests on the business. Start by mapping your contractor relationship, confirming tax documentation needs, setting up consistent payment coding, and validating totals before year-end filing. If you handle contractor payments through a platform, treat the system as recordkeeping support—not as a substitute for compliance.
In practice, “Square Payroll 1099” usually means leveraging Square-related payment and payroll workflows (or exports) to maintain a clear payment ledger for nonemployee compensation. The most important operational principle is that tools are only as good as the inputs you give them: worker identity, tax form status, classification decisions, and payment categorization. A reliable workflow therefore focuses on (1) collecting the right tax forms early, (2) ensuring your payment categories map correctly to your 1099-NEC reporting logic, and (3) running reconciliation checks so the final numbers you intend to file are consistent with both your bookkeeping and IRS reporting rules.
Another core takeaway is that compliance is not limited to the year-end moment. Building a small set of controls—such as monthly reconciliation, payee master data management, and documented adjustments/refund handling—prevents most year-end problems. When businesses wait until December to sort out missing W-9s or ambiguous payment categories, they typically end up with costly corrections, contractor disputes, and filing delays. When businesses treat contractor reporting as a “continuous accounting control,” they maintain defensible records and reduce uncertainty right when accuracy matters most.
Form 1099-NEC is generally used to report nonemployee compensation—payments made to independent contractors for services performed. For many organizations, this becomes a year-end compliance requirement rather than a mid-year task. The U.S. Internal Revenue Service (IRS) outlines requirements for reporting nonemployee compensation and related filing timelines in official guidance.
Because tax rules depend on your specific facts—such as whether a worker is truly an independent contractor vs. an employee—very businesses focus on two practical goals: (1) correct classification and (2) accurate totals per payee for the tax year. When platforms assist with records, they can reduce manual errors, but they cannot determine worker classification or the legal obligation to file. A tool can help you capture and organize the data, but it cannot replace the organization’s responsibility for compliance determinations.
Many businesses also need to ensure they can defend their reporting if questions arise later. Even if you are not being audited, having well-kept records reduces confusion when contractors ask why their tax statements differ from what they expected. Good records also reduce the operational friction of reissuing corrected forms when you later discover a missing payment, a refunded transaction, or a payee name/TIN mismatch.
For reference, the IRS provides authoritative information on Form 1099-NEC and filing requirements via its official pages and instructions for the form. (Sources: IRS “Form 1099-NEC” and IRS instructions for Form 1099-NEC; IRS Publication 15 for general employment tax concepts.)
In day-to-day terms, teams commonly use payroll and payments platforms to streamline scheduling, payments, and recordkeeping. When you hear “Square Payroll 1099,” the typical intent is understanding how a payroll or contractor-payment workflow can help capture payment data needed for year-end tax reporting.
From an industry-expert perspective, the very valuable outcome of using a tool-driven approach is consistency: the same payees are identified the same way across the year, payment types are coded consistently, and totals can be reviewed before any tax reporting deadlines. That said, the reporting correctness still depends on whether each payee’s tax form status (e.g., W-9 collection and validation) and the payment classification align with the applicable IRS rules.
Operationally, a platform such as Square can often act as a “single source of transaction truth” for many businesses. That can reduce the risk of transcription errors that occur when you manually combine spreadsheets, bank statements, invoices, and card processing reports. However, “single source of truth” only holds when you intentionally configure your workflow: you must decide which transactions count toward reportable compensation, how to tag them, and how to handle exceptions such as chargebacks or partial refunds.
In other words, “Square Payroll 1099” should be understood as a process pattern: use a modern payment platform to standardize payee/payment capture and then map those records into your 1099 logic. The compliance conclusion—whether a payment is reportable on 1099-NEC and whether the worker is an independent contractor—still requires you to apply the relevant rules to your facts.
For many small and mid-sized businesses, this distinction matters because they often pay contractors across multiple channels: card payments, bank transfers, invoiced checks, or reimbursements. Even if one channel is handled through Square, your total contractor payments may not be fully represented unless your overall workflow includes a method for collecting and integrating information from other payment sources (or clearly excluding non-reportable amounts).
Not all “non-salary” payments are treated the same for tax reporting. While independent contractors may require 1099-NEC reporting in many cases, the reporting scope can differ based on payment types and thresholds. Businesses usually mitigate risk by maintaining documentation that supports the treatment of each payment.
Some practical scenarios you’ll see in the field:
To reduce ambiguity, many organizations create internal definitions for what belongs in the “reportable contractor payments” category. That category often includes fees paid for services but may exclude certain reimbursements if they meet specific criteria. Another common scenario is payments that appear similar in the ledger but have different tax treatment depending on contractual terms (for example, a contractor invoice that includes both taxable service fees and non-taxable pass-through charges).
Finally, consider the practical issue of payee identity. A business might have a contractor who changes their legal name or uses a DBA (doing business as). If the W-9 shows the legal name and the payment record shows a DBA name, the mismatch can cause filing problems. Good workflows include a “payee master record” that stores the legal name and TIN from the W-9 and links that to the payment activity under a consistent identifier.
Think of Square Payroll 1099 readiness as a control system rather than a single year-end scramble. A reliable approach usually includes five components: worker classification intake, tax form collection, payment capture and coding, reconciliation, and review before filing.
An operations-first mindset reduces surprises. For example, teams that collect tax information early can avoid last-minute holds. Teams that reconcile totals monthly can catch mapping issues sooner—when corrections are simpler and fewer parties are affected.
One reason “recordkeeping support” matters is that many businesses discover data quality issues late: a payee’s TIN on file is incomplete, a payment is coded to the wrong payee, or refunds are logged under a different transaction type. When these issues are discovered months later, they can require rework across accounting records and contractor communications. If you keep a steady cadence, you can correct the underlying data sooner—before the ledger becomes “locked” for tax reporting.
From a design perspective, your workflow should aim to answer the question: “For each contractor/payee, what amount did we actually pay them for reportable services during the tax year, and is our payee tax information complete and validated?” That question should be answerable at any time—not only at year-end.
To make it more concrete, a mature workflow typically uses:
Tools can accelerate these tasks, but you still need policies that define how your business interprets transactions and which adjustments are included in the final 1099-NEC amounts.
Because “Square Payroll” can be offered with varying plan structures, add-ons, or country-specific availability, it’s important to confirm the current cost and plan terms directly with the provider for your location and business type. Similarly, if you’re evaluating a supplier or service package that supports “Square Payroll 1099” workflows, treat advertised pricing as plan-dependent and validate what each plan includes (e.g., tax form support, record access, and reporting exports).
In a compliance-driven workflow, the question isn’t only “What does it cost?” but also: “What data can I export, reconcile, and retain for audit readiness?” If a tool provides reporting exports, review whether you can access historical records and payee-level totals for the relevant tax year.
It’s also wise to ask how the platform handles the operational details that matter for reporting accuracy:
In general, “plan details” translate into practical compliance risk. If the plan does not let you access the detailed payee ledger you need, you may end up relying on manual work. That manual work increases error risk, which can undermine the purpose of adopting a workflow system in the first place.
The table below rephrases supplementary information in a structured comparison format (no links included) to help you distinguish what tools typically do and what organizations must still verify.
| Topic | What payment/“Square Payroll 1099” tools often support | What your business must still verify |
|---|---|---|
| Payee identification | Consistent payee profiles and payment ledger entries | Correct legal name, tax status documentation, and accurate mapping to each payee |
| Tax document collection | Storage or workflows that help track required forms (e.g., W-9 collection status) | Whether collection was completed and whether any backup withholding rules apply in your situation |
| Year-end totals | Aggregated payment totals by payee for a tax year | That totals reflect net amounts required by IRS reporting rules (including adjustments/refunds where applicable) |
| Filing readiness | Exports, summaries, and audit-friendly records | Whether filing is required, which forms apply (e.g., 1099-NEC), and meeting IRS deadlines |
| Tax compliance | Recordkeeping and operational support | Legal responsibility for filing accuracy, worker classification, and compliance posture |
Below is a practical, step-by-step approach many businesses use to reduce errors while supporting year-end readiness for nonemployee compensation reporting.
The approach below assumes you have a workflow that captures contractor payments through Square or otherwise provides exportable payment data. If you pay contractors through multiple payment methods, you can still use the same logic by integrating those sources into your payee ledger (either manually or via accounting system imports), then applying the same reconciliation and QA checks.
Before any reporting workflow, confirm classification. The IRS uses behavioral and control factors to distinguish employees from independent contractors. This is not simply a paperwork exercise. Maintain documentation of your classification rationale and facts about the working relationship.
Condition/requirement: If your worker classification is uncertain, consider professional tax guidance before relying on any automated reporting workflow.
To implement this step operationally, many businesses create a simple classification checklist that captures key facts such as:
Even though the exact legal test is more nuanced, having documented answers to these practical questions makes it easier to support your reporting decisions later. It also helps when contractors dispute their classification or request explanation for why they did or did not receive a 1099.
For independent contractors, many businesses collect Form W-9 to obtain a legal name and tax identification number (TIN). Validate that the payee details match what you have in your payment records.
Condition/requirement: If a W-9 is missing or invalid, reporting and withholding obligations can change depending on the circumstances and IRS rules.
To reduce errors, validation should include more than “form is present.” A practical validation process often includes:
Businesses sometimes delay W-9 collection until after the end of the engagement. A better practice is to collect the W-9 before the first payment whenever possible. That way, your payment ledger can be linked to correct tax information from the start. When you wait, you risk having to retroactively correct payee mappings and transaction assignments.
If your organization pays contractors through invoices, service agreements, or time-based entries, ensure there’s a consistent way to categorize each payment as reportable nonemployee compensation (where applicable). The goal is to reduce “miscellaneous” payments that later become ambiguous.
Condition/requirement: Establish internal guidance for what counts as reportable contractor payment in your ledger (and document exceptions).
Standardization often starts with a payment “taxonomy”—a list of categories and tagging rules. For example, your taxonomy might include:
The key is consistency: if a team uses different category names, or applies categories differently across departments, your final totals may be wrong even if your platform totals are “correct” according to its logic. Therefore, you should document the coding rules and train anyone who enters transactions or approves contractor payments.
Operationally, the easiest time to fix record errors is when they happen. Use your system’s reporting exports or internal reconciliation methods monthly or quarterly. This reduces last-minute surprises in totals.
Condition/requirement: Maintain consistent payee IDs across the year so payments roll up correctly.
A continuous approach often includes a routine of:
Continuous capture also helps address contractor disputes. If a contractor says, “I invoiced you for $1,500 and you only paid $1,200,” monthly reviews give you time to investigate before the tax reporting stage. That reduces corrections later.
Even when tools help summarize totals, you should reconcile those summaries to your accounting system. Reconciliation helps catch differences caused by refunds, voided transactions, or reclassifications.
Condition/requirement: Document reconciliation steps so the process is repeatable and defensible.
Reconciliation is not only “make the numbers match.” It is also “understand why they differ.” Common reconciliation drivers include:
To keep reconciliation defensible, many businesses store reconciliation worksheets and export files with timestamps. That documentation can help if someone else needs to repeat your process later or if there’s an internal or external question about how you produced year-end totals.
Before any filing, conduct a QA review: compare payee lists, ensure names and TINs align with your W-9 records, and verify net totals. This is where many errors can be prevented.
Condition/requirement: Use a consistent review checklist and sign-off process internally.
A practical year-end QA checklist often includes:
To reduce last-minute problems, consider requiring two-person review for critical tasks: one person performs the data extraction and totals calculation; another performs the QA verification. Even in small teams, this simple control reduces the risk of a single person making and missing a mistake.
Once ready, filing should follow IRS instructions for Form 1099-NEC and any applicable state requirements. Deadlines can vary based on filing method and whether you file electronically.
Condition/requirement: Confirm the current tax year filing requirements from official IRS guidance.
Year-end filing has both operational and compliance components. Operationally, you need the final data in the correct format. Compliance-wise, you need to ensure that the amounts and payee information are correct and that you file with the correct method and due date. Additionally, you may have requirements to furnish statements to recipients (contractors) by applicable deadlines, which may differ from IRS filing deadlines depending on filing method.
Because requirements and deadlines can change, you should always rely on the most current instructions for the relevant tax year. Many businesses incorporate a “compliance calendar” that tracks: deadline for collecting missing W-9s, internal review dates, deadline for generating forms, and deadline for IRS filing/electronic submissions and recipient statements.
It can be helpful to treat your “conditions and requirements to watch” as a standing agenda item at regular process check-ins. Many year-end issues are recurring, not one-time. If you address them continuously, you improve year over year.
Another frequently overlooked item is the quality of your internal workflow documentation. If you define what “reportable” means in your ledger but do not document it in a way that a new team member can follow, you may see errors when responsibilities change. A lightweight but clear written policy is a valuable investment.
It commonly describes the use of Square-related payroll or payments workflows to organize contractor payment records in a way that supports year-end tax reporting for nonemployee compensation. The tool can help with recordkeeping, but the business remains responsible for correct compliance and filing.
No. A platform can streamline data capture and provide totals, but the business must verify worker classification, payee information, and that amounts reported match the applicable IRS rules. Even if the platform exports a “1099 summary,” that export is not the legal determination. You still have to confirm classification and reporting logic and make sure the output is accurate for your specific situation.
In other words, treat platform output as a starting point for review. Your final compliance output must be supported by correct underlying payee and payment data and consistent with tax reporting requirements.
Document how reimbursements and expense portions are treated. The correct reporting approach depends on the nature of the payment and the agreement between you and the contractor. If you have mixed invoice structures, reconcile carefully and consider professional guidance when unsure.
Operationally, many businesses handle this by requiring contractors to submit itemized invoices that separate services from reimbursable expenses. Then, the ledger coding can tag each portion correctly. If your platform supports line-item reporting or categories, use those capabilities to keep the expenses and service fees distinct. The goal is to avoid treating the entire invoice as compensation when only part of it may represent reportable nonemployee compensation.
Incomplete or missing W-9 information can affect your compliance steps. Review your records promptly, request updated forms, and ensure your process matches current IRS guidance for situations involving missing or incorrect TIN information.
From a process standpoint, you should define an internal escalation step. For example, if a W-9 is missing by a certain point in the year (or by a certain cutoff date before you finalize totals), you either pause payments until the W-9 is collected (if your business model allows) or you implement whatever withholding/reporting approach is required by guidance for missing TIN scenarios.
Also, keep the contractors informed. A simple communication—requesting the missing form and specifying what’s required—reduces confusion and speeds resolution.
Yes. The IRS provides the authoritative instructions and background for Form 1099-NEC. Use IRS form instructions and IRS publications relevant to reporting and employment tax concepts.
For businesses building a workflow, it is best practice to align your internal checklist to the exact language of the official form instructions, especially for topics like who must be reported, how to report amounts, and what exceptions or special cases apply.
If your content workflow substitutes a location placeholder with “nearby,” it indicates the article is being written without a specific city or country. In that case, you should confirm any local or state rules separately, since tax reporting requirements can vary by jurisdiction.
Monthly reconciliations are generally a strong practice because they reduce end-of-year complexity. However, ensure that your final year-end totals reflect all adjustments, refunds, and corrections up to filing deadlines.
To make monthly summaries truly reliable, you typically need a closing process that includes: confirming the completeness of transactions during the month, capturing any post-month adjustments that impact net totals, and ensuring the payee mapping is stable. When monthly summaries are used properly, they become a “living trail” that you can roll forward.
For many businesses, Square Payroll 1099 workflows represent a practical way to organize contractor payment data. The top outcomes come when you use the system to maintain consistent records throughout the year—while keeping compliance responsibilities clearly owned by your organization. By following a structured process (classification confirmation, W-9 validation, standardized payment coding, ongoing reconciliation, and final QA), you can approach 1099-NEC readiness with more confidence and fewer last-minute corrections.
The deeper lesson is that technology should reinforce good process controls. When your payee identity is consistent, your transaction coding is standardized, and your reconciliation cadence is steady, your year-end work becomes a verification exercise instead of an emergency. That mindset—data quality throughout the year, clear internal documentation, and careful alignment to IRS instructions—creates a workflow that supports both operational efficiency and compliance integrity.
Ultimately, you should view any “1099 support” capability as recordkeeping assistance. Your responsibility includes ensuring that payments were made to independent contractors (not employees), that tax information is accurate, and that the amounts reported reflect net compensation according to IRS rules and your documented approach to refunds/adjustments. When those responsibilities are met, platform-supported workflows can be a strong foundation for accurate and defensible 1099-NEC reporting.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
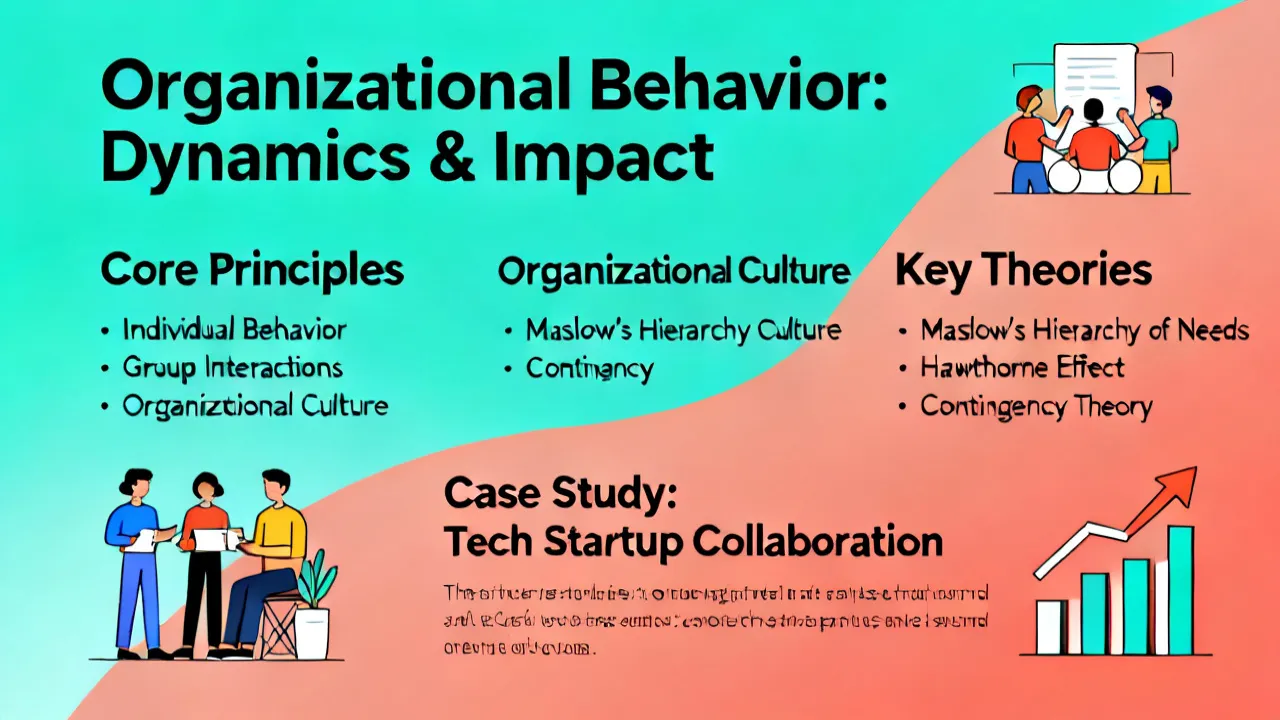
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
