This guide explains how Square Payroll supports contractor payment documentation tied to 1099-style reporting, focusing on practical compliance steps. Objectively, 1099 reporting is used in the U.S. to document certain payments made to non-employees, while payroll platforms help track pay details, classifications, and records required for tax preparation.
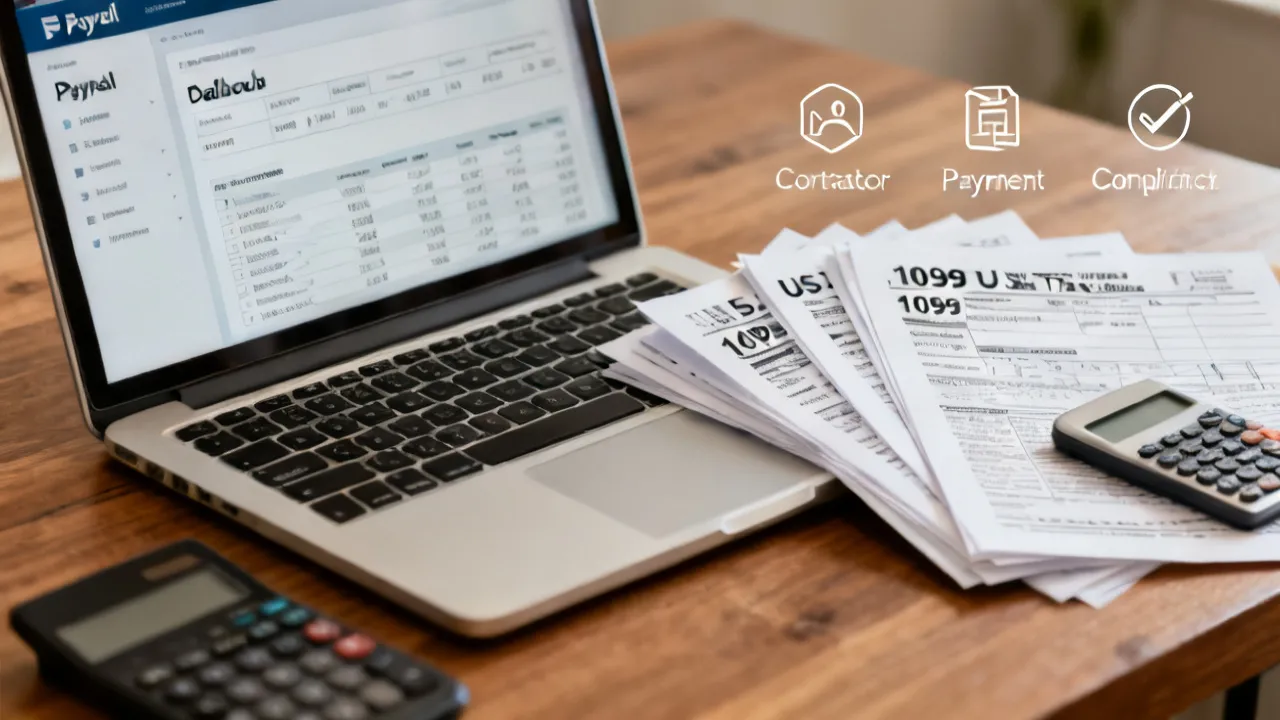
Square Payroll 1099 workflows help business owners organize payments to non-employees and align internal records with U.S. tax reporting practices. The very important actions are to (1) classify workers correctly, (2) capture required contractor details at onboarding, (3) maintain accurate payment and tax-year records, and (4) prepare statements in time for your tax professional or tax filing workflow.
From an industry perspective, the real “value” of a payroll system is not just producing documents—it is creating a defensible audit trail: who was paid, how much, for what period, and under what classification. That audit trail tends to matter very when you’re reconciling bank activity, invoices, and payment summaries.
In everyday business operations, the phrase Square Payroll 1099 generally refers to how a payroll or workforce platform supports the documentation process associated with contractor payments. In the U.S., “1099” commonly describes information returns issued to certain non-employee recipients. While platform terminology may vary, the underlying operational goal is consistent: ensure payments to contractors are tracked and summarized in a way that supports tax reporting.
It is essential to separate two concepts:
Square Payroll-style systems can streamline the second concept by structuring payment data by pay period, recipient, and tax year. However, the classification decision is driven by facts and circumstances, not by what form names appear in software. In other words, a correctly configured workflow still can’t fix a fundamentally incorrect classification decision.
Businesses that pay contractors typically face three recurring pressure points:
An expert approach focuses on controls—repeatable processes that minimize surprises. Even if your team is small, creating a simple “data readiness” checklist can reduce risk and rework. Many small businesses only “feel” the complexity in December. Controls implemented in January through November often make December far calmer.
In the U.S., information returns like those commonly referred to as “1099” are typically used for reporting certain payments made to non-employees. These reporting obligations depend on the payment types involved and your relationship with the recipient.
To keep this discussion objective, it’s helpful to treat the process as a data governance workflow:
When systems are well configured, you spend more time reviewing edge cases and less time reconstructing history after year-end. When systems are not configured—or when data entry is inconsistent—you end up doing “forensic accounting” on your own business records, which is both stressful and time-consuming.
Many businesses adopt workforce tools because the volume of transactions and recipients grows over time—especially in service industries, professional affordablelancing arrangements, and specialized gigs.
From an operational standpoint, Square Payroll-related features can provide practical advantages:
That said, businesses should always validate that the platform’s summaries align with how the contractor relationship is treated under relevant tax guidance. A platform can format your data, but it cannot replace the obligation to understand whether the underlying relationship qualifies for contractor reporting or whether the payments fall under different reporting categories.
While “contractor” arrangements appear in many fields, the following categories often involve frequent independent contractor engagements:
For each category, the practical challenge is similar: consistent tracking and correct classification. Creative or marketing contractors may involve milestone payments, retainer adjustments, and subscription-style services. Skilled trades may involve partial payments, change orders, and schedule variances. In each case, the “1099 workflow” is really about capturing the payment story clearly enough for someone else—your accountant, your tax professional, or an auditor—to understand it without guesswork.
To keep compliance efforts realistic, plan around the operational requirements that typically determine whether your year-end process goes smoothly:
These are not “nice to haves.” They’re the mechanics that reduce the probability of corrections later. If you treat contractor onboarding as an afterthought, you might discover in December that addresses are wrong, names are inconsistent across invoices, or taxpayer ID details are missing entirely. That discovery usually triggers a scramble that costs far more than doing it properly throughout the year.
If you think of your reporting process like a supply chain, Square Payroll (and similar platforms) act as a system of record for payment data. Your suppliers in this workflow are:
In other words, the platform supports the process, but it does not replace professional judgment.
This framing is useful because it clarifies where breakdowns happen. If a contractor’s payment information is missing, the issue might originate from the contractor’s onboarding workflow. If the totals are off, the issue might originate from your reconciliation rules or your handling of reversals, refunds, or chargebacks. If the filing is rejected or corrected, the issue might originate from how data was interpreted for tax forms.
Below is a general, objective operational guide that many organizations use to structure their year-end tasks related to contractor documentation. It is not legal advice; treat it as a process blueprint to reduce errors.
| Area | What to Compare | Common Requirements/Conditions |
|---|---|---|
| Worker setup | Employee vs. independent contractor classification method | Consistent classification rules; documentation of how you determined status |
| Recipient data | Whether onboarding details are complete and current | Accurate recipient identity details and current contact information used for statements |
| Payment mapping | How transactions are coded to recipients and pay periods | Uniform coding practices; handling of reversals, voids, and refunds |
| Year-end close | Reconciliation between bank activity and system summaries | Review totals; investigate discrepancies before preparing statements |
| Document output | How the system generates recipient statements or tax-year reports | Verification that totals by recipient match internal records; readiness for tax preparer review |
| Review and corrections | Process for addressing errors before/after finalization | Clear ownership (who reviews what); time reserved for corrections and resubmission steps |
| Record retention | Where evidence is stored and how long it’s kept | Secure storage of payroll/payment history and contractor onboarding records |
First: lock down worker classification. If someone is misclassified as a contractor when they should be an employee (or vice versa), your reporting and tax obligations can become inconsistent regardless of the payroll system. This is where many businesses face corrections later.
Second: treat contractor onboarding data quality as a control. Missing information is one of the very common operational failure points. A disciplined onboarding checklist—completed early in the contractor relationship—reduces end-of-year risk.
Third: implement a reconciliation routine. Reconcile payments to recipients against payout batches and bank transactions. This doesn’t require complex tools; it requires consistent review.
Many teams also benefit from a “mid-year check” (for example, a review in July) that catches issues early. When you do it late, everything becomes a scramble: contractors may be hard to reach, and bank statements may be harder to reconcile due to intervening activity. A mid-year check does not replace year-end work, but it often reduces the size of year-end surprises.
As your operations scale, errors often arise from edge cases. Consider building a small list of “must review” items:
From an accounting operations lens, these checks are often more valuable than relying solely on whether a generated statement “looks right.” Totals and mappings matter.
To make those checks more actionable, many businesses create simple metrics dashboards or spreadsheets. For example: “total paid per contractor vs. expected range,” “number of contractor records created,” “percentage of contractors with complete onboarding,” and “number of payments missing a recipient mapping.” Those operational indicators help you catch issues before you generate final reporting documents.
You referenced “price information” in your instructions, but no concrete price figures were provided in the prompt. For that reason, this article does not state specific costs. In practice, Square and similar platforms may change pricing tiers based on features, processing volume, and plan type.
Top practice: confirm pricing directly from the official product pages or your Square account dashboard, and ensure the features you need (such as contractor documentation support) are included in your selected plan.
Operationally, the more relevant “pricing” factor is not just the subscription cost—it’s the cost of errors. If an underpowered setup requires significant manual cleanup, your total cost of compliance (time + rework + accountant fees) can far exceed the incremental cost of a better configured system.
Your request also asked to incorporate supplier details. No supplier names or third-party vendors were provided in the prompt. In a compliance workflow, the “suppliers” are better understood as the parties and systems that provide critical data—namely the platform (Square Payroll), the payment funding source (your business accounts), and the tax service provider who interprets obligations.
If your organization uses additional tools (accounting software, invoicing systems, or document preparation services), ensure their outputs align with the payment mappings used for contractor documentation.
It can help to define each “supplier” in practical terms:
By treating these as suppliers of data (not suppliers of truth), you can implement cross-checks and reduce reliance on a single system’s assumptions.
Generally, these systems summarize payments based on how workers are set up and how transactions are mapped. However, your obligation depends on your facts and applicable tax rules. Many businesses treat classification and required reporting as a combination of platform-supported data and human review.
A useful way to think about this: the software can help generate totals and format the output, but the “must file” determination is ultimately grounded in the relationship and the types of payments involved. If a business sets up a worker incorrectly (or records payments under an incorrect category), the system will follow that structure.
Reconcile step-by-step: confirm the payout schedule, check for reversals/voids/refunds, verify recipient mapping, and review posting dates. If the discrepancy persists, document it and consult your accountant or tax professional before finalizing year-end statements.
In practice, mismatches often come from one of these operational scenarios:
Documenting the reconciliation steps matters because if a correction is later required, you’ll want evidence showing how you identified and resolved the issue.
Often, yes—at least from an operational standpoint. Incomplete recipient information can delay statement preparation and can increase the chance of corrections. As a matter of control, many organizations complete onboarding before issuing major payments.
There’s also a practical benefit: onboarding early helps you confirm that the contractor record is consistent with invoices and service agreements. If a contractor uses a legal name on a tax form but an alias in your invoice system, you may end up with inconsistency that triggers additional review later.
Some businesses choose to allow small “starter” payments while onboarding is pending, but they still maintain a control checklist to ensure that all required identity data is complete before year-end reporting deadlines.
No. Classification (employee vs. independent contractor) is a substantive determination. “1099” terminology describes common information-return reporting in the U.S. These concepts interact, but they are not identical.
This distinction matters because software that “labels” workers can create a false sense of certainty. A worker might be labeled a contractor in your system, but if facts indicate the worker is effectively an employee, the compliance implications change. Conversely, a worker could be labeled in an unexpected way but still meet the facts that support independent contractor status.
Record retention periods can vary based on circumstances and applicable requirements. A practical approach is to follow guidance from authoritative sources and your professional advisor, keeping documentation for at least the period your business needs to support audits and tax inquiries.
From a practical operations viewpoint, retention should include:
Even when you are not required to keep every artifact indefinitely, keeping a cohesive set of records for at least the relevant periods reduces risk and speeds up responses if questions arise.
It’s risky to treat outputs as fully self-validating. Software is only as accurate as the data and configuration you provide. A short review process—especially for edge cases—improves reliability.
Many businesses reduce review time by building targeted review lists rather than reviewing everything manually. For example, review only recipients with incomplete onboarding, recipients who received refunds or reversals, or recipients with unusual payment patterns. This makes review scalable, especially when contractor volume grows.
For objective guidance, consult the IRS official resources and instructions related to relevant information returns. These are the very authoritative sources for requirements and definitions.
In addition to IRS resources, some businesses consult professional advisors to interpret specific facts—especially for complex contracting arrangements where payment structure, contract terms, or workflow controls might affect classification or reporting category treatment.
When teams think about Square Payroll 1099 processes, they often focus on the end-of-year output: generating statements, ensuring totals look correct, and submitting forms on time. Those tasks matter. But the real operational value is the creation of a defensible audit trail that connects four items:
A defensible audit trail does not mean you need to be overly complicated. It means you can answer questions like: “How did we determine this recipient’s totals?” “Why does this contractor have a different name on file?” “How did we treat a refund that occurred in January but related to services provided in December?”
Systems like Square Payroll can store the payment facts and can help generate reporting totals. But the defensibility depends on your governance: consistent coding rules, disciplined onboarding, and a documented approach to reconciliation and corrections.
The classification decision is the foundation that everything else rests on. Even if a platform supports contractor reporting workflows, the underlying obligation is fact-based. A classification process typically includes:
From an operational perspective, the best practical “control” is not to guess at classification at year-end. Instead, implement a classification review step when onboarding a new contractor and periodically revisit relationships if circumstances change. If you only revisit classification after you receive a tax reporting correction, you lose the ability to fix issues proactively.
Consider storing a brief classification memo internally, even if it’s simple. It can include: the dates you reviewed the worker status, the factors you relied on, and any contract terms relevant to the relationship. Keeping this memo does not guarantee you will never face questions, but it significantly improves your ability to respond if questions arise.
Contractor onboarding is where many errors begin. A robust onboarding checklist usually covers three categories: identity, payment preferences, and data integrity for reporting.
Identity and contact details typically include:
Payment-related data typically includes:
Data integrity for reporting includes:
A key control idea is to avoid “free-form” data entry at the end of the year. If you wait until November or December to correct recipient details, you often find that contractors are busy, addresses have changed, and historical transactions have already been coded. Fixing historical data after the fact usually requires manual edits or adjustments that raise the chance of another error.
Payment mapping is often where systems and human workflows diverge. Even if the platform is configured correctly, inaccurate coding practices can create wrong totals or wrong recipients.
A practical approach to payment mapping includes:
Some teams discover that mapping is inconsistent across departments. For example, finance codes payments one way, while operations codes them another way in a separate tool. That inconsistency makes reconciliation harder and increases correction risk. The solution is to enforce a single mapping standard for the system of record and train relevant staff to follow it.
Year-end close is not just “run the reports.” It’s the moment when you verify that your internal system and external bank activity agree, at least to the degree required for your reporting process.
A strong reconciliation routine includes:
Many businesses do not document reconciliation steps thoroughly. When corrections are required later, they end up repeating work. A lightweight reconciliation log—stored in a shared folder—often saves hours the next time you do year-end close.
Another best practice is to implement a “freeze” period where you limit adjustments after a certain date, or at least control who can adjust transactions. Uncontrolled late edits can create mismatches between what you generated and what’s in the system later.
Even if your primary objective is to file with the IRS (as applicable), many workflows require you to provide recipient statements as part of the process. That means timing matters not only for filing deadlines, but also for recipient review and correction.
A practical statement generation timeline often includes:
If you wait until the last moment to generate statements, you may not have time to resolve corrections. A small buffer (even a week) can prevent last-minute chaos.
Edge cases are where “generic advice” stops working. Common edge cases include:
Even without getting into legal specifics, the operational best practice is to define how your process treats each category. If you do not define it, different staff might handle the same situation differently, leading to inconsistent totals.
A mature workflow includes a correction process. Corrections can happen for many reasons: identity data errors, mapping errors, or timing errors discovered during reconciliation or recipient review.
Operationally, you should define:
When corrections occur after finalization, the process may become more complex. Having a clear pre-finalization correction workflow reduces the number of after-finalization issues.
Record retention is often treated as a policy topic rather than an operational one. In practice, record retention affects how easily you can reconstruct history when something goes wrong.
A cohesive retention set typically includes:
Additionally, retention should cover versioning: if you change recipient data after the fact, you may want to retain evidence of what the data was at the time you generated the draft or final outputs. Without versioning, it becomes hard to explain why the final output differs from earlier drafts.
Small teams often assume that “someone” will take care of 1099 workflows. But defensible audit trails require clear role separation.
A practical division of responsibilities might look like this:
Even in a one-person business, you can simulate “segregation of duties” by adopting a simple internal review rule: generate drafts, check them against reconciliation logs, then generate final outputs only after sign-off.
In many organizations, contractor payments involve multiple systems: invoicing software, accounting software, payment platforms, and payroll/workforce tools. Data drift—where fields differ across systems—is a common cause of mismatch.
To avoid drift:
These steps reduce reconciliation discrepancies and reduce the number of manual adjustments needed at year-end.
To make the earlier “data readiness” concept actionable, you can implement a checklist that runs throughout the year rather than only at year-end.
Monthly or quarterly checks might include:
Pre-year-end checks might include:
Doing these checks repeatedly often yields a more stable year-end close and fewer urgent corrections.
While each business’s facts differ, the following scenarios illustrate how the process controls work in real life.
Scenario A: Correctly mapped payments with a refund
A contractor provides services in December, and you pay them through the platform. In January, you refund part of the amount due to a service correction. Your workflow should record the refund as an adjustment that impacts totals in a consistent and traceable way.
The key control is traceability: you should be able to explain why the final total differs from the gross payment total.
Scenario B: Recipient identity mismatch due to name formatting
A contractor’s invoice uses “ACME Studio LLC,” but the contractor profile in your system was created as “Acme Studio.” If you generate statements based on recipient profile names, you may later need corrections or clarifications.
Even if your totals are correct, identity formatting errors can create administrative problems during recipient review.
Scenario C: Duplicate contractor profiles
A contractor changes their business name mid-year. Someone creates a new profile because they assume the name change requires a new record. Payments get split between two profiles.
Duplicate profiles can be especially damaging because the output statements may still be “correct” per profile, but the overall reporting story becomes incomplete.
If you pay a contractor through more than one method (for example, platform payouts plus checks), your “system of record” strategy determines how you capture the full set of payments. A practical control is to ensure all payment channels roll up into your year-end summary by contractor, with consistent mapping and a clear reconciliation approach. If you rely on one system alone, you may omit payments made elsewhere.
If a worker’s facts change—e.g., they move from independent contractor work to a role that more closely resembles employee status—your governance approach should include how you represent that change in your system and how you review compliance implications. Operationally, you want to avoid mixing payment mapping across different classifications without a clear explanation and a consistent record of changes.
No. Documentation doesn’t need to be “perfect” to be helpful, but it should be coherent and traceable. Even a concise onboarding checklist, a short internal classification memo, and reconciliation notes can provide substantial support. The goal is to reduce uncertainty and provide evidence trails that answer questions without requiring re-derivation from scratch.
If you want a practical “control list” to guide your operational work, focus on:
When these controls are in place, Square Payroll 1099 processes become less about stress and more about routine governance.
Every business has its own complexity: different payment structures, varying contractor volume, and different accounting systems. Even with a strong platform workflow, it is helpful to align your internal process with how your tax professional expects to receive documentation.
As you refine your workflow, consider sharing your:
This alignment helps ensure your internal records support a smooth tax-year close and reduces the likelihood that your tax professional needs to reconstruct payment history from scratch.
If you want, share your typical contractor payment types (e.g., services only, reimbursements, platform-based payouts) and your general workflow (invoices vs. direct platform payments), and you can tailor a tighter checklist around a Square Payroll 1099-style year-end close—without using any unverified pricing or uncertain claims.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
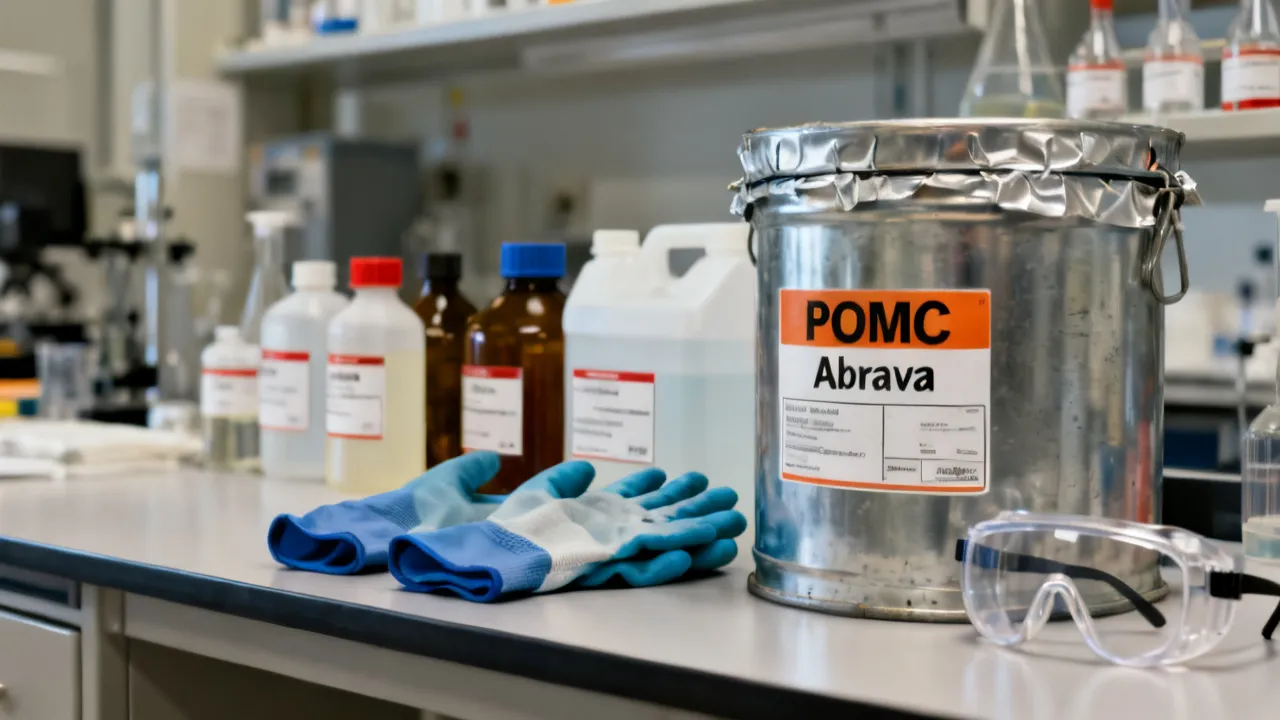
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
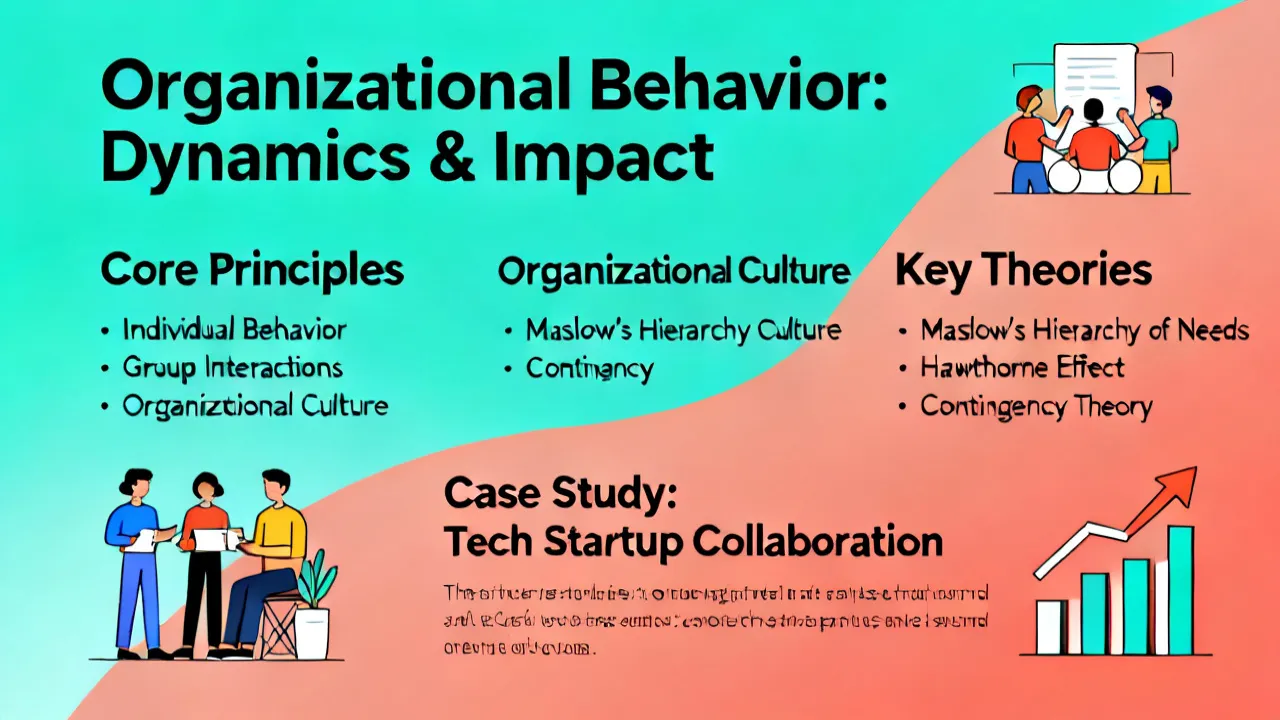
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
