This guide explains how Paychex 401k Fidelity partnerships work, what plan participants typically see in administration, and how to evaluate fund and service alignment. Background context covers 401(k) rollovers, recordkeeping responsibilities, and the role of major providers in day-to-day employer reporting. It also highlights practical steps and common conditions for enrollment, changes, and contribution management.
If your employer uses Paychex for benefits administration and your plan is supported by Fidelity, the very important thing to understand is how recordkeeping, payroll contribution flow, and participant access fit together. “Paychex 401k Fidelity” commonly refers to the operational bridge between an employer’s payroll/HR platform (Paychex) and a retirement plan services provider (Fidelity) that helps participants manage their 401(k) accounts, investments, and recurring plan transactions. While the exact menu of services depends on your employer’s plan documents, the practical experience usually centers on contribution setup, fund selection, and administrative processing.
From an industry perspective, a well-run 401(k) relationship is less about any single interface and more about system design: payroll timing, employee eligibility rules, plan contribution elections, and the participant experience that translates those rules into clear action steps. This matters because participants rarely submit “investment orders” in a vacuum—many transactions are triggered by payroll cycles, plan eligibility windows, and established plan policies.
In this article, we’ll keep the emphasis on what participants should know first: what each party typically does, how contributions and elections usually flow, what could cause delays, what to review in plan disclosures, and how to verify that your choices actually applied. We’ll also cover practical scenarios—like new-hire onboarding, first paycheck timing, reallocations, rollovers, loans, and beneficiary updates—because those are usually where confusion (and avoidable mistakes) shows up.
In many employer setups, the HR/payroll workflow and the retirement recordkeeping workflow are separated for operational efficiency and risk management. For employees, that separation often shows up as two different “experiences”: a benefits administration platform used by HR and recordkeeping tools used by participants. When people say “Paychex 401k Fidelity,” they’re usually pointing to a combined ecosystem where:
Importantly, neither provider can override plan rules. If your plan requires a waiting period, places limits on contribution changes, or uses specific “effective dates,” those rules come from the plan document and governing policies approved by the plan’s responsible parties. Fidelity may implement the rules and provide the tools; Paychex may transmit or coordinate payroll data; but the underlying retirement plan terms are still the governing “source of truth.”
A common participant misconception is that “the provider” controls how fast things happen or what actions are possible. In reality, many timing details come from a combination of plan policy, payroll cutoffs, remittance schedules, and recordkeeping processing windows. This is why you’ll often see the same set of steps across many large employer plans—regardless of whether the interfaces are branded Paychex, Fidelity, or both.
401(k) systems are “time-sensitive” by design. Contributions are typically collected through payroll and then deposited and allocated according to established schedules. Any mismatch between payroll elections and recordkeeping processing windows can create employee confusion—such as seeing contributions later than expected or requiring additional confirmation before an election is implemented.
From an expert lens, the very common friction points tend to be:
These are not “performance issues” in the everyday marketing sense; they are normal consequences of how payroll and recordkeeping systems coordinate. When participants understand the “why” behind timing rules, they can manage expectations and avoid the common impulse to repeatedly re-submit the same election change.
For example, if you change your contribution percentage late in the payroll cycle, you may see the new rate start on a later paycheck. If you submit another change immediately, you could inadvertently alter the next period too, depending on how your plan’s deadlines work. Understanding effective dates can reduce these knock-on effects.
Even when the employer UI is different, the lifecycle is broadly similar across many large plan providers. A simplified flow often looks like this:
Because payroll and recordkeeping are linked, participants benefit from understanding when changes take effect and where to confirm that their elections were received and applied. “Received” and “effective” are not always the same. Many plan systems show that an election change is saved instantly, but the actual effective date may be tied to a payroll cutoff or eligibility confirmation.
It’s also useful to recognize that there may be multiple “events” that need to align:
Any one of these events could happen on a different day than you might expect. That’s normal. What matters is that the events reconcile over time and follow plan policy.
When people focus on “Paychex 401k Fidelity,” they are often trying to answer: “How good is the participant experience and how reliable is the administration?” In an objective evaluation, you generally cannot isolate recordkeeping quality from plan design. However, you can assess several factors that are repeatedly important in industry practice:
For participants, the top “benchmark” is often the plan’s formal disclosures—especially the Summary Plan Description and fee-related disclosures—rather than word-of-mouth or isolated anecdotes. Portal UI can feel intuitive or clunky, but the true measure is whether the plan is administered accurately and consistently over time.
If you are evaluating the plan as a participant (not as a plan administrator), you can use a practical checklist:
401(k) costs can take different forms: plan-level administrative expenses, recordkeeping fees, and underlying investment expenses (such as fund expense ratios). In practice, participants typically don’t see an “itemized bill” in the way they might for a bank account. Instead, costs show up through plan notices and fund pricing mechanics.
To evaluate costs in a defensible way, participants should:
If your plan offers a “total cost” view or includes fee statements in participant materials, treat those as starting points, then confirm against the plan’s official disclosures. This approach avoids assumptions and supports better decision-making. It also matters because “what you feel” about performance can be misleading if expenses are not considered.
It’s also worth understanding how fees can affect outcomes over time. Even small differences in expense ratios can compound across decades of saving. That doesn’t mean every plan with higher expenses is “bad,” and it doesn’t mean every plan with lower expenses is “good.” The right evaluation is contextual: what you’re getting (fund lineup quality, diversification, services) and what you pay (recordkeeping and fund expenses).
When participants want a simple action step, it’s usually this: find the fee disclosure section in your plan materials, note the recordkeeping/admin structure as described, and then focus on investment fund expense ratios and whether you can choose lower-cost share classes or broad-market index options.
Even when recordkeeping is strong, participants still have to choose from the plan’s offered investment options. Plan lineups may include indexed funds, actively managed funds, target date funds, stable value options, or other strategies. The right choice depends on time horizon, risk tolerance, liquidity needs, and whether you’re building a retirement allocation versus managing shorter-term goals.
From an industry standpoint, a common mistake is treating a 401(k) plan as if it were a generic brokerage account. Many 401(k) plans restrict certain actions (like frequent trading) and follow daily cutoffs or settlement rules. Therefore, participants should:
Another practical point: some participants expect that switching funds moves money instantly. Many plans process allocation changes using valuation timing rules. That means the shares may show up at the next valuation point or in a later statement cycle. If you’re making a change close to market close or during a time window, the portal might show “pending” or the change may appear after the next processing day.
Target date funds can be helpful for participants who prefer a “set it and adjust it automatically” style of allocation. However, it’s still important to check the target date series rules and whether the plan uses a particular glidepath. Even within target date categories, glidepaths and underlying fund expense structures can differ.
If your plan includes a stable value option, it can be relevant for participants managing near-term goals or those wanting reduced volatility. But you should also understand what stable value means within your plan context—how it is credited, how it behaves during plan turnover, and whether liquidity features differ from mutual funds.
For many employees, the single very economically meaningful aspect of a 401(k) is often not the interface—it is the employer match and vesting terms. Plans may offer a dollar-for-dollar match up to a certain percentage, a tiered formula, or no match depending on employer policy. Vesting can be immediate or graded over time.
Because matching and vesting are plan-specific, the very reliable method is to:
It’s common for participants to focus only on the “how much I contribute” portion. But the match is an additional “return” on your contribution. If you’re not capturing the match because your contribution rate is too low, you may be leaving free benefits on the table.
Still, you should consider your personal finances. If you have high-interest debt (such as certain credit card balances) or insufficient emergency savings, it may be rational to prioritize stabilization before maximizing retirement contributions. But if you can capture the employer match, it’s often a strong starting point.
Vesting impacts what you “keep” if you leave the company. The vesting schedule tells you whether employer contributions are fully owned immediately or earned over time. This is important even if you’re confident you’ll stay for years—people’s career paths change. Vesting information gives you clarity about what happens to employer money if you separate from employment.
Participants should also understand how match is calculated (for example, whether it’s based on a pre-tax deferral amount, after-tax amounts, or only certain contribution types). Some match formulas exclude certain contributions. That’s why the plan documents matter.
Because you did not specify a city or country in the keywords provided, this article stays broadly applicable. Still, “local” context can matter in subtle ways—such as how payroll calendars vary across industries, how HR communications are delivered, and how benefits enrollment periods align with hiring cycles. In many workplaces, HR onboarding is structured around internal milestones (like a first-day benefits meeting), which can affect how soon a new employee is able to make elections and see contributions begin.
For employees who are new to workplace benefits, a practical approach is to treat your first 1–2 pay cycles as a “verification window”: confirm payroll deduction accuracy, confirm the contribution appears in your 401(k) account after the plan’s processing timeframe, and confirm your investment allocation election is implemented if the plan supports that election.
This verification approach is not about distrust—it’s about reducing uncertainty. Once you confirm the process works as intended, future changes are less stressful because you know how quickly and where information updates.
Also remember that some participants may receive new-hire setup instructions from HR that differ from what they later see in the recordkeeping portal. That mismatch can happen because HR and recordkeeping teams sometimes coordinate through different internal timelines. If you rely on the portals alone, you may miss important details that are communicated during HR onboarding (like deadlines, default options, or required forms).
Before any election or transaction can occur, certain conditions usually apply. While exact rules vary by plan and employer, the following requirements are common in 401(k) administration environments:
If you encounter issues, the fastest path is usually to compare (1) your payroll deductions, (2) the plan election record (what the election system says), and (3) the participant transaction history available through the recordkeeping portal. That triangulation reduces guesswork.
For instance, if your payroll shows the deduction taken from your paycheck, but Fidelity doesn’t show contributions posted yet, the most likely issue is timing—remittance posting windows or allocation processing schedules. But if payroll shows no deduction and Fidelity shows an election, then the issue might be a Paychex-side enrollment or effective date problem. If payroll deduction appears but Fidelity shows an incorrect allocation or wrong category (pre-tax vs Roth), then it may be an election configuration issue or a plan-specific classification rule.
The following supplemental section is designed to be practical and decision-oriented. It compares typical responsibilities and provides a workflow you can follow without relying on unverified claims.
| Area | Paychex (Typical Role) | Fidelity (Typical Role) | Participant Action to Confirm |
|---|---|---|---|
| Contribution elections | Helps ensure payroll deductions follow elections | Maintains account records and reflects allocations | Verify the contribution election date and allocation status in plan tools |
| Payroll timing | Processes deductions according to pay cycles | Records incoming contributions after remittance | Check payroll deduction vs. statement posting date |
| Account access and reporting | May support employer-side enrollment workflows | Provides statements, transaction history, and account tools | Confirm statement totals match internal payroll records |
| Loans/withdrawals (if allowed) | Employer coordination for eligibility/permissions | Process transactions under plan rules | Review plan restrictions and required forms/terms |
| Beneficiary updates | Employer may initiate onboarding steps | Records beneficiaries for the account | Confirm beneficiary is updated and saved successfully |
Source (industry and compliance context): For background on how 401(k) plans are governed and how participants can obtain reliable plan information, reference official US Department of Labor resources, including materials explaining ERISA-covered plan disclosures and participant rights (see US Department of Labor: “Employee Benefits Security Administration (EBSA)” resources). For general retirement plan fundamentals, the SEC and IRS provide complementary education materials on rollovers and retirement account rules. Exact plan terms must still be verified in your employer’s plan documents.
It’s worth emphasizing that the “chain of responsibility” matters for resolution. If you call with a question and the agent asks “is this a payroll issue or a recordkeeping issue?”, you’ll get faster help if you can answer based on your own evidence: what your paycheck shows, and what your recordkeeping portal shows. That helps the team route the issue to the correct internal system.
There’s a good reason these steps emphasize verification: the most common “participant regret” is not usually caused by someone choosing an overly risky fund—it’s caused by someone not realizing a contribution election took effect in a later period, or by someone assuming employer match always shows up immediately, or by someone overlooking a beneficiary designation update.
If you’re the type of participant who wants a repeatable routine, you can treat your 401(k) tasks as “quarterly habits”:
To make the “Paychex + Fidelity” concept concrete, it helps to look at a few common real-world scenarios and identify what typically causes confusion.
Possible reasons include an eligibility waiting period, a payroll cutoff issue (you enrolled after the deadline for that pay period), HR onboarding not yet completed in the payroll system, or an election that didn’t map correctly to payroll deductions. The fastest response is to check:
If your plan uses a “default enrollment” approach, it may automatically deduct once you become eligible. In that case, you might see contributions begin after the employer’s system completes enrollment onboarding. Patience is sometimes appropriate—but verification matters.
This is one of the most common timing misunderstandings. Payroll may deduct funds during the pay period, but remittance posting and investment allocation may happen on a schedule after payroll processing completes. You can treat this as a timing window problem unless there’s a larger discrepancy.
If the contributions do not post after multiple cycles beyond what the plan’s materials suggest, then it’s appropriate to contact support with the details. Bring evidence: paycheck date, deduction amount, and your election effective date.
Allocation changes often process based on valuation timing and settlement rules. Even when you submit a reallocation request successfully, the actual investment transfer might be reflected later. Some portals show “pending” status. Some only show the fully processed allocation after certain conditions occur.
Participants who plan long-term usually benefit from avoiding over-trading. The best allocation changes are the ones you can stick with, aligned with your time horizon and your risk tolerance.
Loan transactions (if allowed by your plan) often involve checks for eligibility and documentation, and sometimes employer coordination. The recordkeeping side may wait for required approvals or confirm outstanding plan rules before processing disbursement.
Because loans can involve compliance and administrative steps, the timeline may be longer than you’d expect for a simple allocation transfer. Plan communications often include loan processing guidance; reviewing that can reduce frustration.
Rollovers can be particularly sensitive because the rollover “source” might have different tax treatment, and the receiving plan might require specific instructions for how rollover money should be invested. If you don’t provide explicit instructions, some plans apply default investment rules.
When in doubt, you want the transaction history to show a clear lineage: contribution or rollover source → cash movement → investment allocation action → updated account balance. That’s what “reconciliation” looks like at the participant level.
For participants, the best way to manage delays is not to wait blindly. Instead, track what you can measure:
This makes you a more effective participant when you contact support. It also helps you avoid the “double-action” mistake—changing the same setting multiple times without understanding whether the original action has already been processed.
When employees feel uncertainty about “Paychex 401k Fidelity,” it often comes from asking questions too broadly. A more effective approach is to ask for the timeline and the controlling rule. Examples include:
In practice, service teams can answer these questions more precisely when the employee references the plan document’s sections and the relevant dates. If you can provide your pay dates, election date, and the amount you expected, you can often move from “we see a delay” to “here is what timeline applies to your case.”
It generally describes a combined benefits environment where an employer uses Paychex for HR/payroll administration and Fidelity provides retirement plan recordkeeping and participant account services. The exact experience depends on your specific plan documents.
Compare your payroll deduction on your pay statement to the contribution posting in your retirement account records after the plan’s processing timeframe. Also verify that the election’s effective date aligns with your payroll cutoff.
Usually, reallocation requests follow plan processing rules and may not be reflected fastly. Check your plan’s transfer timing guidance and your transaction history for confirmation.
Many plans allow changes, but they often require you to submit elections before a payroll cutoff and may limit how frequently changes can occur. Your SPD or plan notices will state the precise rules.
Common causes include eligibility waiting periods, missed cutoff dates, remittance schedules, or allocation processing time. The very reliable approach is to confirm your eligibility status and election effective date, then compare payroll deductions with account postings.
No. Employer match formulas, vesting schedules, and plan-specific transaction rules are defined by the employer’s plan documents and the plan’s governing processes. Fidelity recordkeeping typically implements those rules.
Use the plan’s Summary Plan Description (SPD), prospectus-like materials for investment options (where applicable), and any participant fee disclosure notices provided by your employer or plan administrator.
Yes. Rollovers involve documentation and processing steps that can have separate timelines from payroll-based contributions. Your plan’s rollover instructions and required forms govern the process.
Beneficiary updates are typically completed through the retirement plan recordkeeping account tools (the Fidelity side), while HR may coordinate enrollment workflows. Confirm that your change is saved and reflected in your account details.
First, re-check whether your request is still pending or already processed. Then verify the effective date and cutoff rules in your plan communications. If the request already went into effect, correcting may require another election change before the next cutoff. If you need urgent help, contact plan support with your dates and amounts.
A Paychex 401k Fidelity setup is top understood as an administrative partnership: payroll administration on one side and retirement recordkeeping on the other. When employees focus on timelines, election effective dates, plan eligibility conditions, and the match/vesting details specified in official documents, the account experience becomes predictable and actionable. Use the plan disclosures as your primary source, validate the first few contribution cycles, and ask targeted questions tied to specific plan rules. That combination is the very reliable path to confident 401(k) participation.
Ultimately, the best participant mindset is to treat your 401(k) as a system of coordinated steps rather than a single button. The “Paychex + Fidelity” naming may feel like a single entity, but in practice it’s a chain: you make an election → payroll applies deductions → contributions are remitted → recordkeeping posts and invests → statements reflect activity. Once you know where each step lives and what it depends on, most surprises become understandable—and most fixes become straightforward.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
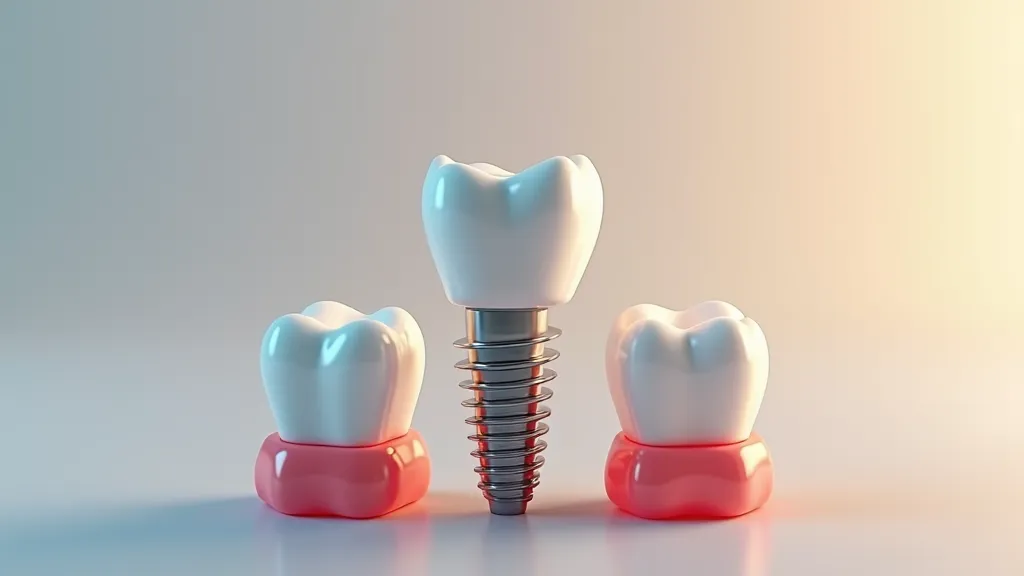
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
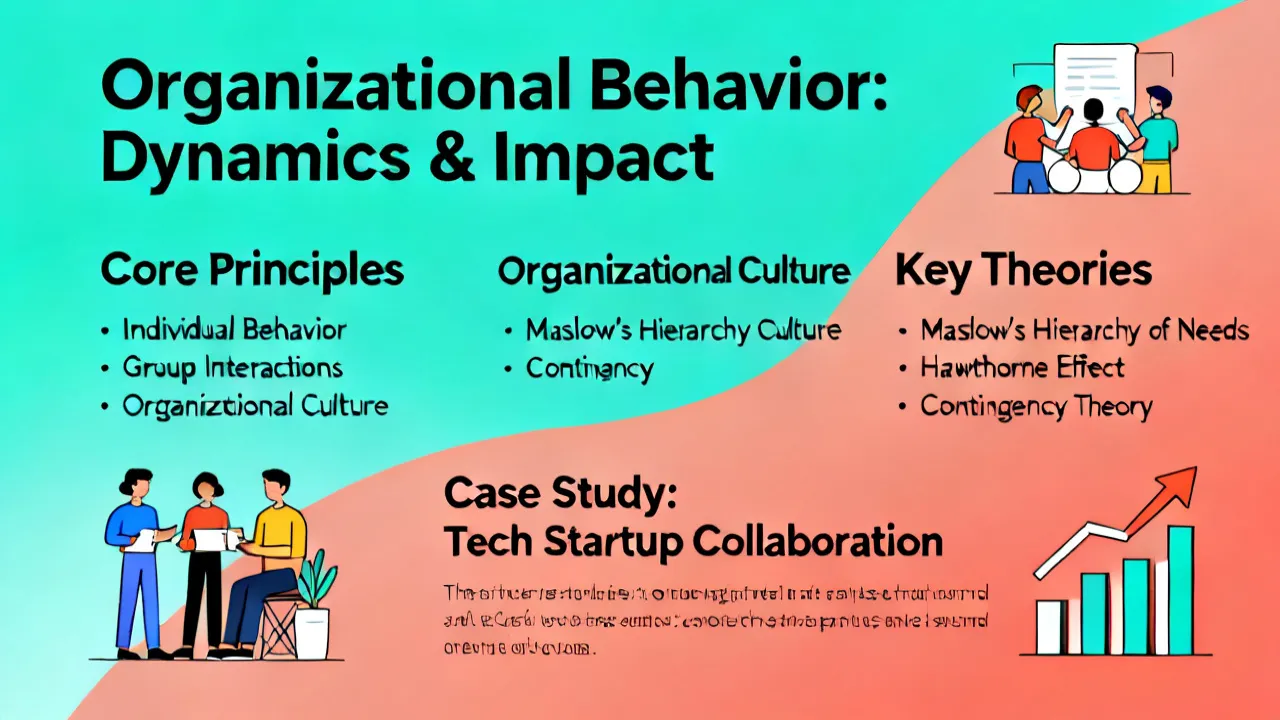
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.