This guide explains how to evaluate and implement Intuit Payroll for accurate, compliant paycheck processing. It provides objective background on payroll fundamentals, compliance considerations, and the practical factors businesses weigh when selecting payroll software—helping HR, finance, and owners align payroll workflows with local regulatory expectations.
Intuit Payroll is commonly evaluated by finance and HR teams because it centralizes payroll calculations, helps standardize pay runs, and supports payroll reporting workflows. This guide expands on how to assess Intuit Payroll against day-to-day needs—such as accurate employee compensation, timely payroll runs, audit-ready records, and practical usability for administrators—while keeping compliance, data protection, and internal controls in clear focus.
In many organizations, payroll is less about “just paying people” and more about managing a controlled process with clear inputs, consistent rules, and verifiable outputs. When payroll processing is fragmented across spreadsheets, emails, and manual journal entries, errors can multiply quietly—often surfacing only after employees ask questions, after accounting close, or during audits. A payroll platform like Intuit Payroll can reduce process variance by applying consistent logic to common payroll tasks and by providing a structured way to produce reports and documentation.
This expanded guide is written for decision-makers and implementers. It aims to help you evaluate whether Intuit Payroll supports a repeatable, reviewable, and defensible payroll process that fits your workforce profile, your pay policies, your internal controls, and your operational capacity.
Payroll touches legal compliance, employee trust, cash-flow planning, and financial reporting integrity. A system that is easy to run incorrectly is still a risk: incorrect withholding, wrong deduction treatment, incomplete recordkeeping, or incomplete reporting can lead to operational delays and potential liabilities. Conversely, a robust payroll platform is only beneficial if it fits your workforce structure, pay policies, administrative process, and reporting requirements.
When evaluating Intuit Payroll, teams typically examine the same high-level outcomes but may translate them into different internal checklists. Common dimensions include:
Ultimately, payroll decisions affect not only “how payroll is calculated,” but also how your organization proves that it calculated correctly—especially when something doesn’t go as planned.
From an industry perspective, payroll tools like Intuit Payroll are designed to streamline repetitive payroll tasks while improving consistency. While exact capabilities vary by configuration and plan, payroll software commonly supports:
For organizations that treat payroll as a controlled business process, the key question is not whether payroll software can calculate pay, but whether it supports repeatable, reviewable, and defensible payroll runs. “Defensible” means you can answer: what data was used, what rules applied, who approved the run, what changes were made, and how the organization produced the final payroll totals.
Payroll compliance depends on jurisdiction, business type, employment classification, benefit design, and how payroll is reported and remitted. Because requirements vary widely, the safest approach is to rely on official guidance from relevant government agencies and to validate settings before each payroll cycle.
As an objective baseline, businesses should consider how payroll systems address these core compliance areas. Even if a payroll system performs calculations, your organization still owns correct configuration, correct classification, correct recordkeeping, and correct remittance practices where applicable:
For the most current compliance requirements, organizations generally consult official resources such as tax authority publications and employment regulation guidance. In the United States, for example, the Internal Revenue Service (IRS) and the Department of Labor (DOL) provide authoritative references for payroll-related obligations and recordkeeping. (See “Sources” near the end of this article.)
Important note for evaluators: compliance is not merely a software feature. Payroll software helps, but compliance outcome depends on your configuration quality, ongoing administrative discipline, and the correctness of your employment data.
Payroll platforms can be especially helpful for businesses that need:
In small and mid-sized organizations, the “human workflow” often matters as much as the software. If the payroll person is the single reviewer, the platform should still allow for structured checkpoints—such as verifying employee pay settings prior to processing, reviewing exception lists, and preserving evidence for what was changed and why.
In larger organizations, operational fit also means the system should support standard operating procedures (SOPs), approvals, and reporting handoffs. If payroll results must be reconciled in the general ledger, the platform should provide outputs that can be mapped reliably to accounting structures.
From an operations and governance standpoint, the strongest payroll implementation is the one that balances control with usability. Overly complex setups—especially when the business rarely uses certain features—can create “configuration debt.” That debt shows up when administrators stop trusting outputs because too many rules are unclear, or because too few people understand the system sufficiently to manage exceptions confidently.
A practical mindset when adopting Intuit Payroll is to build a payroll configuration that supports your most common scenarios reliably, then incrementally extend capabilities only when needed. Teams often adopt the following approach:
When your implementation follows this discipline, payroll software becomes a tool that reinforces internal controls rather than something that creates a new source of confusion.
You noted “price information” and “supplier details,” but no explicit price amount or supplier entity was provided in the prompt. Because payroll pricing can vary by features, number of employees, plan structure, and sometimes by jurisdiction, the responsible approach is to treat pricing as plan-dependent and to confirm it directly with the vendor’s current published information or a reseller/quote process.
When requesting a quote or reviewing pricing for Intuit Payroll, teams generally ask questions that help them compare “apples to apples,” including:
In other words, “price” is not just a number. It’s the total cost of running compliant payroll reliably: license fees plus implementation effort plus the internal time spent on validation, exception handling, and reconciliation.
The following table is designed as a supplement for decision-making. It compares common evaluation dimensions rather than claiming a universal top option for every organization. Use it to structure internal questions for Intuit Payroll and competing vendors.
| Evaluation Dimension | What to Check in Intuit Payroll | Why It Matters |
|---|---|---|
| Setup and configuration | Employee profiles, pay schedules, deductions, tax settings, and any supported payroll calendars | Reduces errors and prevents inconsistent withholding or incorrect deduction application |
| Payroll run workflow | Draft/review steps, correction processes, and approval structure | Supports internal controls and auditability through consistent workflow evidence |
| Reporting outputs | Payroll reports for accounting close and recordkeeping; clarity of totals and mappings | Improves financial reconciliation and documentation readiness |
| Administrative usability | How quickly payroll staff can process standard runs and exceptions; clarity of system prompts and warnings | Lower operational risk from user error and faster issue resolution |
| Data access and permissions | Role-based access; ability to restrict payroll changes; evidence of an audit trail | Helps protect sensitive employee data and enforces separation of duties |
| Integration readiness | How payroll results align with bookkeeping and HR processes; export/import options | Reduces manual re-entry and reconciliation friction; improves month-end efficiency |
| Exception handling | Support for retro pay, off-cycle adjustments, terminations, and deduction changes | Ensures payroll correctness during real-world events, not only standard cycles |
| Document retention | Retention time, export formats, and availability of prior payroll records | Supports audits, employee disputes, and internal recordkeeping |
Because payroll compliance and recordkeeping requirements are jurisdiction-specific, it’s important to rely on primary sources. The following are commonly referenced starting points for payroll and employer obligations:
For authoritative research and compliance detail, consult the official websites of these agencies and any local tax authorities applicable to your business. Also consider consulting a qualified payroll compliance professional or accountant for interpretations specific to your company’s circumstances.
Below is a practical, expanded guide for adopting Intuit Payroll. This is written as a general method—always verify your configuration against your jurisdiction and business policies. The steps emphasize controls, validation, and realistic workflow planning rather than only technical setup.
Identify who will be processed in payroll: employees, changes in headcount, and any special cases (e.g., new hires, terminated employees, retroactive adjustments, multiple job assignments where relevant). Condition/Requirement: workforce data must be accurate before pay run input, including start dates, employment status, pay rate effective dates, and deduction eligibility.
Practical additions for evaluators: validate that HR and payroll share a clear source-of-truth for employee demographics (address, filing status details if applicable, exemptions), and confirm how the organization handles mid-cycle changes (for example, when an employee’s pay rate changes mid-pay period).
Document pay schedules (weekly/biweekly/monthly), pay rates, overtime rules (where applicable), deduction categories, and any company-specific rules. Condition/Requirement: payroll rules should be reviewed internally to ensure they match HR policy, employment agreements, collective bargaining agreements (if any), and relevant labor regulations.
Practical additions: define a “rules inventory” that includes the current state of your payroll logic (earnings types, deduction types, proration rules, and any special calculation behaviors). Confirm that the payroll system’s configuration model can represent your rules without excessive manual intervention.
Enter or import employee information, confirm tax-related settings, and validate deduction details. Condition/Requirement: implement a checklist for the payroll administrator to confirm critical fields before processing. This should include effective dates for rates and deductions and confirmation that the employee is flagged for inclusion in the upcoming run.
Practical additions: determine whether your organization uses role-based access for profile changes. Consider limiting the ability to change tax settings to payroll administrators, while allowing HR to update job-related information under controlled permissions.
If supported, run a draft cycle or test scenario using representative employee records. Condition/Requirement: compare calculated results to your expected baseline (e.g., historical pay stubs, internal spreadsheets, policy-based calculations, or a prior payroll system’s outputs). Use at least one scenario that exercises complexity—partial periods, pay rate changes, or a deduction change within the period.
Practical additions: validate that the system produces the reports you need for accounting reconciliation (earnings totals, tax liabilities, net pay, deduction totals). Validate report totals match the outputs employees would see (where employee pay statements are generated).
Assign responsibility for reviewing totals, deductions, and exceptions. Condition/Requirement: establish a separation-of-duties approach where possible (e.g., preparer vs. reviewer). Ensure the system’s workflow supports capturing evidence of review.
Practical additions: define “stop conditions,” such as if a pay run includes employees not expected, if deduction totals deviate from expected thresholds, or if there are mismatched effective dates. Ensure reviewers know what documents or system screens they must check before approval.
Process payroll according to the company’s timeline. Condition/Requirement: confirm remittance or submission workflows (if applicable) and ensure the timing aligns with company cash-flow planning and statutory deadlines.
Practical additions: schedule a post-run review meeting for the first one or two pay cycles to capture lessons learned and refine SOPs. Consider establishing a “rapid correction window” process so that if corrections are needed, they can be handled without delaying employee communication.
Verify that payroll expenses, liability accounts, and net pay align with accounting entries or close procedures. Condition/Requirement: maintain consistent mapping for reconciliation to avoid recurring month-end adjustments.
Practical additions: verify that the payroll reports can be reconciled to general ledger accounts in a repeatable way. If payroll exports are used, ensure the export format is consistent and that any transformations are documented. Confirm whether the organization posts payroll as a single journal entry or multiple entries (earnings, taxes, deductions) and ensure payroll outputs support that structure.
Provide training on common issues: corrected hours, retro pay, deduction changes, and employee termination timing. Condition/Requirement: keep a short internal SOP so exceptions are handled consistently.
Practical additions: build a library of “what to do when…” scenarios, including how to process corrections, how to communicate impacts to employees, how to update records for future pay runs, and how to document approvals for audit readiness.
After rollout, set a cadence to review payroll settings and user access. Condition/Requirement: verify that changes to employee policy (benefits, deductions, pay rules) are reflected in the payroll configuration before they affect payroll.
Practical additions: periodically test restoration/export capabilities of payroll records (in case you need to retrieve historical information). Also confirm that permissions remain current as staff roles change, and that privileged access is reviewed at least quarterly or per your internal policy.
Even with a strong platform, accuracy is largely a system design problem: inputs, workflows, approvals, and monitoring. Here are practices industry teams use to reduce payroll errors. Many of these practices apply regardless of whether you use Intuit Payroll or another tool.
One effective approach is to treat payroll like a “controlled release process.” Instead of relying on a single human memory for what’s correct, you rely on checklists, roles, and system outputs that can be compared against expected patterns.
Payroll exceptions are where systems either shine or create operational stress. When evaluating Intuit Payroll, test your ability to manage these scenarios before final rollout. Even if you don’t expect frequent exceptions, you should know exactly how the process works when they occur.
Common exception types include:
To evaluate fit, create a scenario checklist and run it in a test environment (or in draft mode). Have a payroll administrator, and optionally an accounting reviewer, walk through the workflow exactly as they would in production. The goal is to confirm that:
Intuit Payroll is used to process employee payroll cycles—calculating earnings, applying deductions, and generating payroll documentation and reports to support internal and compliance-related recordkeeping workflows. In practice, it helps you run pay cycles in a structured way, produce standard reporting outputs, and manage payroll administration tasks that would otherwise be handled manually.
Use a pre-run checklist covering employee pay rates, pay schedules, deduction categories, tax-related settings, and employment status. When possible, validate outputs against a known reference such as prior pay stubs, your internal payroll policy, or calculations from historical records. For reliability, confirm effective dates and inclusion rules, not just the final totals.
It can reduce mistakes by standardizing calculations and supporting consistent workflows. However, accuracy still depends on correct inputs, thoughtful configuration, internal review steps, and careful handling of exceptions. In other words, software reduces risk but doesn’t eliminate operational responsibility.
Common controls include role-based access, approval workflows for pay runs and adjustments, audit trail review, and reconciliation procedures that verify payroll totals align with accounting close. Additionally, define stop conditions and exception approval requirements for retro pay and off-cycle corrections.
Payroll systems typically depend on HR inputs such as hire dates, termination dates, pay rates, and employee status. They do not eliminate HR responsibilities; rather, they operationalize those decisions in pay processing. To reduce payroll errors, HR and payroll should coordinate on a shared workflow for updates and effective dates.
Retroactive changes require careful documentation and consistent processing rules. Establish a clear internal procedure for approval, re-calculation, and communication so employees and accounting records remain aligned. The main risks with retro changes are unintended duplicates, inconsistent effective dates, and missing audit evidence.
Confirm what’s included in the plan (pay runs, reporting, employee documentation, and any self-service features), how employee count affects pricing, any onboarding/setup costs, support scope, and whether certain features require additional fees. Also ask about export capabilities and data retention terms, since those can affect downstream accounting and audit needs.
Use official government guidance relevant to your jurisdiction for tax withholding, reporting, and recordkeeping. For the most reliable interpretation, consult qualified professionals such as accountants or payroll compliance specialists. If you have multiple jurisdictions, confirm that you have a process for jurisdiction-specific settings and updates.
Beyond standard pay runs, test at least one scenario that includes: a pay rate change effective mid-cycle, a new hire starting near a cutoff, a termination effective near cutoff, a deduction change that starts or stops within the period, and a retro correction. Also test your ability to produce the reports you need for reconciliation and internal review.
Audit readiness comes from consistent evidence: who ran payroll, what data was used, what changes were made, and what the resulting totals were. Use the system’s reporting and audit trail features, maintain standardized reconciliation documentation, and ensure approvals are captured according to your internal SOP.
Choosing Intuit Payroll is best approached as a governance decision: ensure that employee data, pay rules, and payroll workflows are accurate, reviewable, and aligned with compliance obligations. When implemented with disciplined internal controls—clear checklists, defined approval steps, role-based access, reconciliation routines, and structured exception handling—payroll software becomes a practical foundation for dependable paycheck processing and audit-ready documentation.
Finally, remember that payroll is not only a technical system but a recurring operational process. The most reliable implementations treat payroll as something you maintain over time: you validate settings before each cycle, update configurations when HR policy changes, review permissions, and continuously refine your SOP based on exception patterns.
If you share your business size, pay frequency, typical deductions, employment categories (and your jurisdiction), a tailored evaluation checklist for Intuit Payroll can be mapped to your exact workflows—so you test the right scenarios and adopt controls that match your risk profile.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
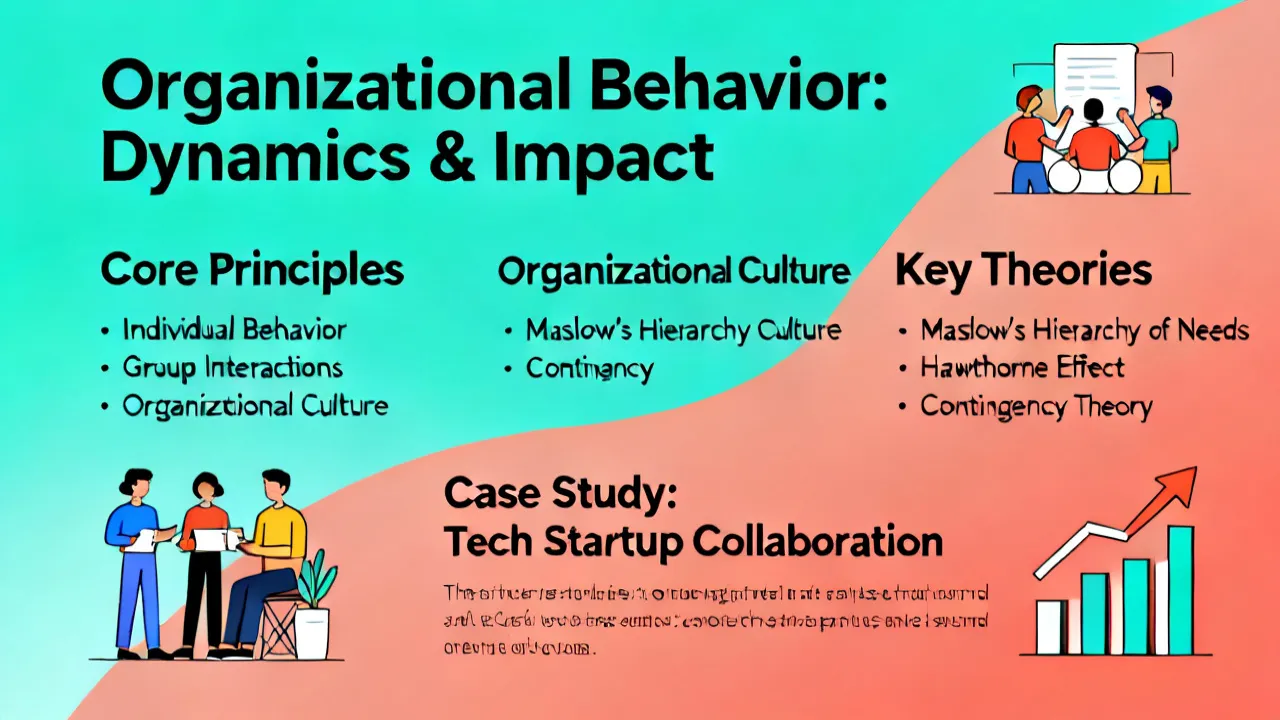
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
