Square Payroll 1099 guidance helps businesses correctly handle independent-contractor reporting. This guide explains what “Square Payroll 1099” typically refers to in practice, the compliance rationale behind Form 1099-NEC reporting, and how to coordinate contractor records, payment documentation, and deadlines. It also outlines decision conditions and a practical checklist for reducing errors without relying on unsupported claims.
Square Payroll 1099 guidance is about correctly preparing and managing information returns for independent contractors—especially when your payments may trigger IRS reporting obligations. From an industry-expert perspective, the very important step is ensuring that contractor identity, payment totals, and filing timelines are consistently maintained so your 1099-NEC process is accurate, auditable, and defensible during reviews. In practice, this means treating “1099 reporting” as a disciplined operational workflow, not as a one-time export you run at year-end.
When organizations treat the process like operations—tight onboarding, correct classification, accurate W-9 data capture, consistent payment coding, mid-year hygiene checks, and documented reconciliation—they drastically reduce the kinds of failures that cause corrections, recipient confusion, and avoidable compliance exposure. Tools can help, but only strong data governance makes the output meaningful. That distinction—between “software-generated outputs” and “compliance-grade inputs”—is where most real-world results come from.
In common business practice, “Square Payroll 1099” is used as shorthand for the workflow of generating or supporting the preparation of IRS information returns—very often Form 1099-NEC—for payments made to non-employees. While many companies use payroll-style systems to manage payments, the legal and tax categorization behind “1099” reporting is still grounded in IRS rules: whether someone is truly an independent contractor versus an employee.
From a compliance standpoint, the label matters less than the substance: you must determine worker classification, maintain correct payer/payee records, and produce accurate totals for reporting. Any tool—whether a payroll platform, payments platform, or accounting system—only helps if your underlying data is correct. If your internal contractor records are incomplete or your payout coding is inconsistent, the system may still produce a clean-looking report that is wrong in substance—creating downstream issues.
In other words: “Square Payroll 1099” usually refers to a combination of (1) payment capture, (2) contractor record maintenance, (3) export or reporting logic that calculates totals, and (4) year-end reconciliation and filing readiness. If any of those components are missing or unreliable, your 1099 outcomes can be compromised.
Form 1099-NEC is generally used to report nonemployee compensation to the IRS. The purpose is information matching: the IRS receives reporting from payers and compares it with what recipients report on their own tax returns. For businesses, this increases the need for disciplined recordkeeping and accurate reporting scope decisions.
It is also important to understand that 1099-NEC reporting is not solely about IRS filing mechanics. Recipient reporting matters too. Many contractors plan personal tax filings based on the statements they receive. If you issue incorrect forms, contractors can experience delays, amended filings, or questions from tax preparers. Even when the tax outcome ultimately differs for technical reasons, the administrative burden often falls on the payer.
To avoid common pitfalls, organizations typically focus on three pillars:
For authoritative tax requirements, businesses should reference IRS guidance on Form 1099-NEC and independent contractor versus employee considerations. The IRS is the primary source for filing instructions, thresholds, and deadlines (see IRS Form 1099-NEC instructions and relevant IRS guidance on worker classification).
From an internal-control perspective, the IRS instructions function as both a “rulebook” and a “standard.” If you align your workflows to those rules—especially the definitional rules for what is reportable and how to treat exceptions—your reporting is more likely to withstand scrutiny. If you deviate without documented rationale, you may be forced into reactive corrections later.
Even when a system is described as “payroll,” 1099 reporting is not just about running a report—it’s about the governance of contract records and payment documentation. An experienced operations or finance leader typically asks:
In practice, systems often provide exporting, reporting, or data-mapping features. However, the final compliance outcome still depends on your inputs: correct tax details, correct payment totals, and correct determination of reporting scope. A common internal failure is assuming that the system’s “1099 report” feature is automatically aligned with your specific business rules.
For example, some payment platforms can capture various transaction types (service fees, tips, reimbursements, discounts, partial refunds). Not all of those items necessarily belong in nonemployee compensation. Your mapping logic must reflect IRS expectations and your business’s actual contracts and payment terms. That mapping logic needs to be repeatable and documented, not improvised at year-end.
Industry teams see recurring error patterns that do not require dramatic assumptions—just everyday breakdowns in process:
Mitigating these risks is less about “finding the right button” and more about building a reliable workflow between onboarding, payment processing, and year-end reporting. Think of it as building a chain of custody for data: where it originates, how it is validated, how it is transformed, and how it is finally filed.
From a defensibility standpoint, you want to be able to answer, for any contractor on your list: (1) why they are included, (2) what data you used, (3) how totals were calculated, and (4) how you handled exceptions. If your business can answer those questions quickly and consistently, you are substantially more prepared for contractor inquiries, tax advisor review, or potential issues flagged in IRS matching processes.
An effective Square Payroll 1099 workflow usually includes a tight loop: onboarding + verification + payment capture + reconciliation + final filing support + correction handling. Below is a pragmatic inverted-pyramid approach: the very critical activities first.
It can be helpful to visualize 1099 reporting as a sequence of gates. You do not want to pass a contractor into the “reportable set” unless they pass the gates for classification, identity documentation, and inclusion rules. You do not want to pass payments into totals unless they pass the gates for correct category mapping and reconciliation. You do not want to finalize filings unless the output passes a gate for completeness and reasonableness checks.
Before you even think about the form, confirm whether the worker is an independent contractor for your purposes. Classification is fact-specific and depends on the relationship, control, and economic realities—not merely the wording of a contract. A contract can be helpful evidence, but it rarely substitutes for actual operational behavior.
In regulated business environments, teams often keep an internal classification memo and use a standardized onboarding questionnaire. This reduces later disagreements about why a worker was (or wasn’t) included in a 1099 reporting run. It also reduces the risk that someone will “fix” classification late in the year without documentation of the reason.
Common internal-control best practices include:
From a workflow standpoint, classification gatekeeping should happen before major payments occur. Waiting until year-end is risky because correcting classification and reclassifying payments late can require a cascading set of changes—payments, records, potential tax treatment differences, and potentially amended filings if reporting has already been submitted.
For contractor reporting, businesses typically collect a completed W-9 form. The operational goal is data certainty: legal name, business name (if applicable), address, and TIN. A common top practice is to validate that the tax details are complete and match what the contractor provides.
Where mismatches occur, teams coordinate with tax advisors and follow IRS guidance regarding corrections and potential backup withholding requirements. This keeps the year-end process from becoming reactive.
Beyond “having a W-9,” data verification should include quality control steps such as:
Some businesses also implement a “TIN check” process through professional tools or IRS-recommended validation approaches. If you do not have access to advanced validation tooling, you can still improve reliability by enforcing strong form completion standards and requiring review by a second person before approving the contractor in your reporting system.
In addition, if you allow contractors to self-update their profile details through a portal, ensure your process keeps an auditable trail. If a contractor updates a profile close to year-end, you want to know what changed, when it changed, and which version of data was used to calculate totals.
Once classification and tax details are set, the next question is how payments flow into your reporting dataset. For example:
From an accounting-control standpoint, reconciliation is where errors are caught early. A strong process compares totals generated by the platform against your bookkeeping records or payout ledgers. When differences appear, the team documents the reason and corrects the underlying data.
A robust reconciliation approach usually includes the following:
It is easy to get trapped by “the system says” totals. Instead, build a simple mapping document that explains how each payment type is treated. For example, your mapping might say: “Service fees to contractors are included; reimbursement of approved expenses is excluded; third-party pass-through amounts are excluded; tips follow the contractor/treatment rules under our agreements and are categorized accordingly.” That mapping document becomes the foundation for stable and consistent reporting.
If you cannot map the payment purpose with reasonable certainty, that is a signal to pause and research or seek guidance before closing the 1099 data set. Many reporting errors are not purely technical—they are definition errors about what the payment represents.
Even with strong controls, errors can happen. Prepare for:
This “readiness” mindset reduces disruption in February and March—the months when many finance departments experience a spike in questions and adjustments. A common mistake is not assigning responsibility: if no one owns the correction process, error resolution can become chaotic.
Operationally, you want a correction playbook that includes:
Defensibility is not only about being correct the first time; it is also about being organized when you are not.
Use the steps below as a practical workflow. This is not legal advice, but it reflects standard internal-control logic used in finance operations:
Many organizations also add a “mid-year” checklist because year-end cleanup is costly. A mid-year hygiene check gives you time to request updated W-9s and correct mapping problems while contractors are still actively engaged and reachable.
The table below compares common approaches businesses use when implementing Square Payroll 1099 workflows. It also includes sources and conditions/requirements. No links are provided.
| Approach | What You Do | Source of Rules / Reference | Conditions / Requirements |
|---|---|---|---|
| System-assisted reporting workflow | Use Square Payroll-related exports or data outputs to help prepare 1099 reporting inputs, then reconcile with your accounting records. | IRS Form 1099-NEC instructions; IRS instructions for recipient and filing procedures; IRS guidance on backup withholding and TIN issues (as applicable). | Worker classification is correct; W-9 data is complete; payment mapping aligns with reporting scope; reconciliation is performed before submission. |
| Accounting-led preparation | Generate 1099 totals from accounting systems (GL/payout ledger), then use payroll/payments platforms only for supplemental data. | IRS Form 1099-NEC instructions; general IRS reporting requirements for information returns. | Accounting categorization is stable; contractor accounts are tracked separately; adjustments/refunds are properly netted according to policy and IRS rules. |
| Tax advisor review (recommended for complex cases) | Provide prepared contractor lists, payment totals, and W-9 data for professional review prior to filing. | IRS guidance; professional top practices for information return accuracy and corrections. | Timely submission of materials; availability of documentation for classification and payment disputes; documented rationale for inclusions/exclusions. |
| Hybrid workflow (often best for growing businesses) | Use platform exports to accelerate data gathering, but finalize totals and contractor eligibility from accounting and controlled mapping tables. | IRS Form 1099-NEC instructions; IRS general rules for information returns; documented internal mapping logic. | Strong reconciliation between platform and accounting; controlled master contractor data; clear responsibility for approvals and corrections. |
Below is a step-by-step guide intended to be operationally useful for finance, controller-level teams, and small-business owners who need a reliable year-end process.
To make this guide truly “implementable,” consider assigning roles: who owns classification, who owns W-9 collection, who owns payment mapping, and who signs off on final totals. Without role clarity, even the best checklists can fail because tasks get “absorbed” informally by whoever is available.
Before you submit any Square Payroll 1099-related reporting outputs, verify the following:
From a practical standpoint, many organizations create a “pre-filing binder” (digital or physical) for each reporting year. The binder can include spreadsheets showing reconciliation, a list of included contractors, copies or images of W-9 forms (or a secure index linking to them), and a log of adjustments/refunds mapping decisions.
Because “Square Payroll” workflows can touch multiple types of payments, it helps to consider typical mapping scenarios and how they influence 1099-NEC totals. While exact treatment can depend on facts and IRS instructions, the operational approach should be consistent and documented.
Here are examples of scenarios that often require careful categorization:
The key is not memorizing every edge case; it is building a mapping framework that your team can apply reliably. That framework should include a documented set of transaction codes and the rules for inclusion/exclusion. When mapping is inconsistent, your process becomes “personal” to individual operators, which increases error rates.
In real-world audits or reviews—whether informal internal reviews, external CPA reviews, or operational investigations prompted by a contractor inquiry—you will often be asked: “How did you get to that number?” A defensible 1099 process can answer that quickly.
To build that audit trail, consider capturing these artifacts:
This kind of audit trail is especially valuable when multiple staff members touch the workflow. It prevents the “institutional knowledge” problem where only one person remembers how the numbers were produced.
Below are common failure points that show up in 1099 problems across many small and mid-sized businesses. They are presented as operational categories rather than purely legal issues, because prevention is usually operational.
Prevention: enforce a workflow gate where no contractor is eligible for reportable payments until a W-9 is received and validated for completeness. For contractors who start mid-year, implement a process that prevents missing documents from becoming year-end problems.
Prevention: implement duplicate checks on onboarding (for example, matching on TIN or a combination of name/address). If your platform allows contractor re-creation, train users not to create new profiles when a contractor already exists.
Prevention: schedule reconciliation earlier than you think you need. Waiting until the last days of December or January compresses time and makes errors harder to fix.
Prevention: decide on a standard approach for payment year determination (based on payment date versus posting date) and document it. Ensure your extracted dataset uses that standard consistently.
Prevention: treat refunds and reversals as first-class transaction types in your mapping logic, not as “misc adjustments” discovered later. Make sure your extraction pulls both payments and related reversals.
Prevention: create a named correction owner (even if it is shared) and a procedure for responding to contractors and amending records when needed.
Many businesses only pay attention to 1099 reporting in late Q4, but a more reliable approach is to schedule recurring checks. A mid-year hygiene check addresses the practical risk that your W-9 collection and contractor data quality can degrade over time if no one reviews it.
A mid-year check might include:
While you can’t eliminate all issues, mid-year checks reduce the number of missing documents and mapping errors you must solve at year-end—dramatically reducing the chance of last-minute corrections.
Reasonableness checks are not about guessing; they are about using simple patterns to detect errors. These checks are especially useful when reconciling totals and validating the completeness of contractor lists.
Examples of reasonableness tests include:
When outliers are found, document the explanation and the evidence. If you cannot explain an outlier quickly, treat it as a potential error until proven otherwise.
No matter how well you prepare, sometimes errors are discovered. The question becomes: how quickly and effectively can you respond?
To handle corrections, develop a clear workflow for intake and resolution:
Also, communication matters. Contractors may be upset if they receive a statement that appears wrong. A calm, structured response that references the data trail (without overstepping into legal advice) helps reduce churn and protects your operational credibility.
It is typically used to support the workflow for preparing information returns for independent contractors—very commonly through the preparation of inputs for Form 1099-NEC reporting—by maintaining contractor payment and identity data in a payroll-adjacent process.
In other words, “Square Payroll 1099” is usually a practical way to describe how your system helps you assemble data needed for 1099 reporting. The compliance outcome depends on correct classification and accurate data, not on the label of the platform.
No. Tools can streamline data handling, but classification is ultimately a fact-based determination. Many businesses still consult IRS guidance and, when needed, a tax professional to confirm whether workers are independent contractors.
Even if a platform offers “contractor” tagging, classification must still reflect the reality of the working relationship. The system can store your decision; it cannot determine the facts.
Incomplete or inaccurate W-9 details can lead to corrections, recipient issues, and potential compliance consequences. Your process should include early collection, validation, and a correction plan. For specific outcomes, refer to IRS instructions and professional advice.
Operationally, you can reduce impact by tightening onboarding gates and implementing periodic validation checks. If errors are found, update the contractor master record promptly and re-run the totals to ensure you used the correct information.
Adjustments can change reportable totals depending on the transaction nature and applicable IRS instructions. A controlled reconciliation process helps you determine the correct net amounts and document the reasoning.
A practical approach is to ensure refunds and reversals are coded and mapped consistently so that they offset the correct contractor’s compensation amounts. Avoid handling refunds as ad-hoc items after totals are calculated.
Yes. Deadlines exist for both furnishing recipient statements and filing with the IRS. Business owners should rely on the current-year IRS instructions for exact dates and submission requirements.
Because deadlines shift by year and can differ based on filing methods, you should verify the current year’s instructions well in advance of finalizing totals.
It can prevent many avoidable mistakes, especially those related to missing contractors, mis-mapped transactions, and data-entry issues. However, reconciliation does not replace compliance checks—classification, completeness, and IRS-specific requirements still matter.
Reconciliation is a control mechanism. Like all controls, it is only effective when it is performed consistently and documented, with enough time to correct issues before submission.
Many small businesses can manage with strong internal controls and careful adherence to IRS instructions. Complex contractor relationships, unusual payment arrangements, or repeated discrepancies are reasonable triggers to involve a tax professional or CPA for review.
A tax advisor review can also improve confidence and reduce correction risk, especially if you have a history of data quality issues or complex reconciliation challenges.
For authoritative requirements and filing rules, consult the IRS official documentation including:
These are the very reliable references for thresholds, procedural steps, and compliance expectations. If your process deviates from the instructions, ensure your rationale is documented and reviewed by a qualified professional where appropriate.
The request did not specify a particular city or country. If you operate “nearby” within a specific jurisdiction, you should still rely on IRS guidance for federal reporting while considering any additional state or local requirements. Many regions require separate compliance steps for withholding or state-level information reporting; verify with your state’s revenue department or a qualified tax professional.
Even when federal reporting is the same across the United States, state reporting can be different in timing, thresholds, or data requirements. If you operate in multiple states, you may need additional mapping logic for state compliance.
A Square Payroll 1099 workflow is strongest when it behaves like a controlled process: accurate classification, clean contractor identity data, correct payment mapping, and reconciliation before filing. When those elements are in place, the year-end reporting becomes less stressful and more defensible—because the system’s outputs reflect reliable inputs and documented review, rather than last-minute corrections.
The most effective teams do not wait for February problems. They build gates in their onboarding, enforce W-9 validation, reconcile mid-year, and document their mapping logic. Then, when the 1099 run happens, it is primarily verification and final quality control—rather than discovery and firefighting.
Ultimately, “Square Payroll 1099” reporting is about reliability: reliability of worker records, reliability of payment totals, reliability of timelines, and reliability of the audit trail. If you approach it that way, you create a system that is accurate today and resilient next year.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
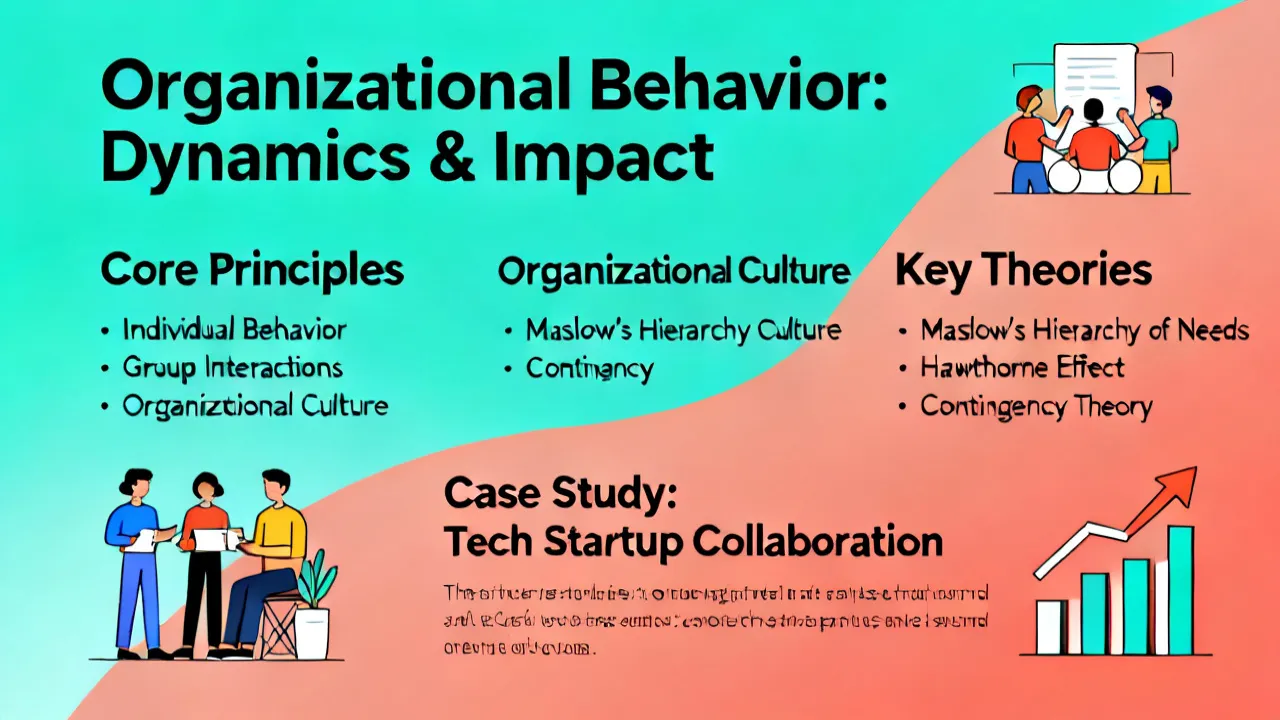
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
