This guide explains how to handle 1099 reporting when using Square Payroll for independent contractor payments. Background sections clarify what 1099 forms represent, how “independent contractor” differs from employee status, and why accurate categorization matters. It also outlines practical workflows, recordkeeping, and review conditions to reduce tax-time friction and improve compliance.
Square Payroll 1099 workflows are very reliable when you treat 1099 reporting as a structured process: (1) confirm contractor status, (2) collect required tax forms and addresses, (3) ensure payment data is correctly classified, (4) reconcile records before filing, and (5) maintain documentation in case of IRS questions. This approach supports accurate reporting for independent contractors and helps you avoid common mismatches between payment records and tax submissions.
In practical terms, “reliable” does not mean “automatic.” Instead, it means that if you follow a repeatable set of steps and keep a defensible trail of evidence, you can produce totals that align with your accounting, your payment exports, and your tax filings. For many organizations, the most costly problems come from small inconsistencies that stack up over time: a contractor’s name is spelled differently across systems; a tax ID is missing; a reimbursement is accidentally included as compensation; or payments are categorized using internal labels that do not map cleanly to the IRS’s instructions. A disciplined workflow prevents these issues from escalating.
Another useful way to think about it: 1099 reporting is less about “which button you press” and more about how you translate real-world payments into legally meaningful categories. When you do that translation carefully—using the IRS form instructions as the final authority—you create a reporting package that stands up to both internal review and external scrutiny.
When organizations pay independent contractors, they often need to report certain payments to the IRS. In practice, many businesses ask, “How does Square Payroll relate to 1099 reporting?” The very objective answer is that the 1099 process depends on your payment classification and the data you maintain—while tools (including payroll or contractor-payment workflows) can help organize payment records. Even when software streamlines reporting, your responsibility remains: correct identification of payees, correct tax identification numbers (when applicable), and consistent recordkeeping.
“Square Payroll 1099” is sometimes discussed in the context of platform capabilities, but compliance hinges on the underlying facts: who performed services, whether the payer had the right kind of control for employee classification, what was paid (compensation versus reimbursed costs), and what your records say. If the data you generate via Square-related workflows does not match how you classify payments in your accounting and how the IRS expects those categories to be treated, the output may still be incorrect even if the workflow seems straightforward.
Additionally, many businesses operate with multiple systems: payment processing, invoicing, accounting, and contractor onboarding. Each system may store slightly different versions of names, addresses, or payment categories. Over time, these differences can cause a “data drift” problem where your reports look correct internally but fail reconciliation when compared to another system or to IRS expectations. Treating 1099 reporting as a compliance workflow—centered on reconciliations and validation—reduces this drift.
Finally, a compliance-first approach is not just about avoiding penalties; it is about operational sanity. When year-end arrives, you will want a clear, auditable set of totals and supporting documents. If you collect contractor information and categorize payments consistently throughout the year, year-end becomes a verification step rather than a reconstruction project.
Before touching any system settings, define your payer/payee relationship. The IRS distinguishes employees from independent contractors based on the facts and circumstances (behavioral control, financial control, and relationship type). In other words, the classification is not simply a label you choose in your software. If you have any uncertainty, it is prudent to consult qualified tax counsel.
Many business owners intuitively associate “contractor” with a person who invoices rather than punches a clock. However, the IRS evaluation is not satisfied by that single factor. Instead, the classification depends on a multi-factor analysis. Even when someone looks like a contractor operationally—remote work, project-based engagement, independent scheduling—the IRS may still view them as an employee if the payer controls key aspects of the work in ways that align with employment.
This distinction matters because 1099 reporting generally applies to certain payments to independent contractors, while employee compensation is typically handled through W-2 reporting (and payroll tax processes). If a payer misclassifies a worker, the downstream reporting may be wrong as well.
From an operational standpoint, “1099 reporting” becomes relevant when you have independent contractor payments that meet the applicable reporting criteria. This is why “Square Payroll 1099” should be understood as a workflow concept: the software is a tool; the compliance requirement comes from how the payments were made and to whom.
In the real world, many organizations also run into hybrid arrangements. For example, a company may treat a person as an independent contractor for most services but bring them in for work that resembles employee control (e.g., requiring strict hours, enforcing detailed performance instructions, or integrating them as a core part of operations under management control). Those situations require careful analysis. If you are in doubt, document your reasoning and consider seeking advice before year-end so you can correct course if necessary.
Square Payroll is designed to support payroll-related tasks, including calculating and managing payments under certain structures. For contractor payments, businesses typically use the payment and recordkeeping portions of their systems (and may use different tools depending on whether they are paying W-2 employees or contractors). When users mention “Square Payroll 1099,” they are usually referring to the broader question of how to capture contractor payment totals, keep payee details current, and generate records that can support 1099 submissions.
To keep the process accurate, you should focus on three operational points:
To make this concrete, imagine your organization pays contractors through a mix of invoices, deposits, refunds, and adjustment entries. Square-related workflows might help you track payment activity, but you still need to determine which amounts are compensation and which amounts should not be included in the 1099 totals under the relevant form instructions.
Think of Square Payroll (and related data exports) as a “data capture and aggregation” layer. The compliance layer is your decision process about what counts as reportable payment and how that should map to IRS form categories. When you keep those roles clear, you avoid the common trap of treating exported numbers as automatically “tax-ready.” Instead, you treat them as a raw dataset that you validate against rules and accounting records.
1099 requirements can vary by form type and the nature of payments. For many businesses, the very common contractor reporting scenario involves Form 1099-NEC (Nonemployee Compensation). However, other 1099 categories exist depending on payment type. Because “Square Payroll 1099” is often used as shorthand, ensure you are generating the correct form category for the payments you made.
For official guidance, use IRS resources and the IRS instructions for each specific 1099 form. The IRS provides the legal framework and the form-specific requirements, including what information must be reported and how to correct errors.
It can be helpful to remember that “1099” is a family of forms, not a single form. Two businesses can both say “we file 1099s,” but one may file primarily 1099-NEC while another may file 1099-K (depending on payment card processing and merchant reporting rules), or other forms such as 1099-MISC for certain types of payments. Therefore, you should treat the “Square Payroll 1099” phrase as a starting point for asking: which specific form applies to each payment type you made?
In addition, some 1099 reporting obligations depend on thresholds and specific conditions. Even when the threshold is not met, your records should still be organized in case a later review suggests an adjustment. A clean dataset makes it easier to test threshold calculations and confirm whether you should have filed—or whether you should correct or void an output.
Another compliance principle: do not rely solely on memory or prior-year approaches. Rules and IRS procedures can change, and payment structures often evolve. A recurring workflow (collect info early, categorize payments correctly, reconcile totals, and document decisions) keeps you aligned even when specifics change.
The goal is not merely to “run a report.” The goal is to produce totals and payee information that are consistent across your accounting system, your payment records, and your tax submissions. The workflow below is designed for clarity and audit readiness.
One reason businesses struggle with 1099s is that reporting is typically done late in the year, when the team is busiest with year-end close. If you wait until the last weeks to think about contractor onboarding, payment tagging, and reconciliation, it becomes harder to correct errors. A practical workflow begins earlier and treats 1099 readiness as an ongoing quality control cycle rather than a year-end scramble.
Do not assume contractor status because someone invoices you or signs a service agreement. Review the relationship factors using IRS guidance. If your business has a mix of roles (employees, contractors, and potentially hybrid arrangements), create an internal checklist so the correct classification is reflected in your operational records.
In practice, classification confirmation is not just a tax question; it is an operational design question. Your onboarding and contracting process should align with your classification decisions. If you decide someone is a contractor, your engagement should avoid unnecessary controls that resemble employment. That means how you schedule work, how you set performance expectations, how you manage tools and methods, and how you structure the relationship. The goal is not to “game” the analysis but to align operations with your documented understanding.
If you are starting a new contractor program, create a standard intake form that prompts internal decision-makers to evaluate key factors: How much control do we exercise over daily work? Can the contractor generally choose how to perform tasks? Are we providing significant training or requiring adherence to detailed schedules? Is the work part of the company’s core operations in a way that suggests an employment relationship? Is the contract term and relationship type consistent with independent contracting?
If you find uncertainty, document that uncertainty and your decision rationale. While the IRS ultimately evaluates facts, documentation helps you show good-faith effort. It also helps you refine processes for future engagements so your classification analysis becomes more consistent over time.
Many 1099 workflows require payee information such as name and tax identification number. A common top practice is to collect tax documentation at onboarding (or before the first payment) and refresh it when needed. Keep a dated record of what you collected and when.
Most businesses require tax forms like a W-9 for contractors. The W-9 provides the tax identification number and legal name you will use for 1099 reporting. A recurring operational failure is collecting this information late (after a payment has already been made), which creates time pressure at year-end and increases the chance of incomplete fields.
Early collection also improves correction speed. If you notice an issue—such as a missing TIN, a mismatch between name and TIN, or a contractor using a business name instead of their legal name—you have time to request an updated form. If you discover the issue after multiple payments have already occurred, it may be more difficult to reconcile corrected reporting because you may have already generated partial totals or created records that require rework.
A strong process treats contractor onboarding as a compliance step. It means your onboarding checklist should include the required tax documentation, a clear record of the contractor’s legal identity, and a standardized approach to addresses and name formatting.
Address formatting matters, too. Even if you have the correct TIN, an address field that is consistently wrong may cause notices or delays in the processing chain. Your goal is to provide accurate and legible information.
Before generating anything for “Square Payroll 1099,” verify that your payments are recorded in the correct category. Misclassification is one of the very frequent causes of reporting issues—such as combining reimbursements with compensation, or including payments that should not be reported under the relevant form instructions.
From an accounting perspective, you want clear separation between:
To expand on this, reimbursements can be a particularly tricky area. Some reimbursements are legitimate pass-through expenses that may not be reportable depending on the situation and documentation. But if reimbursements are bundled with service fees in a way that makes it hard to distinguish amounts, your report may overstate reportable compensation. One practical strategy is to enforce a policy for contractors: reimbursements must be documented with receipts or a clearly labeled expense category, and they should be recorded in a different accounting classification than service compensation.
Another issue is “adjustments.” Payments can be partially reversed, corrected, or reconciled after initial processing. For example, if you issued a payment and later corrected it due to an invoice dispute, your accounting system might include both the original entry and a later adjustment entry. Your 1099 totals should reflect the final net amount that is reportable. If your export simply totals gross payments without accounting for adjustments, you may produce incorrect figures.
It’s also important to ensure that payment dates used for 1099 reporting align with the IRS requirements for when payments are treated as made (depending on the applicable accounting method and form instructions). Many businesses use cash basis or accrual basis approaches consistent with their tax method, but the internal data fields should be mapped appropriately.
Even with software assistance, you should reconcile. Compare totals per payee and total compensation amounts in your payment exports to general ledger activity or accounting summaries. If there’s a mismatch, resolve it before filing.
Reconciliation is where “workflow reliability” becomes real. Software may export totals correctly within its own universe, but your compliance requirement spans across systems. Therefore, reconciliation is not optional if you want to reduce risk.
A disciplined reconciliation approach usually includes:
When a mismatch appears, treat it as a debugging exercise rather than a surprise. Common causes include:
As you resolve mismatches, document your findings. Even if the IRS never asks, internal documentation supports process improvement. If you do this year after year, you gradually reduce the likelihood of the same issue recurring.
Accuracy matters for each recipient. Review recipient details for typos, formatting issues, and missing information. Inconsistency between the payee name/TIN combination and IRS records can create processing delays or mismatches.
In practical operations, a “good enough” approach is not enough: you want a defensible review trail—who checked what, and when.
Consistency review typically includes:
Many businesses accidentally create duplicate contractor profiles because onboarding data came from different sources (an invoice platform, an email signature, a contract portal, or a payment system). To prevent this, consider enforcing a master payee record policy: one legal identity per contractor, and all payments should reference that identity.
Another layer is the “process evidence” aspect. If you can show that you performed reasonable checks—such as reviewing W-9 information and reconciling payment totals—your position improves if you encounter IRS questions or notices. In other words, this step reduces not just numeric errors but also process risk.
After reconciliation, generate the filing-ready output and keep a complete backup package: exported reports, reconciliation worksheets, contracts (if relevant), and payee information you collected. If you ever need to correct a submission, having a clear record reduces the time spent reconstructing what happened.
A practical recordkeeping package often includes:
Also consider access control and version control. If multiple team members can update contractor data or payment categories, ensure you can identify what changed and when. Even simple controls—like using a single owner for year-end exports—reduce confusion.
If a correction is needed after filing, you will need to trace back to the numbers used in the original submission and identify what was wrong. Having a coherent audit package makes corrections faster and reduces the chance of introducing new errors during the correction process.
This table summarizes common ways businesses approach “Square Payroll 1099” workflows. It is a practical comparison rather than a substitute for IRS advice or professional tax counsel.
| Approach | Primary Source of Truth | Step-by-Step Guide (Condensed) | Conditions / Requirements |
|---|---|---|---|
| Software-assisted contractor reporting workflow | Exported payment records and internal contractor/payee master data | 1) Confirm contractor classification. 2) Verify payee info fields. 3) Export payment totals per payee. 4) Reconcile with accounting records. 5) Generate the appropriate 1099 category output. 6) Perform final review before filing. | Payees must be correctly classified; payment totals must exclude non-reportable items per form instructions; payee details must be consistent. |
| Accounting-led reconciliation with software as a data collector | General ledger and subledger (payee-level tracking) | 1) Pull payee totals from the ledger. 2) Compare against platform exports. 3) Identify and correct discrepancies. 4) Map totals to the correct 1099 form category. 5) Validate that recipient details meet required fields. | Requires disciplined mapping between software transaction categories and ledger categories. |
| Manual spreadsheet process for smaller payee counts | Contracts/invoices and payment history | 1) Create a payee list. 2) Document compensation amounts per payee. 3) Validate payee names and tax IDs. 4) Confirm totals with invoices and bank statements. 5) Prepare form data following IRS instructions. | Only feasible for limited payees; higher risk of transcription errors; must maintain strong audit trails. |
Beyond these points, several additional failure modes show up frequently:
From an industry perspective, “compliance-by-software” is rarely sufficient. The very resilient approach blends systems with a disciplined review cycle:
1) Build a timeline. Set an internal calendar for payee onboarding, mid-year checks, and year-end reconciliation. Many businesses miss the “middle” work and only discover issues when the deadline is near.
A good timeline often includes at least three checkpoints: (a) early-year onboarding and tax form collection for new contractors, (b) mid-year data quality review to ensure payee records are complete and payments are being categorized correctly, and (c) year-end reconciliation and filing preparation. Mid-year review is especially valuable for organizations with contractor churn or seasonal contractors.
2) Standardize your payee master record. Maintain consistent formatting for legal names and addresses as much as feasible. Consistency reduces friction across exports and forms.
Standardization is not only about formatting—it is also about governance. If your organization updates payee records, define who can update them, what fields can be changed after onboarding, and how to handle corrections. Ideally, changes should be supported by updated tax forms and documented with the date of update.
3) Use reconciliations as quality control. Treat reconciliation as a control, not an afterthought. A 30–60 minute reconciliation step can prevent larger corrective projects later.
Quality control benefits from sampling as well as full reconciliation. For very large contractor networks, you may not reconcile every item in exhaustive detail during early checkpoints, but you can reconcile samples to validate that your categorization mapping is working. Then at year-end, you perform a comprehensive reconciliation before filing.
4) Document policy decisions. If your team uses a policy for how reimbursements are handled or which payment types are excluded, document it. When questions arise, you can show your rationale.
Documentation also makes training easier. New staff members can follow the documented approach rather than learning informally. Over time, this reduces inconsistency across years and across team members.
5) Separate duties where possible. If your workflow allows it, separate the person who exports data, the person who reconciles, and the person who approves final filing. Even simple separation reduces the chance of errors going unnoticed.
For example, one person might prepare the export and generate a draft dataset; another person might reconcile totals to the ledger and review payee details; a third person might approve final submission. You do not always need a large team, but where roles can be separated, you improve accuracy and accountability.
6) Maintain a “correction playbook.” Errors happen. Instead of improvising at the last minute, predefine steps for common issues: missing TIN, name/TIN mismatch, incorrect total, duplicate payee, or wrong form category. Your playbook should tell you who to contact (internally and externally), what evidence to collect, and how to prepare an amended submission.
A playbook reduces stress and time. It also reduces the likelihood of compounding errors during corrections.
7) Validate exports using “spot checks.” Even if you perform reconciliation, add a spot check method before finalizing. For example, randomly select a handful of payees and compare their exported totals to underlying invoices, contracts, and accounting entries.
Spot checks can detect hidden mapping problems that a high-level total might not reveal—for instance, if the export totals are correct overall but one payee category is systematically miscategorized.
8) Align internal labels with tax concepts. Many reporting problems come from mismatched internal categories. If your accounting categories do not map cleanly to the tax reporting categories, you should refine your chart of accounts (or at least refine how you tag transactions) so that “compensation,” “reimbursement,” “refund,” and “adjustment” are unambiguous.
This alignment reduces confusion when you generate the dataset for filing. It also improves the accuracy of audit trails because you can show how each transaction category maps to form reporting logic.
To make “Square Payroll 1099” operationally robust, it helps to consider additional real-world scenarios that commonly occur in contractor payment programs. These scenarios can influence how you categorize payments, how you reconcile totals, and how you validate payee records.
Many contractor engagements involve milestone billing or retainer structures. For milestone payments, you may issue payments at different points in the project year. For retainer agreements, you may receive an upfront fee that is later applied against future work.
From a workflow perspective, you need to determine whether those payments are treated as compensation or if any portion is refundable or applied as a credit rather than compensation. Even if your system records the payment as “received” or “paid” at a certain moment, your tax reporting needs to align with the form instructions and the manner in which amounts are treated as reportable.
A practical strategy is to ensure your payment categorization captures the intent of the payment. For example:
Because the details can be fact-specific, the key is to build a data model that preserves the distinctions. If you categorize everything as one umbrella “contractor payment” without detail, you may have to reconstruct meaning later.
Contractors sometimes submit updated tax forms mid-year. For example, they may change their legal name due to marriage or update their address. Occasionally, there may be a corrected TIN.
Operationally, you should have a process to:
When updating payee details, be careful not to create duplicates. Instead, update the existing payee record linked to all payments. This ensures that your export totals are not split across profiles.
If a contractor changes their tax classification or structure, you may need to confirm whether reporting should reflect one identity or a different one for the same vendor across the year. This is an area where consulting the specific form instructions and potentially professional tax advice can prevent mistakes.
Because reimbursements are a major cause of overreporting or misreporting, many organizations formalize reimbursements through policies and required documentation.
A strong reimbursements process might require contractors to:
From a recordkeeping standpoint, you want to ensure that reimbursement payments are not indistinguishable from compensation in your exports. That means:
It’s also important to consider partial reimbursement arrangements. For example, if you agree to reimburse a percentage of travel expenses or a negotiated cap, the policy should define how that reimbursement is documented and recorded. Your 1099 totals should reflect those decisions, not just the gross payment amounts.
Refunds and reversals are operationally common when using card payments or online transaction flows. Refunds might happen due to a customer dispute, service cancellation, or correction of an invoice.
From a 1099 workflow perspective, you need to ensure that your net compensation totals do not include refunded amounts as if they were still paid for services. If you reconcile correctly to the accounting books, you should already be netting refunds appropriately. However, some systems handle refunds in separate entries that can be easily misinterpreted.
Practical steps include:
A spot check can help: pick a payee with both payments and refunds and ensure the 1099 amount reflects the net effect that your accounting shows.
Even if your main goal is to file 1099 forms correctly with the IRS, recipients also need accurate information. If addresses are wrong, you might receive undeliverable mail notifications or delays in distributing forms to contractors.
To prevent address problems:
While recipient delivery does not change your underlying tax liability, poor address quality can create operational burdens and additional notices that consume time during tax season.
Reconciliation is critical, but audit readiness also includes the ability to explain the underlying logic. If asked, you should be able to show:
This matters because 1099 reporting problems sometimes arise from misunderstandings about what counts as reportable compensation. When you keep clear mapping documentation and supporting records, you can respond quickly.
Audit readiness also means keeping your documentation organized. If your team cannot quickly locate exports, W-9 forms, or reconciliation worksheets, the “audit response” becomes difficult. Establish a consistent folder structure by tax year, and keep each payee’s records accessible.
One of the most subtle challenges in “Square Payroll 1099” workflows is mapping internal transaction types to tax reporting categories. Software may have payment types like “services,” “consulting,” “labor,” “expense reimbursement,” “refund,” and “credit.” Accounting may have different account codes that represent these categories.
To ensure correct tax reporting, you must decide:
The key is that your mapping must be consistent and documented. If different team members apply different mapping logic, you can end up with inconsistent totals and higher error risk.
Over time, you should refine your mapping rules based on reconciliation outcomes. When mismatches occur, use them as feedback to improve the classification approach. This turns compliance into a continuous improvement cycle rather than a once-a-year correction.
Even though this is a business compliance topic, it is also a relationship management topic. Contractors may not understand why you need specific tax information or how you treat reimbursements.
Many compliance problems reduce significantly when you proactively communicate requirements to contractors:
While this may sound like administrative work, it saves time at year-end. Contractors are also more likely to respond quickly mid-year when you request updated tax forms or corrected information.
To reduce risk, implement operational controls that catch issues earlier in the year.
Examples of practical controls include:
These controls turn compliance from a reactive project into a proactive workflow.
Square Payroll can help organize and export payroll or payment-related data, but correctness depends on how recipients are classified, how payments were categorized, and whether the export aligns with the appropriate 1099 form instructions. Always reconcile totals and verify payee details before filing.
In general, independent contractors are individuals who are not employees and meet IRS criteria based on facts and circumstances (control, independence, and relationship). If you are unsure, review IRS guidance and consider professional advice.
Even one payment may require reporting depending on the payment type and the relevant IRS criteria for the form you are filing. Confirm the applicable form category and thresholds using IRS instructions.
Typically, you need payee identifying details such as legal name and tax identification number, plus accurate payment totals per payee. Exact field requirements depend on the specific 1099 form category.
Reimbursement handling varies based on documentation and how the payments were structured and recorded. The objective way to manage this is to separate compensation from reimbursements and follow the instructions for the specific 1099 form category you are preparing.
Corrective action depends on the nature of the error and IRS procedures for that form type. The very defensible method is to review the IRS instructions for corrections and consider professional guidance for complex cases.
Potential penalties and interest can apply for certain filing issues or inaccuracies. To minimize risk, focus on accurate classification, data consistency, reconciliations, and timely corrections per IRS guidance.
If a payee’s TIN is missing or incorrect, pause and address it before final submission if possible. Collect updated tax information from the payee using the appropriate tax form process. Then reconcile totals again to ensure corrections do not create duplicate payee records or split totals across multiple identities.
LLCs may be treated differently depending on their tax classification and the specific facts of the engagement. Whether a 1099 is required depends on how the contractor is classified and what the form instructions say about entities. Review IRS guidance and, when needed, consult a tax professional.
Common mismatch causes include inconsistent legal names, incorrect addresses, and TIN issues. To reduce mismatches, align your payee master data to the information collected on the tax documentation, ensure that exports use the same payee fields for filing and furnishing, and reconcile payment totals per payee using the same date range and netting rules you apply to your accounting books.
For authoritative requirements and definitions, consult:
These sources are the primary basis for compliance, and they supersede any interpretations from third-party summaries.
Because the IRS instructions are updated periodically and because specific questions can be fact-dependent, it is best to treat IRS materials as the final authority for your reporting decisions. Internal checklists and software workflows are valuable, but they should align to IRS requirements.
“Square Payroll 1099” is top approached as a workflow discipline rather than a single feature or setting. The quality of your 1099 outcomes depends on correct classification, accurate payee information, careful categorization of payments, and strong reconciliation. By treating 1099 reporting as an audit-ready process, you create clarity for tax time and reduce operational risk throughout the year.
When you implement the process consistently—collecting tax data early, tagging transactions thoughtfully, reconciling outputs to your accounting books, validating payee identity fields, and maintaining documentation—you create reporting that is not only accurate but also explainable. That explainability is often what makes the difference when questions arise.
Ultimately, successful 1099 reporting is not a one-time event. It is a year-round approach to managing relationships with independent contractors and managing the data trail that follows each payment. With a structured workflow, the burden of tax season becomes manageable—and the risk of mismatches and corrective filings is dramatically reduced.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
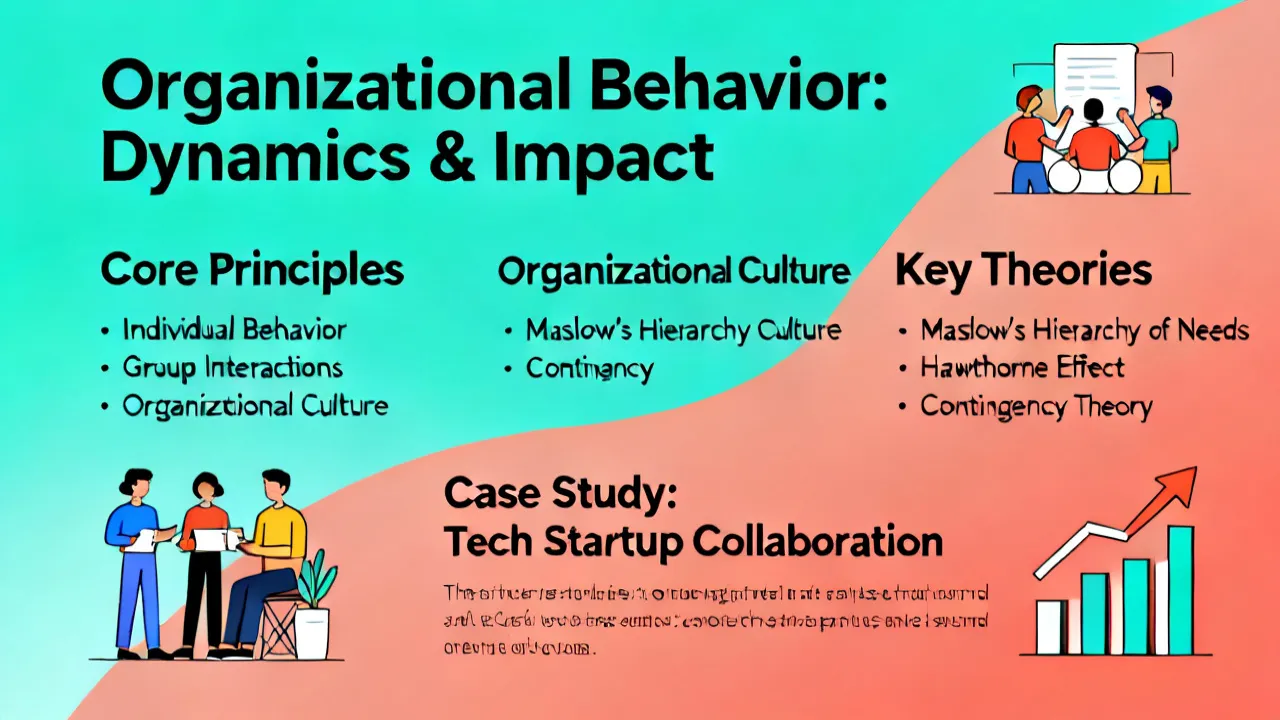
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
