This guide explains how Square Payroll supports 1099 reporting for independent contractors, focusing on practical compliance decisions, documentation readiness, and review steps. It provides objective background on “Square Payroll 1099,” clarifies what 1099 forms generally represent, and outlines conditions that businesses should confirm before filing or furnishing contractor tax forms.
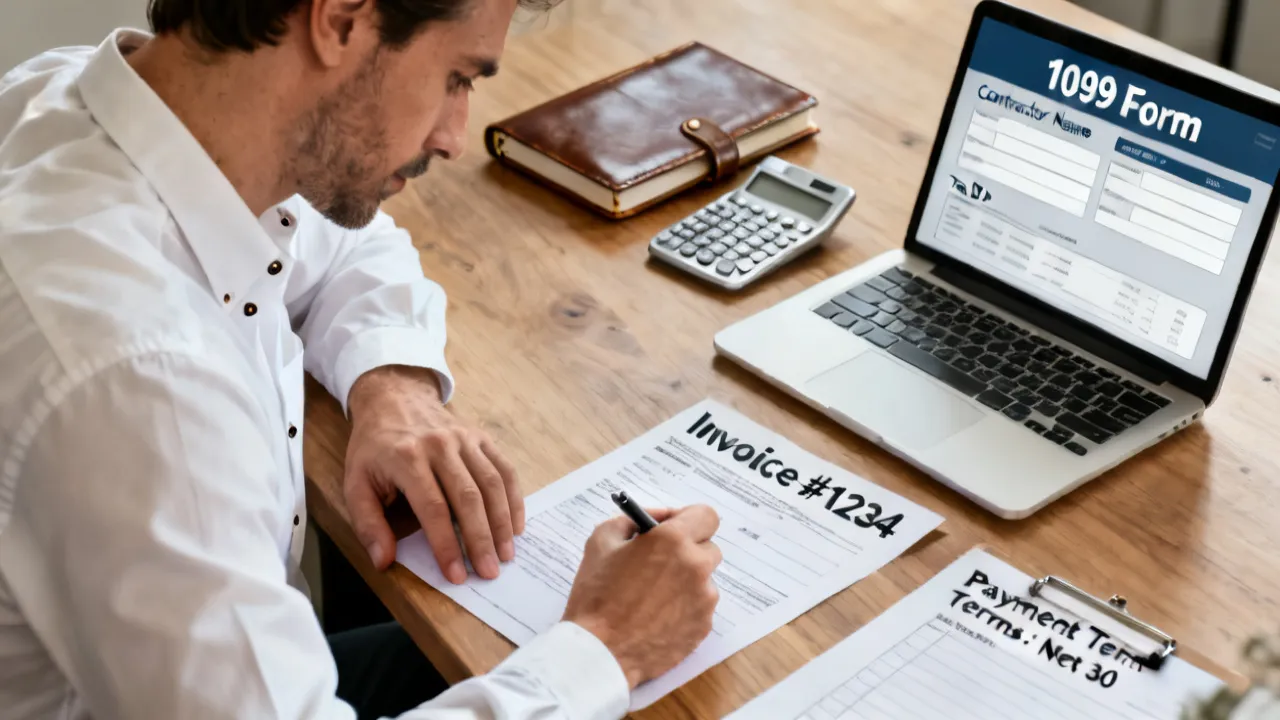
Square Payroll 1099 workflows are ultimately about documentation, classification accuracy, and timely form preparation for independent contractors. In practice, businesses should confirm how contractor payments are captured, verify required contractor details, and perform a careful review before any furnishing or filing deadlines. This is less about “pressing a button” and more about maintaining consistent records that can withstand tax-season scrutiny.
When a company uses Square (or any payroll/invoicing system) to organize contractor payments, the system becomes a recordkeeping engine—but the legal responsibilities remain with the business. That means you need to ensure (1) that the worker is appropriately treated as a contractor under applicable rules, (2) that your payment totals are coded and interpreted correctly for the specific 1099 reporting requirements, and (3) that the information you furnish and file (names, taxpayer identification numbers, addresses if required, and the amounts) is accurate and defensible.
A mature workflow treats 1099 reporting as a year-round process. The year-end “run” is the final step in a broader data lifecycle that starts when you onboard a contractor and continues through periodic reconciliation and internal review. If you structure the work this way, you reduce the odds of avoidable corrections, back-and-forth with contractors, and rushed tax-season fixes. For many organizations, that is the difference between a smooth filing season and one marked by amended forms and emergency administrative work.
“Square Payroll 1099” usually describes a reporting and form-furnishing process connected to independent contractors (often referred to as non-employee compensation reporting on IRS Form 1099 series). Many businesses use Square’s payroll and related tools to track payments and streamline year-end reporting. However, the compliance responsibility generally remains with the business: the software helps organize data, but classification rules, contractor eligibility, and form accuracy are business-owned tasks.
From an objective perspective, the phrase blends three concepts:
It’s also useful to recognize that in real-world operations, people use “Square Payroll 1099” as shorthand for “Square has my year-end contractor payment information and helps me prepare the 1099-related paperwork.” Depending on what Square features you’re using, you may be pulling contractor payment totals from multiple places (for example, invoicing systems, payment flows, or payroll settings). That’s why your internal checklist should not assume a single data source is perfect; it should verify that what Square reports matches what you intend to report.
Another frequent point of confusion is that “1099” can refer generically to many different tax forms (1099-NEC, 1099-MISC, 1099-K, 1099-INT, and others). Businesses sometimes hear “1099” and assume they must issue a single type of 1099 to every non-employee. In reality, different forms apply to different payment types and circumstances. Your workflow should therefore include a step that confirms which specific 1099 form (or forms) are relevant to your payment categories.
1099 forms matter because they connect payments made during the year with tax reporting obligations. When a business pays someone who is not an employee, the tax system often expects the business to report those payments to the IRS (and to furnish a copy to the recipient, where required). The exact filing form and requirements can vary by payment type and the recipient’s role.
For businesses, the main risk is not simply missing a form. The more common operational issues include:
It can help to think of 1099 compliance as having two separate—but related—tracks:
Many companies focus heavily on the administrative side (collect data, generate forms, file on time). That’s necessary, but it’s not sufficient if the substantive assumptions are wrong. Conversely, even if your worker classification is correct, your reporting can still fail due to administrative errors such as a missing TIN or a mis-entered legal name. Strong workflows address both tracks.
To stay grounded, very businesses should anchor their approach in official guidance from the IRS. For general 1099 principles and related reporting obligations, see the IRS instructions and publications on the 1099 series and backup withholding concepts. Your internal procedure should treat IRS instructions as the authoritative reference for rules that are highly specific—especially around eligibility thresholds, form selection, and how to handle missing/incorrect TIN data.
In an industry setting, I typically recommend treating “Square Payroll 1099” as a data lifecycle, not a single year-end event. The workflow begins at onboarding and ends at review, furnishing, and (when applicable) filing. When organizations structure their process this way, they reduce the chances that tax-season surprises will require rushed corrections.
An evaluation approach that works well in practice is to map each stage of the lifecycle to a specific risk. For example:
Once you can articulate the risks at each stage, you can build targeted controls—such as periodic reconciliations, completeness gates, and structured review checklists—rather than relying on a single “final review” that may be too late to correct root problems.
Before focusing on 1099 outputs, verify that the person or company you paid is properly treated as an independent contractor under the relevant legal framework. While the IRS provides guidance through various resources (including discussions of the “common law” employee/contractor framework), the key point for operational planning is this: software cannot fully substitute for classification decisions based on facts and circumstances.
Practical condition: If your classification policies are uncertain, pause reporting reliance and document the basis for contractor treatment. This is especially important if you manage contractors on-site, control work details extensively, or provide employee-like supervision.
In practice, classification uncertainty can arise from everyday business behaviors. For example, a business might feel that it is “just hiring help,” but in reality, it could be exercising the kind of control typically associated with employment. That can include directing how work is performed, providing training that resembles employee onboarding, requiring set schedules, controlling day-to-day methods, or integrating the worker into the company’s core operating structure.
A practical approach is to maintain a documented classification file for any “borderline” roles. Even if you do not anticipate IRS scrutiny, a well-reasoned documentation packet helps internally and supports third-party advice if you consult a professional. That file might include:
It’s also worth noting that classification rules can vary depending on the type of reporting, state law considerations, and other regulatory frameworks. While the prompt focuses on IRS 1099 reporting, an organization should ensure that its classification work is consistent across the broader compliance landscape—not only for federal reporting but for employment-related obligations too.
1099 reporting hinges on accurate recipient identification. In operational terms, the very important fields usually include the contractor’s legal name and tax identification number. If a contractor’s information is missing or mismatched, you may face issues such as rework, corrections, or potential backup withholding obligations depending on circumstances.
Practical condition: Set an internal “data completeness gate” before year-end. If your contractor onboarding is rolling, treat name and TIN collection as a continuous requirement rather than a last-month scramble.
Many businesses underestimate how much rework occurs due to small identity errors. Common data issues include:
Even if your internal team believes the information is “probably correct,” 1099 accuracy requirements typically justify a more disciplined standard. A completeness gate might include automated checks (for example, ensuring a TIN field is populated and a legal name meets minimum character patterns), but you should also implement a human validation step for exceptions.
If you use Square to store contractor or vendor information, align your internal “who is the contractor” records with your 1099 reporting records. A frequent source of errors is having multiple contractor records—perhaps created in different systems, under different names, or with slight variations in spelling—so that totals fragment across records. Fragmentation can make it seem like you underpaid or overpaid certain contractors for reporting purposes.
Additionally, consider how your workflow handles contractor updates. If a contractor provides corrections mid-year or near year-end, you should have a procedure for deciding whether to update the underlying payment coding, how to regenerate reports, and how to preserve a record of what changed and when. Those steps matter if you later need to explain corrections or defend your reporting decisions.
Businesses often pay contractors for multiple purposes: services, reimbursements, platform fees, or pass-through costs. While many systems track totals, not all payment categories automatically map to the same reporting rules. An industry top practice is to reconcile what the system reports as “contractor compensation” to your internal understanding of the nature of the payments.
Practical condition: Use your chart of accounts or payment categorization rules consistently so the totals presented by Square Payroll (or any payroll/accounting output) align with how you intend to report.
One of the most practical improvements you can make to a 1099 workflow is to ensure that every payment you intend to include in contractor compensation has a clear accounting “reason” for inclusion. For example, if you pay a contractor for design services, route those payments through an income/expense classification that the business has already decided is reportable (based on IRS instructions and thresholds). If you reimburse expenses that should not be treated as reportable compensation, code those reimbursements separately.
When categories are inconsistent across the year, you may end up with confusing aggregates. For example, you might find that some invoices recorded as “consulting” and others recorded as “contract labor” are mixed into the same totals, or that reimbursements were mistakenly included. The reconciliation step helps you see this mismatch before it becomes a filing error.
It can also be valuable to maintain a “reporting rules matrix” internally. This matrix can be a simple document that maps each payment type you commonly pay out to a decision: report on 1099-NEC, report on a different 1099 form, exclude entirely, or treat as a special-case item requiring review. As your business changes, the matrix can be updated. Over time, this reduces confusion and improves consistency.
Finally, pay attention to the boundary between the payment processing timeline and the tax year window. Some systems record when funds are processed, while your accounting might record when services were performed or when invoices were issued. Your workflow should define which timestamp drives inclusion in the reporting year. That’s not merely a bookkeeping detail—misalignment can cause some payments to slip into the wrong year or require reclassifications after the reporting run.
A robust review is more than checking totals. I advise teams to review at three levels:
When you design a review cycle, build it like a quality control process rather than a single ad hoc check. A quality control mindset often includes the following:
Recipient-level review should not only confirm presence; it should also confirm that the data matches the format you expect. For instance, if you compare the contractor’s legal name on file to invoices, contracts, or onboarding documentation, you may detect discrepancies early. Some organizations also compare the last four digits of a stored TIN to what contractors provided, although exact handling depends on internal privacy practices and what you’re permitted to store.
Payment-level review can include verifying that each payment falls under the reporting logic you defined. If you have multiple payment types (services, reimbursements, subscriptions, tooling, and so on), confirm which ones appear in the “contractor compensation” total. If the output includes something you consider non-reportable, adjust your coding or create a manual exclusion list.
Control totals should align with your accounting ledger. When they do not align, investigate the mismatch rather than forcing the numbers to agree. Mismatches often point to systemic issues, such as duplicate contractor records, time-window differences, or payments categorized incorrectly in the chart of accounts. Addressing the root cause prevents the same error from repeating across multiple years.
Additionally, build a process for “known anomalies.” For instance, some businesses pay certain contractors in partial payments throughout the year, or they may have contractors who invoice irregularly. You should anticipate these patterns and define thresholds or rules for what constitutes an anomaly. That way, reviewers focus attention where it’s most likely needed.
In many 1099 scenarios, businesses must both furnish a statement to the recipient and file information with the IRS. The timing and required actions can differ based on the specific 1099 form and tax year rules.
Practical condition: Use the IRS instructions corresponding to your specific form type. Your software may generate statements, but your business is responsible for ensuring you follow the applicable requirements.
In practice, “furnish” and “file” represent two administrative responsibilities:
These deadlines can differ from each other and can also vary depending on whether you file electronically. Your workflow should explicitly include both actions in the project plan, not just “file with the IRS.” Many organizations are tempted to treat it as a single deadline because the forms are prepared together—but missing the furnishing deadline can still create penalties or corrective work.
Also, consider the internal process for distributing furnished statements. If you send them electronically, you should confirm that your method aligns with IRS recipient furnishing rules and your contractors’ preferences/consent, where applicable. If you mail statements, confirm address accuracy and retain evidence that the statements were sent.
Another operational detail is version control. Suppose you discover an error after furnishing but before filing, or after filing but before any recipient updates. The best practice is to follow IRS correction procedures for the specific form type. That may involve filing corrected information returns and furnishing corrected statements to contractors, depending on the nature of the error. To prepare for these possibilities, your internal workflow should keep a record of what was furnished and what was filed, as well as when corrections were made.
Based on recurring patterns seen in tax operations, here are issues businesses encounter when working with contractor reporting:
Below are additional pitfalls that show up in real operational environments, even when teams believe they’re doing everything “right.”
One of the most common “soft” failures is the absence of a repeatable internal calendar. Teams sometimes run 1099 workflows ad hoc. That leads to last-minute scrambles, which increases error rates. Consider building a simple timeline:
This structure makes it much easier to catch errors early. Even if you can’t do everything monthly, doing it at least quarterly can reduce the chance that problems remain hidden until the final weeks.
From an expert standpoint, Square Payroll 1099 reports should be used as “work papers,” not as a substitute for decision-making. Treat the outputs as draft data that you verify. If you do outsource to a tax preparer or accountant, those reports and reconciliations can also improve the quality and speed of review.
When you treat the software output responsibly, you’re not trying to “prove” that the system is correct. Instead, you’re using the software as a structured data extractor and then validating the results against your internal rules and supporting documentation.
To use outputs responsibly, consider the following practical behaviors:
For objective guidance, the IRS provides general instructions on 1099 reporting and recipient data requirements. It’s advisable to consult those resources directly rather than relying on informal summaries. Tax reporting rules are highly specific, and small differences (for example, in payment type or recipient status) can produce different outcomes.
Also, consider the benefits of involving a professional when the numbers or complexity grow. If you have a small number of contractors and relatively straightforward payment types, internal checks may be sufficient. But if you handle multiple payment categories, have unusual contract arrangements, or face classification uncertainty, professional review can reduce the risk of filing errors.
| Component | What to verify | Why it matters | Conditions / requirements |
|---|---|---|---|
| Contractor classification | Whether the recipient is truly a non-employee under applicable rules | Determines whether 1099 reporting applies at all | Confirm facts and circumstances; document your classification rationale |
| Recipient identity data | Legal name and taxpayer identification number (TIN) | Avoids errors that can trigger corrections | Maintain complete, consistent records; resolve missing or incorrect details early |
| Payment categorization | Which payments are treated as reportable contractor compensation | Ensures your totals match the intended reporting category | Apply consistent coding rules across the year; reconcile exceptions |
| Software output review | Recipient totals, included payments, and control totals vs accounting | Finds data mismatches before furnishing/filing | Use a review checklist; compare to the general ledger or accounting reports |
| Furnishing and filing deadlines | Whether you must furnish recipient statements and file with the IRS | Prevents late filings and avoidable penalties | Follow IRS instructions for the specific form type and tax year |
| Potential backup withholding (if applicable) | Whether any special handling is required based on missing/incorrect TIN data | Impacts withholding and reporting obligations | Review IRS backup withholding guidance relevant to your situation |
Primary sources to consult: IRS instructions for the relevant 1099 form type, IRS publications covering information reporting and backup withholding rules, and IRS guidance on worker classification and reporting obligations.
Step-by-step guide (operational checklist):
Additional “requirements” considerations you may need to operationalize:
It generally refers to using Square’s payroll-related data and reporting tools to support year-end information reporting for independent contractors on 1099 series forms. Regardless of software, your business remains responsible for correct classification, accurate recipient data, and adherence to IRS filing/furnishing rules.
In practice, the phrase can mean different things depending on how your business uses Square. Some companies may use Square mainly to capture invoices and payments, while others may use payroll-related features for contractor payment tracking. Your best approach is to identify your exact data source(s) for the totals you plan to report and validate that those totals reflect the reportable payments under the relevant IRS form instructions.
Not necessarily. Whether a 1099 applies depends on the type of payment and applicable IRS requirements for the specific reporting situation. You should consult the IRS instructions for the relevant form type and criteria.
A responsible operational step is to maintain a “reportability decision” for each contractor and each payment type. Some contractors may be excluded due to their status or due to the nature of the payments. Others may require reporting only if payments cross certain thresholds. You should not assume universal applicability.
Incorrect or missing recipient identification details (such as legal name or TIN) and miscategorized payment data are among the very frequent drivers of corrections. That’s why recipient-level validation and payment reconciliation matter.
Another common driver is duplicate contractor records leading to split totals. In those cases, the amounts may still add up correctly, but they are assigned to the wrong recipient record. Corrections then become administrative and time-consuming. You can reduce this issue by enforcing consistent naming conventions and establishing a contractor master record approach.
No. A top practice is to use Square Payroll outputs as a starting point, then reconcile with your accounting records and review included payment categories. This reduces avoidable discrepancies before furnishing or filing.
Even if your totals “look right,” a reconciliation spot-check can identify mismatches such as payments posted to the wrong period or reimbursements included inadvertently. The objective is not distrust of the system, but confirmation that the output aligns with your reporting rules and your financial records.
Establish an internal cut-off for year-end processing and a procedure for late updates. If changes occur after you generate reports, you may need to rerun data outputs and re-verify recipient information before furnishing/filing.
A good operational method is to separate two “modes” of the process: a data collection mode (where updates are accepted freely) and a reporting freeze mode (where updates must be evaluated and, if they affect reporting, the report is rerun and the review cycle is repeated). This reduces the odds of furnishing statements with outdated information.
For tax reporting, accuracy is essential. If the legal name is unclear, you should request clarification from the contractor rather than guessing. Misreporting can lead to corrections and potential withholding-related complications depending on the facts.
In some cases, contractors use the same name for business and tax reporting, but in other cases, the legal name on tax documents differs from the “operating name” they use publicly. Your workflow should treat legal name as the authoritative field for reporting.
The IRS provides the authoritative instructions and guidance for each relevant 1099 form type, including requirements, deadlines, and recipient data rules. Those instructions should be your primary reference.
If you have multi-state operations or additional reporting obligations, also consider state-level requirements. While your question is focused on IRS reporting and 1099 readiness, state reporting can have its own deadlines and rules for worker payment reporting and withholding.
If you have uncertainty, document your analysis and consult professional guidance. Worker classification is fact-specific and can affect reporting obligations. Software reporting should not be used to override classification decisions.
In such situations, it’s especially important not to “solve” classification uncertainty by simply reporting a 1099. If the facts lean toward employee treatment, reporting based solely on how a worker is labeled in your system could create broader compliance issues. Consider consulting an employment tax professional or legal counsel to ensure your classification posture is supported by the facts.
Square Payroll 1099 reporting can be efficient when your underlying data practices are consistent—contractor details are accurate, payment categories are applied uniformly, and outputs are reviewed against accounting records. The strongest approach is repeatable year-round hygiene: disciplined onboarding, periodic reconciliation, and a structured review cycle at year end. That combination reduces operational friction and supports compliance decisions you can stand behind if questions arise.
To make the process defensible, ensure that your workflow produces evidence—not only numbers. Evidence includes documented classification decisions, records of contractor identity information collection, reconciliation worksheets linking Square output to accounting records, and internal checklists showing that review steps were performed. In tax operations, a defensible process is one that can be explained clearly and supported with reasonable documentation.
Finally, remember that 1099 reporting is only one part of broader contractor compliance. If you maintain contractors responsibly—by using clear agreements, paying according to contract terms, collecting required documentation promptly, and ensuring classification aligns with the facts—you’re not only preparing for a single filing season. You’re reducing compliance risk across the life of your contractor relationships. That long-term approach typically results in fewer corrections, fewer disputes, and a more reliable reporting workflow over time.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services


Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.

Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.
