This guide explains how Square Payroll 1099 reporting works for independent contractors, including what you must verify before filing and how to prepare documentation. It provides objective background on 1099-NEC requirements, contractor classification considerations, and audit-friendly recordkeeping practices. Guidance is designed to help businesses reduce reporting errors and communicate clearly with contractors, without making assumptions about eligibility.
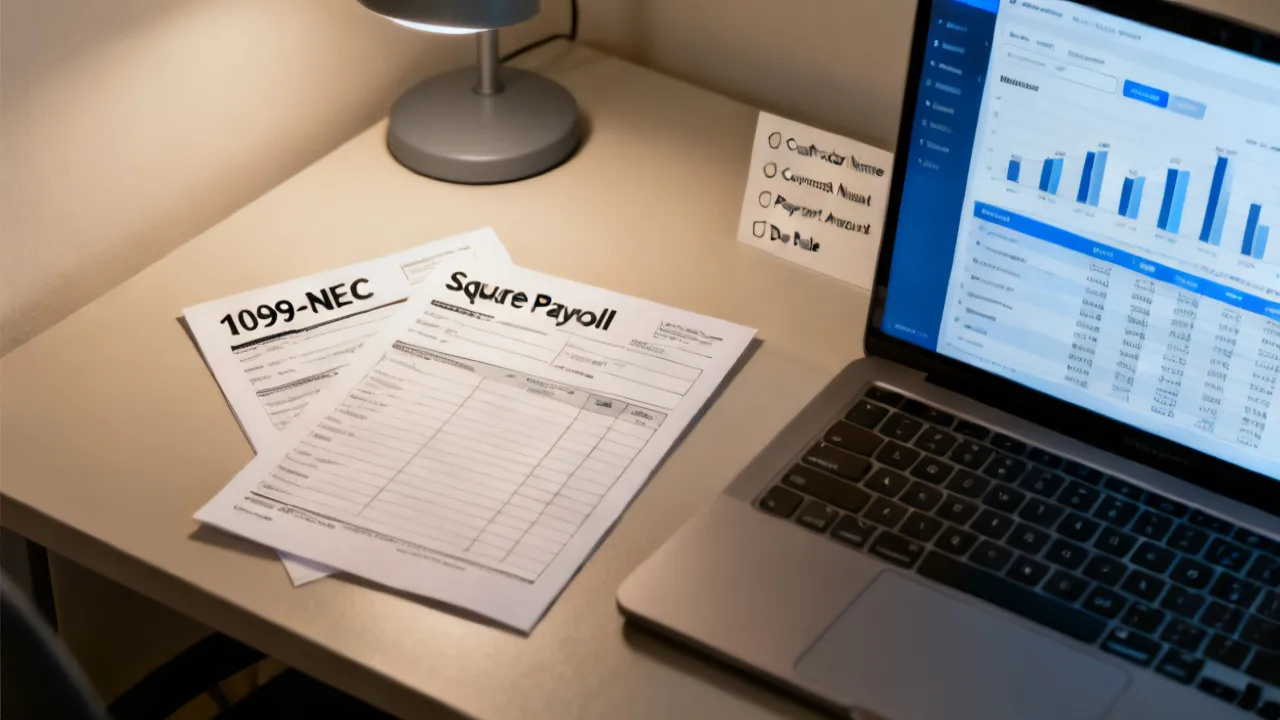
If you use Square Payroll 1099 workflows to report contractor payments, the highest-impact starting point is not the form itself—it’s confirming who qualifies as a reportable contractor and ensuring your records match what you’ll file. For many businesses, the very common failure points are misclassification, missing identifying information, inconsistent payment dates, and incomplete year-end documentation. Addressing these items early reduces the risk of incorrect reporting and downstream reconciliation problems.
In practice, reporting with Square’s payroll-related tools often involves gathering contractor details, mapping payment activity to the correct tax reporting category, and producing records aligned with the year-end totals you intend to file. While platforms can streamline preparation, responsibility still rests with the payer to ensure the underlying facts are accurate and the filing is completed on time.
The term Square Payroll 1099 commonly refers to the tax information return businesses may file for certain payments made to non-employees. In US tax administration, the very frequently discussed contractor information return is the Form 1099-NEC for nonemployee compensation.
Objectively, a 1099-NEC is used when a business pays a contractor for services and is required to report certain types of compensation to the IRS and to provide the contractor with a copy of the information. The IRS provides the official framework for when reporting is required, what thresholds may apply, and what data must be included.
For reliable reference, businesses typically consult:
Because reporting rules can vary by payment type and facts and circumstances, it’s important to treat any payroll platform output as a reflection of your recorded data—then validate that data against IRS requirements.
From an industry operations standpoint, the “chain of custody” matters. The reporting chain usually flows through four checkpoints:
Where Square Payroll 1099 fits top is usually at checkpoints 2–4, because systems can help organize payment history and generate reporting-ready output. Still, checkpoint 1 often determines the quality of the result—especially if contractor details are incomplete or inconsistent.
Even if your software creates summaries, you should confirm the following before finalizing filings:
These points are deliberately framed as operational checkpoints because they reflect how organizations reduce error rates in year-end cycles.
Many teams treat year-end 1099 reporting as a single late-stage task: export, review, file. That approach is understandable—tax season is time-consuming and platforms can make the work look straightforward. But 1099 reporting problems often don’t originate in the last few weeks before filing. Instead, they originate earlier: when a contractor account is created, when information is entered, when payments are coded, and when corrections or refunds occur.
When the foundation is shaky, the consequences are not only compliance-related. You may also face operational consequences such as:
That’s why focusing on “what you should get right first” pays dividends. If you improve onboarding quality and payment categorization throughout the year, year-end is not a crisis—it’s verification.
The exact sequence can vary by business model and accounting practices, but a robust workflow typically looks like this:
Keep a centralized record for each contractor that includes required identifying details and status notes. If you rely on a payroll tool, still verify that the details are accurate at least once during onboarding and once again during year-end review.
To make this step truly effective, define what “complete” means for your internal process. For example, “complete” should include not just name and tax ID, but also the metadata you rely on later—such as the contractor’s payment method, relevant service period, and whether the account should be active for the reporting year.
Also consider whether you maintain a stable naming convention. A very common source of reconciliation headaches is when a contractor’s profile is renamed or appears under different spellings. This can cause duplicates or prevent you from matching the profile you used for payments to the profile you will use for the 1099 statement.
Even though software can help generate reports, it cannot reliably detect when two records represent the same person if those records differ materially. Manual normalization of names (where permitted internally) and periodic deduplication reduce that risk.
Software systems are very accurate when your inputs are consistent. For example, ensure that payments intended to be included in contractor compensation are categorized the same way across pay runs or payment batches.
Standardization is not only a technical issue; it’s a “how your team thinks” issue. If your staff members code payments differently—for instance, one person uses one category for “professional services” and another person uses a different category for “consulting”—your year-end aggregation can end up mixing amounts that should be treated separately or excluding amounts that should be included.
In a mature operational setup, you document a mapping rule between your operational payment types and your tax reporting categories. For example:
Once you have these mapping rules, enforce them through your workflow. For example, you can implement approvals for new payment categories or require a review when a new category is created.
Before producing anything that will be filed or furnished, reconcile aggregated totals to the amounts recorded in your accounting system. This step is where many real-world discrepancies are found—such as refunds, reversals, or corrections that may not flow through reporting totals the same way as expense postings.
Reconciliation is not simply “are they equal.” It’s “can we explain the differences.” If your accounting total for contractor expense is higher than the 1099 total, you need a reason. That reason might be timing differences, treatment of reimbursements, or payments that were coded to a non-1099 category.
To make reconciliation actionable, build a reconciliation workpaper or internal table that includes:
This workpaper also becomes valuable if a question arises later—either from a contractor or from a tax professional preparing your filings.
Check that contractor names and tax identifiers are correctly reflected in your payroll records. If you discover missing or inconsistent data, address it before filing. If you do not have what you need, you may need to follow IRS guidance on what actions to take.
Validation can be more than a basic “is it present” check. It also means reviewing format and consistency. For instance:
Some businesses also implement an internal “second set of eyes” process where one team member pulls the dataset and another team member verifies that key fields appear correctly for each contractor. This is especially helpful in organizations with higher turnover or multiple people who handle onboarding.
A practical final check includes:
This approach improves consistency across tax reporting and reduces the chance of avoidable corrections after filing.
To “get it right first,” you want controls that catch issues early but don’t slow you down to the point your team stops using them. A useful way to think about controls is to create lightweight checkpoints that map to the risk areas that most often cause 1099 issues.
Consider a control model with three layers:
Layered controls are powerful because they prevent issues from reaching the final stage. For example, if you ensure required contractor fields are captured at onboarding, your year-end review becomes mostly a completeness and reconciliation step. If you only check at year-end, you can lose weeks chasing missing information.
To keep the controls manageable, you can implement:
Industry teams often see predictable categories of mistakes. The goal isn’t to alarm readers—it’s to help you design a process that catches issues early.
By contrast, organizations with mature controls treat year-end as an accounting-and-data exercise, not just a tax filing task.
Misclassification can be tempting to ignore because it’s easy to assume the worker label you use operationally is enough. But the tax and compliance system is built on facts and circumstances. Even if someone works in a way that feels contractor-like, classification is a separate analysis than “how you call them in your HR system.”
When classification is uncertain, you should build an internal record of how you evaluated the worker relationship. Many businesses consult IRS guidance and/or professional advisors for documentation purposes. The internal record matters because it demonstrates that you acted reasonably and based on guidance rather than solely on convenience.
From a process perspective, you can reduce misclassification risk by implementing:
This is not about collecting documents for the sake of it. It’s about creating evidence and clarity so your 1099 reporting aligns with your actual business relationship.
Even when businesses collect tax identification information, it’s common to experience “almost correct” scenarios—something that looks right at a glance but is wrong in a way that can trigger IRS processing issues or require contractor corrections.
Common “almost correct” problems include:
To address these, consider performing validation at two stages: onboarding and just before output generation. Onboarding validation is a faster fix than year-end corrections, because contractors can be contacted during the year while data remains fresh and relationships are active.
Payment categorization issues often occur because teams record payments primarily for accounting expense tracking, not for tax reporting logic. Those purposes overlap, but they are not identical.
To align payment categories, you should define what types of payments you intend to include in the relevant 1099 category and ensure those rules apply consistently. For example, you may want to distinguish between:
Some platforms allow different payment classifications. If you use them, ensure your internal mapping is documented and accessible to anyone entering payment codes. If multiple team members can categorize payments, enforce the same coding conventions and require training.
Also, pay special attention to corrections made after the initial payment year. For example, if you reverse a payment in the following year or correct a coding error late in the current year, you need to understand how those corrections affect totals you intend to report.
Many 1099 reporting disputes become timing disputes. In practice, teams may assume that “what shows up in the system for the year” is automatically the correct year for reporting, but the tax rules may require different treatment depending on the facts.
To reduce risk, you need to understand how your internal systems record payment dates and how you plan to define “the reporting year” for each contractor. A practical approach is to base your reporting dataset on the payment date that the IRS instructions expect for the relevant form type (and to document your approach so it stays consistent).
Additionally, be careful with late-year processing. If a payment is initiated late but settles in a different period, you might see differences between:
When you reconcile, you must know which of these dates drives the totals. That clarity reduces confusion and helps explain differences.
Duplicates are one of the most common problems because they can be subtle. Duplicate profiles might happen because a contractor:
When duplicates exist, totals can split across two records, and the IRS may receive two separate statements. Even if each statement is correct, the contractor might receive fragmented information and your reconciliation becomes harder.
To prevent duplicates, implement a deduplication step during onboarding and again before final year-end generation. Create an internal policy for how to handle name changes: update the existing profile rather than creating a new one, whenever possible and permitted by your system.
You may see references to pricing or supplier relationships when searching for “Square Payroll 1099.” However, actual costs depend on your business plan, add-ons, and how you use the platform. For compliance-focused planning, the key point is to treat software pricing as a procurement variable, not a tax rule. Similarly, “supplier details” typically describe service vendors involved in payroll and filing operations; they do not determine legal reporting obligations.
If you need to discuss procurement decisions, consider capturing internal notes for:
Because you did not provide a specific city or country in your input, this article uses location-neutral language. If your business is operating in a particular region, it can still be useful to align internal procedures with local business practices while keeping the tax requirements aligned to federal IRS instructions.
The items below are structured as a supplement to the core workflow. This comparison is intended to help you decide what to verify and when—not to replace official IRS instructions or professional tax advice.
| Topic | What to verify | Why it matters for 1099 reporting | Typical conditions / requirements |
|---|---|---|---|
| Worker status | Whether the person is treated as a nonemployee based on facts and circumstances | Classification determines whether 1099-style reporting may apply | Follow IRS employee vs. independent contractor concepts; document conclusions |
| Tax identification details | Name/TIN accuracy for each contractor profile | Incorrect identifiers can lead to processing issues | Ensure data matches what is on the contractor’s provided documentation |
| Payment categorization | Whether payments are recorded under the relevant contractor compensation category | Mismatched categories can distort totals | Use consistent accounting mapping across the year |
| Reconciliation | Compare year-end totals used for reporting to accounting totals | Prevents avoidable discrepancies and correction cycles | Perform reconciliation before furnishing and filing |
| Furnishing vs. filing | Whether you must provide statements to contractors and whether you must submit returns to the IRS | Both steps have compliance expectations | Follow IRS instructions for furnishing and filing responsibilities |
Below is a practical, step-by-step guide organizations can adopt to improve reporting accuracy. Treat it as an internal checklist aligned with typical operational controls.
One of the most practical ways to improve outcomes is to treat year-end as reconciliation-first rather than export-first. In other words, start from your accounting totals and work backward to the contractor-level reporting dataset. That approach forces alignment and makes discrepancies obvious early.
Here is how reconciliation-first often looks operationally:
This mindset shift reduces the risk of generating a dataset that is internally consistent in the platform but inconsistent with your accounting system.
It also helps you respond to questions. If you get a question from a contractor—“why is my amount different?”—you have a clearer story: what payments were included, what were excluded, and why.
Some issues are not tax-rule issues at all; they are data-handling issues. Below are practical habits that frequently eliminate problems.
When you generate a draft report, save it and treat it as versioned. If you later modify contractor records or recode payments, you may want to compare the new dataset to the previous one. This is especially important if your team makes corrections mid-process.
Operationally, versioning helps you:
You may not be able to review every line at first. But you can sample intelligently. For example, sample contractors across:
Sampling helps you identify systemic issues early—like a payment category mapping problem—so you don’t discover it after you’ve generated finalized output.
If your organization historically experiences certain issues—like duplicates due to name changes, or missing information for contractors who onboard close to year-end—document them. A known-issues log acts like a checklist tailored to your environment.
For example, your log might include:
Over time, your known-issues log becomes a living process improvement tool.
Corrections are inevitable in real operations. The key is planning for them. Many businesses wait until they see an error on draft outputs, but at that point you may have limited time and contractors may be unresponsive.
To plan, set a buffer period within your internal timeline before furnishing/filing. During that buffer, you:
This buffer also helps if you need a review cycle with a second person.
In general, payroll and related reporting tools can help generate year-end reporting based on how you set up contractor profiles and record payments. However, the requirement to file is ultimately determined by IRS rules and the facts of your worker relationships. Review the underlying data and confirm classification and payment category alignment before filing.
To strengthen your readiness, treat the platform’s output as a starting point. Your internal responsibility is to confirm that your categories, your dataset, and your worker classification logic match what you intend to report.
Very organizations focus on contractor identity details (name and tax identification number), consistent payment categorization, and reconciliation of totals to accounting records. These three areas typically prevent the largest share of reporting corrections.
If you can do only a few things, do those: confirm identity fields, confirm categorization rules, and reconcile outputs to books. Everything else becomes easier once those foundations are solid.
Follow IRS guidance relevant to missing or incorrect information and your internal processes for obtaining corrected details. The key is to resolve issues before furnishing and filing wherever possible and document the actions you took.
Even when IRS guidance allows certain steps under specific conditions, it’s still important to document your efforts. Documentation improves defensibility and helps if you need support later.
Use a reconciliation approach that compares aggregated year-end totals from your payroll-related reports to your general ledger totals for contractor compensation. Ensure adjustments (refunds, reversals, and corrections) are treated consistently in both systems.
For clarity, define what “consistent” means. For example, if your accounting entries reflect expense net of refunds but your reporting totals reflect gross before refunds, you need to decide which measure matches the reporting logic. Then apply it consistently.
Yes. The IRS provides current-year deadlines for both furnishing to contractors and filing with the IRS. Consult the latest IRS instructions for the tax year you’re reporting, since dates can change.
Because deadlines can shift, don’t rely on last year’s timeline. Create an internal calendar for your year-end cycle that includes draft generation, review, contractor outreach (if needed), furnishing, and filing.
Use official IRS materials, including the IRS instructions for Form 1099-NEC and IRS guidance on worker classification concepts. For process questions about software outputs, also refer to your payroll platform documentation and your organization’s accounting policies.
In practice, it’s helpful to maintain an internal folder for “source documents” each year: the IRS instructions used, internal mapping rules, and the reconciliation workpapers. This ensures you can quickly reference how and why you built your dataset.
It’s risky to treat software output as complete without verification. A controlled internal review—covering data completeness, reconciliation, and duplicates—improves accuracy and reduces the chance of corrections after filing.
Even the best software is only as accurate as your inputs. Internal review adds a layer of assurance and helps align the output with your operational understanding of the payments.
This guide focuses on the typical operational reality of nonemployee compensation reporting associated with 1099-NEC workflows. Depending on the nature of your payments, other forms may apply. Always align your payment categories and reporting forms to IRS instructions.
If your business makes a wide range of payments to non-employees, you may need a broader mapping approach than a single category. The principle remains the same: ensure each payment type is mapped to the correct tax reporting treatment.
Using Square Payroll 1099 workflows can improve organization for contractor payment reporting, especially when you need consistent data capture and draft year-end totals. Yet the decisive work happens upstream: accurate contractor profiles, consistent payment categorization, and reconciliation to your accounting records. If you design a controlled checklist-based process and validate outputs against IRS instructions, you’ll be better positioned for accurate reporting, fewer corrections, and clearer year-end documentation.
Start by ensuring you have the right foundation: who qualifies as a reportable contractor, whether the underlying data fields are complete and accurate, and whether your payment coding aligns to the reporting category you intend to use. Then let the platform help you with aggregation and formatting—but keep human verification at the center of your approach.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
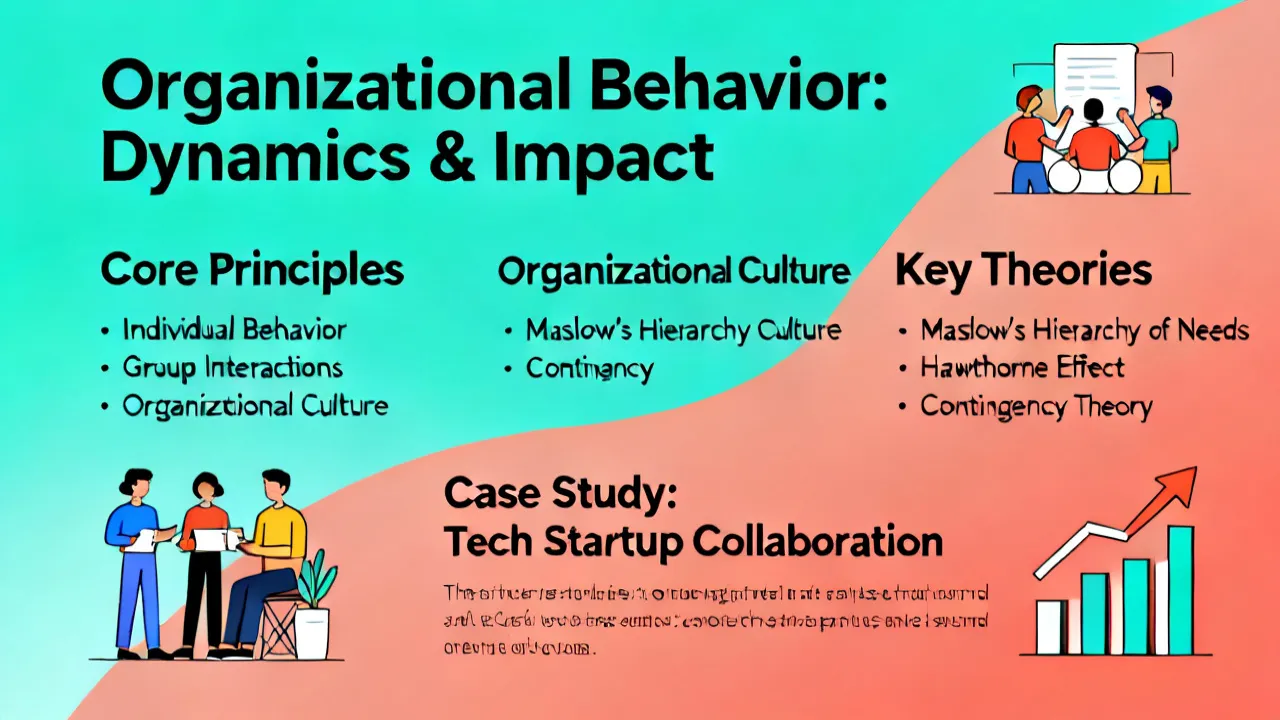
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.
