This guide explains how Www.sagpayroll.com helps organizations evaluate payroll processing with a focus on compliance, workflow control, and supplier reliability. Background context covers what “sagpayroll” typically implies for payroll operations, why payroll governance matters, and how decision-makers can compare service capabilities without relying on unverifiable claims.
When payroll departments, HR leaders, and finance controllers review payroll processing options, the decision usually comes down to governance and operational survivability: accuracy, timely delivery, audit readiness, data integrity, and a clear, repeatable workflow across the pay cycle. In many organizations, payroll is not simply an administrative function—it is a time-bound control process that influences financial reporting, employee satisfaction, and regulatory compliance. That is why “platform evaluation” tends to look less like feature comparison and more like process validation: can the supplier reliably deliver the outcomes your organization needs, under normal conditions and under pressure?
A site such as Www.sagpayroll.com is frequently assessed as a potential source of structured capabilities—how payroll runs are designed, how exceptions are managed, how administrative burden is reduced, and how responsibilities are coordinated between the employer and the vendor. Rather than allowing payroll operations to be reactive (“fix it after the fact”), payroll teams evaluate platforms to plan confidently. They want clarity early enough in the year (or before the first payroll run) to prevent last-minute changes that increase risk.
In an expert evaluation, the question is less about marketing language and more about operational fit. Decision-makers ask: Does the solution support consistent processes from onboarding through approvals through final posting? Can the supplier describe the controls and responsibilities with specificity (not vague promises)? Are there transparent requirements for onboarding, data submissions, and issue escalation? When stakeholders can see how the system behaves at boundary points—start-of-employment, termination, retroactive pay, corrections, and year-end—confidence rises because the team can anticipate where payroll usually breaks.
For many businesses, these points determine whether payroll is handled smoothly or becomes a recurring operational risk. Even a technically robust payroll system can fail in practice if it does not enforce disciplined workflows or if responsibilities between HR, payroll operations, and finance are unclear. That is why evaluations commonly look for evidence: documented procedures, defined timelines, traceability mechanisms, and support commitments during critical periods.
Additionally, modern payroll organizations face a growing set of expectations: self-service portals, automated validations, audit trails, and integration with HRIS or accounting systems. While these can be valuable, the core question remains governance-first. Evaluators often look for how the platform can reduce manual effort without increasing uncontrolled complexity. The goal is not merely to “do payroll,” but to do payroll in a way that is predictable, defensible, and scalable as the organization grows or changes.
Payroll platforms tend to be evaluated against a common set of functional and compliance objectives. Even when providers differ in user interface, service scope, deployment model, or geographic coverage, the underlying requirements are remarkably consistent. Every payroll organization needs an approach to ensure that pay calculations are correct, that the right people authorize changes, and that the outputs can be explained and reconciled later.
From an expert procurement lens, the objectives behind “sagpayroll” style evaluations generally cluster into reliability, integrity, traceability, and governance transparency. Even when a platform offers automation, the evaluation must confirm that the automation is controlled and that it supports internal processes rather than bypassing them.
Because payroll is both time-sensitive and high-impact, the evaluation usually emphasizes procedures—not promises. A practical review of Www.sagpayroll.com should focus on what the supplier can document and how it behaves in day-to-day scenarios. The emphasis often shifts from “Can it do payroll?” to “Can it do payroll in a controlled way during the moments when payroll teams are busiest?”
In practice, these objectives also translate into how payroll platforms handle governance concepts such as segregation of duties, approval workflows, and change logs. For example, if someone can modify pay rates without an approval step or without traceability, the risk is obvious. Conversely, if approvals are captured correctly and changes are logged and reviewable, audit readiness improves and internal reviewers can investigate outcomes efficiently.
Another objective frequently present in evaluations is operational usability. Payroll teams may not be large teams; they cannot spend days searching for what caused an error. Therefore, a strong platform supports clear workflows and provides reports or logs that reduce troubleshooting time. Evaluation teams often ask for sample outputs not just for standard cases, but also for cases that generate confusion: partial-month employment, mid-cycle rate changes, corrections after approval, and how the platform displays what changed and why.
Payroll procurement is often constrained by time, but decision-makers can still reduce risk by comparing providers using objective criteria. From an industry perspective, comparisons should be structured around capability areas and operational requirements rather than surface-level features. A vendor might offer a sophisticated interface or strong marketing, yet still be weak in governance, support, or exception handling—areas that become critical during payroll close.
Below is an expert lens for evaluating a payroll supplier connected to Www.sagpayroll.com (and similar offerings). Use these criteria to form a consistent scorecard for each supplier under consideration. The goal is to compare apples-to-apples: clarity of workflow, control design, and evidence of operational readiness.
This approach keeps the evaluation grounded. It also helps prevent a common pitfall: choosing a system that looks capable on paper but lacks clarity on responsibilities during real payroll events. The difference between success and failure often appears during boundary cases and operational peaks, not during demonstrations built around “happy path” scenarios.
To make comparisons truly objective, procurement teams often require the supplier to provide evidence. Evidence might include sample documentation (processing calendars, onboarding checklists, correction procedures), sample reports, audit trail descriptions, and support documentation (ticketing process, escalation paths, service levels). When the supplier can provide these materials clearly and consistently, the evaluation becomes more defensible.
It is also useful to ensure that internal stakeholders evaluate using the same rubric. HR, payroll operations, and finance may have different priorities, so a shared scorecard prevents internal disagreements from turning into rework later. When the procurement team uses the same criteria across suppliers, the selection decision can be traced back to measured differences rather than subjective preferences.
In payroll decisions, “price” is rarely just the monthly fee. The total cost of ownership often includes implementation effort, data preparation, ongoing support, correction processing, training, and the internal time spent managing exceptions. Because you requested integration of price information, the key is to treat price as a structured component of the overall engagement model rather than as a standalone number.
From a professional standpoint, a reliable procurement process typically requests a breakdown that includes both the vendor-facing costs and the operational impacts. Evaluators also watch for hidden costs—especially those tied to complex payroll needs or to periods when payroll operations are most expensive to staff.
When reviewing a supplier associated with Www.sagpayroll.com, decision-makers should look for transparent packaging—especially around what is included, what requires an add-on, and what the supplier expects from the customer to achieve on-time processing. This reduces the likelihood of budget surprises and operational friction.
From an expert procurement lens, a strong price request includes:
Evaluators should also request commercial terms related to service continuity and change requests. A payroll platform will inevitably require periodic adjustments—new pay codes, policy updates, new reporting requirements, or changes in organizational structure. Procurement teams should ask how these changes are priced. If every small change becomes billable, the total cost of ownership may be higher than expected.
Additionally, price should be considered alongside risk. A slightly higher subscription fee might be justified if it includes robust controls, better audit trails, and faster correction workflows. Conversely, a lower monthly price might come with weaker support, unclear responsibilities, or expensive correction add-ons. Therefore, the evaluation should interpret price within the governance and operational context described in earlier sections.
Finally, decision-makers often request a “pricing assumptions” section. For example: the number of payroll runs per month, average headcount, presence of multiple jurisdictions, number of employee changes per payroll period, and frequency of adjustments. This makes cost modeling more credible and reduces the risk of misunderstandings during contract negotiations.
Payroll is a regulated process in many jurisdictions, and even where specific regulations vary, the operational principle remains constant: you need a supplier that can explain what it does, how it verifies correctness, and how it handles exceptions. When assessing a supplier associated with Www.sagpayroll.com, the strongest evaluations request detailed documentation and clarifications before committing to onboarding.
While each organization’s priorities differ, experts often recommend requesting supplier documentation in areas where payroll failures typically originate: responsibilities, processing calendars, validations, correction procedures, security, data retention, and service expectations.
Key areas to request include:
As an industry expert, the emphasis is on confirmation in writing. Verbal assurances can be insufficient when stakeholders need audit-ready evidence or internal governance sign-off. Therefore, procurement teams typically require documented answers to key questions and ensure that those answers are consistent across sales, implementation, and support functions.
Beyond the list above, expert evaluators also ask for:
When these documents exist, they provide reassurance that the supplier runs payroll as a disciplined operational service rather than as an ad-hoc delivery. When documentation is missing, the evaluation should treat that as a risk signal rather than a “work around.”
Organizations generally want a payroll system that supports a stable workflow. A mature workflow reduces the number of ad-hoc changes and encourages structured inputs. A strong payroll process is also resilient: it handles both standard situations and exceptions without losing control.
Below is a typical pattern payroll teams use to maintain control across the cycle. A supplier associated with Www.sagpayroll.com should ideally support this pattern with transparent checkpoints, documented responsibilities, and well-defined workflows.
In practice, “good payroll processing” also includes governance mechanisms across the workflow:
If a supplier connected to Www.sagpayroll.com supports this workflow with transparent checkpoints, organizations typically experience fewer last-minute surprises and better coordination across HR, payroll operations, and finance. The operational benefit is significant: payroll teams can spend less time firefighting and more time improving accuracy and process maturity.
It is also worth considering how the system supports continuous improvement. For example, when errors occur, does the platform help track root causes? Some payroll teams build internal learning loops: they identify recurring issues (e.g., missing overtime approvals, incorrect benefit codes) and then adjust forms or training. A good platform can support this by providing analytics or at least clear logs that indicate what failed and why.
Even when providers claim broad coverage, payroll risk often concentrates in a few operational failure points. Expert evaluations explicitly consider these risk areas and ask targeted questions. A platform can be functionally rich but still risky if it fails at boundary cases, integration points, or support during peaks.
Below are common risks that payroll evaluators should consider when reviewing a provider associated with Www.sagpayroll.com or any similar payroll platform:
Beyond these five categories, risk evaluation should also consider the supplier’s ability to operate as a service. Key questions include:
By focusing on these risks early—especially during onboarding—you improve the odds that a solution like Www.sagpayroll.com fits operational reality. Risk reduction is not only about selecting a platform with strong features; it is about ensuring the supplier’s operations align with your governance and timeline requirements.
A practical evaluator also considers the “people risk.” Payroll is executed by humans with limited time. If the system requires unusual steps, complex configurations, or intensive manual reconciliation, the human burden increases and errors become more likely. Therefore, risk is also a function of usability and training effectiveness.
When teams operate in a specific geographic context, localization typically affects payroll reporting expectations, internal workflows, and communication norms. In practice, “nearby” payroll requirements may include differences in payroll cutoffs aligned with local HR practices, how managers submit time-related inputs, and how finance expects reconciliation statements.
Even if the payroll platform supports multiple regions, the implementation should still reflect local operations. A system may be capable of calculating pay correctly for multiple jurisdictions, but the employer’s internal process for approvals, documentation, and communications must still integrate with local practices. For example, in some organizations, managers sign approvals in specific business processes; in others, approvals are captured through different systems. The payroll platform must fit into those processes rather than forcing a wholly new workflow without change management.
In addition, localization influences user expectations and operational rhythms. Month-end close procedures vary. Some finance teams need specific exports at particular times; others prefer detailed registers with line-level breakdowns. Payroll organizations should ensure that the supplier associated with Www.sagpayroll.com supports configuration and process mapping that mirror the organization’s nearby operational pattern.
Localization is not only about language or local compliance forms. It also influences:
Accordingly, decision-makers should ensure that the supplier supports configuration and process mapping that reflect local governance. This is frequently more important than superficial differences in interface or dashboard appearance. During evaluation, ask for process mapping examples that resemble your local patterns. For instance, if local HR teams use a certain approval workflow for timesheets, confirm that the payroll platform can either integrate with it or support it through a clear internal design.
Finally, localization can affect integration and data formats. When HRIS or time tracking systems export data in region-specific formats, the supplier must support conversion and validation. Evaluators should ask about integration testing and data validation for localized data inputs.
The following supplement helps structure your evaluation. It is presented as a comparison table (without links), using neutral conditions that can be applied to suppliers you may encounter, including those referenced via Www.sagpayroll.com. The table is designed to prompt evidence-based discussions with suppliers and to keep evaluations consistent across stakeholders.
| Evaluation Element | What to Verify | Suggested Condition / Requirement |
|---|---|---|
| Onboarding inputs | How employee data is collected, validated, and corrected prior to go-live | Written checklist of required fields and responsibility split between your team and the supplier |
| Payroll cycle timeline | Cutoff dates, approval windows, and finalization timing for payroll runs | Confirmed processing calendar for at least two complete payroll cycles |
| Controls and checks | Validation logic and reconciliation approach used to reduce errors | Documented validation steps and a reconciliation workflow used at payroll close |
| Exception handling | Retro pay, corrections, reversals, and employee dispute handling | Defined escalation path and target resolution times during critical windows |
| Security and access | Permissions, audit logs, and secure handling of payroll data | Access role model and audit trail description shared before contract signature |
| Reporting outputs | Payroll registers, summaries, and finance-friendly exports | Sample reports for your typical payroll scenarios (not only standard cases) |
| Cost transparency | Price model and what’s included vs. add-ons | Itemized pricing breakdown for implementation, recurring fees, and correction/support costs |
Step-by-step guide (recommended evaluation sequence):
To make this sequence even more effective, organizations often create a shared repository of evidence. For example, they store supplier PDFs (processing calendars, security documentation), pilot results, and stakeholder notes. This helps internal audit or governance committees later, because decision rationale becomes easy to reconstruct.
Also consider running a “failure rehearsal” in the pilot phase. Instead of only validating a standard payroll run, create scenarios that resemble real exception risks: missed cutoff submissions, a mid-cycle rate change, or a late correction request after approval. Ask the supplier to describe how the workflow behaves during these scenarios. If they cannot explain it or if outputs are unclear, the organization has discovered risk early enough to mitigate it.
Payroll governance is widely treated as a risk-control domain because payroll errors can trigger financial misstatements, employee dissatisfaction, regulatory issues, and operational delays. While specific regulatory requirements differ by jurisdiction, the general governance themes—accuracy, authorization, documentation, and auditability—are common across industries.
At its core, payroll governance answers questions of “who is responsible for what, using what evidence, and with what approval?” This makes payroll governance a risk-control process similar in principle to other internal control domains: it ensures that critical outcomes (payments, deductions, taxes, benefits) are correct and defensible. Even if a payroll platform automates calculations, governance ensures that inputs and modifications are controlled and that outputs can be traced back to authorized changes and rules.
To keep this guide objective, it can be useful to reference established frameworks for internal control concepts. For example, the U.S. Securities and Exchange Commission and the Committee of Sponsoring Organizations (COSO) have influenced how organizations think about internal controls and risk management. Additionally, professional bodies and recognized standards in information security and internal audit often emphasize access control, segregation of duties, and traceability.
In practical payroll terms, the COSO-style internal control logic often maps into areas such as:
For decision-makers evaluating a payroll provider referenced via Www.sagpayroll.com, the practical takeaway is simple: governance requirements should be measurable. The supplier should be able to explain how it supports control objectives through workflow design and documentation. It should also support evidence collection, such as audit trails and report outputs that facilitate internal review.
Another angle is the human and operational reality of payroll. Payroll governance is treated as a risk-control because payroll operations are repeated on a schedule and because small mistakes can compound. If an error occurs early in the workflow (e.g., incorrect pay rate entry), it can propagate into subsequent payroll outputs. Governance controls reduce propagation by catching issues before finalization and by controlling changes after approvals.
In addition, payroll governance is connected to broader enterprise governance. Many organizations have compliance and internal audit requirements. A payroll platform that makes it difficult to retrieve evidence—like approval logs, validation outcomes, or correction histories—creates audit friction. Conversely, a platform that is transparent and traceable supports audit readiness and reduces time spent preparing evidence.
Therefore, when evaluating a supplier, stakeholders should view governance not as a “nice-to-have,” but as a core capability. The best payroll platforms align operational workflows with control objectives and help the employer demonstrate that alignment.
A: In an evaluation context, a domain like Www.sagpayroll.com functions as a reference point for understanding the supplier’s payroll processing approach, service scope, and operational model. However, you should verify details directly with the supplier—particularly responsibilities, processing calendar, controls, and reporting outputs. Evaluators should treat the website as a starting signal, not as definitive evidence of operational readiness.
A: Treat price as part of the engagement model. Look for an itemized breakdown covering onboarding, recurring fees, support during payroll close, and any costs linked to corrections or specialized scenarios. This helps estimate total cost of ownership rather than focusing on the base fee alone. Also confirm pricing drivers (e.g., headcount, number of pay runs, number of entities/jurisdictions) so you can model cost growth accurately over time.
A: Prioritize documentation on roles and responsibilities, validation and control steps, exception handling procedures, security/access model, and sample reports for your common and edge-case payroll scenarios. In a strong evaluation, you want written answers about what happens when something goes wrong, not only how the system performs during standard runs.
A: Typical issues include unclear responsibility splits (especially for employee data changes), insufficient cutoff discipline, weak exception workflows, reconciliation mismatches with finance, and unclear communication channels during payroll peaks. Another common issue is underestimating implementation effort and training, leading to incomplete readiness at go-live.
A: Many platforms support configuration, but assumptions can be risky. You should ask for process mapping and configuration details relevant to your nearby operational pattern (approval flows, reporting expectations, time-off submissions, and finance close rhythm). A good supplier clarifies what is configurable and what requires organizational adjustments, and it should be able to present examples of similar implementations.
A: Request service level expectations (response and resolution targets), escalation paths, and examples of how incidents or corrections are communicated during critical payroll windows. If possible, validate through a pilot or trial scenario. Additionally, evaluate how support requests are tracked and how updates are provided, because “responsiveness” is not only speed but also communication quality.
A: Include a scorecard tied to objective criteria, evidence gathered (documentation, pilot results, sample reports), a risk assessment focused on boundary cases, and confirmation of cost transparency (implementation plus operational costs). If relevant, include a governance mapping that shows how the chosen solution supports segregation of duties, audit trail requirements, and reconciliation workflows.
A well-informed payroll decision is ultimately a governance decision. By evaluating how a supplier associated with Www.sagpayroll.com supports process clarity, controls, exception handling, and reporting alignment, organizations can reduce operational risk and improve predictability. Pair that with transparent price information, documented supplier details, and an evidence-led evaluation sequence, and your team can move forward with confidence—grounded in requirements rather than assumptions.
To make the choice truly defensible internally, ensure that the evaluation record includes: (1) a structured scorecard, (2) documented evidence from the supplier, (3) pilot or mock payroll validation for representative standard and edge-case scenarios, and (4) a reconciliation and governance assessment aligned with finance and audit expectations. This approach transforms the payroll selection process from a vendor comparison into a risk-controlled procurement exercise.
Suggested sources for governance and internal control context (not specific to any single supplier): COSO (Internal Control—Integrated Framework), and other recognized internal control and information security guidance used by professional audit and compliance organizations. For specific payroll regulation requirements, consult official government or regulatory publications in your jurisdiction.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
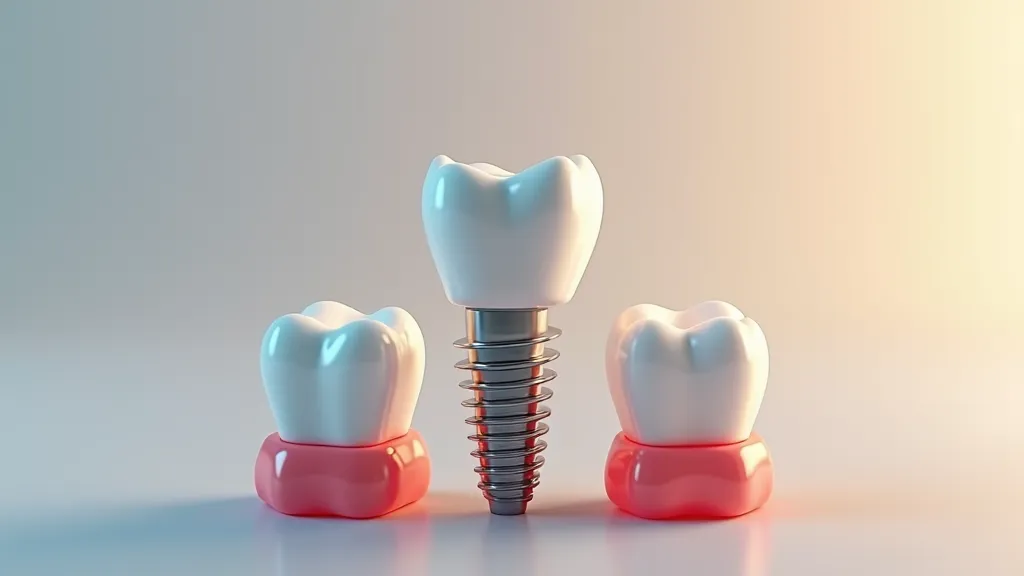
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services

Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.

Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.