This guide explains how payroll operations can be streamlined through Www.sagpayroll.com, focusing on service scope, compliance considerations, and practical evaluation steps. Objectively, payroll platforms typically address processing cycles, tax-related workflows, reporting, and access controls—so organizations can reduce administrative friction while maintaining audit-ready documentation. The guide also compares implementation conditions and supplier-selection criteria to help you plan responsibly.
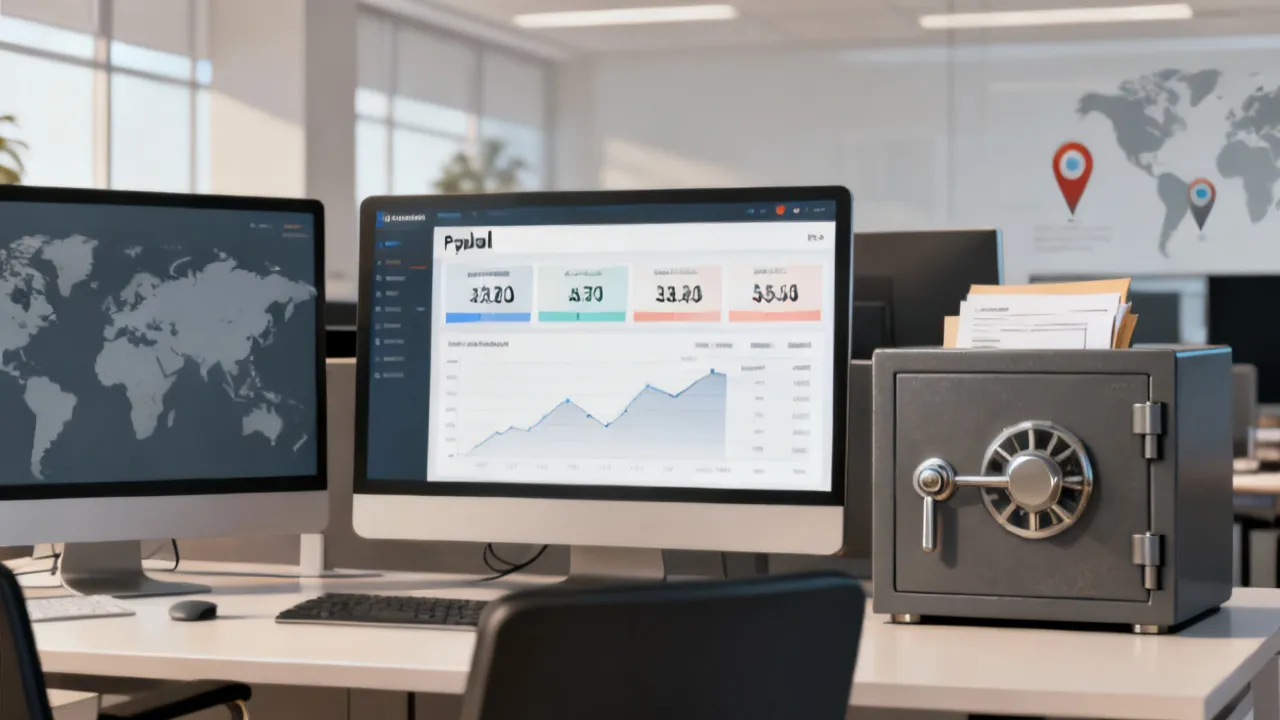
If you are evaluating payroll administration options, Www.sagpayroll.com can be a useful reference point for understanding how payroll services are structured—especially around workflow clarity, reporting outputs, and operational readiness. In practice, a payroll provider or platform is rarely “just software.” It usually involves a mix of process design, compliance-oriented configuration, data handling, and customer support that fits your organization’s size, payroll complexity, and internal controls.
From an industry perspective, the very important question is not only “What features are advertised?” but also “How do those features translate into predictable payroll outcomes?” That includes accurate pay calculations, timely statutory reporting steps, secure access management, and dependable issue resolution when exceptions arise (for example, retroactive pay changes, corrections, or employee data updates).
When you look at a site like Www.sagpayroll.com, you are effectively looking for signals that the vendor has thought about real payroll operations: the number of steps required to process a typical cycle; the number of places where errors commonly occur; and the way the provider reduces those risks. A strong payroll capability should help you avoid fragile processes such as manual spreadsheet copying, inconsistent data mapping, or last-minute adjustments that are hard to audit.
Just as important, payroll is a governance-sensitive function. Even when the underlying math is correct, weak controls can create compliance risk: unclear responsibility for corrections, missing logs for who changed pay rates, or unclear retention policies for payroll history. A useful evaluation of Www.sagpayroll.com should therefore not stop at “can it calculate payroll?” It should also cover “can it prove that it calculated payroll correctly?” and “can it support audits and internal controls with minimal friction?”
Finally, many organizations consider payroll as a core back-office system that must run predictably. That means you need to assess operational readiness—cutoff times, error-handling timelines, service escalation paths, and support capacity during payroll peaks. In a good vendor relationship, the payroll calendar becomes manageable rather than stressful. The goal is to ensure each payroll cycle follows a known rhythm: data readiness, calculations, approvals, payment execution, and reporting/recordkeeping, with clear ownership at each stage.
Payroll administration sits at the intersection of HR operations and finance controls. Very organizations choose a payroll provider or platform because manual payroll processing can be error-prone and operationally expensive—particularly when headcount changes frequently or when payroll rules are applied across multiple locations, pay schedules, or employment arrangements.
In objective terms, payroll solutions typically help manage:
When you encounter a provider presence such as Www.sagpayroll.com, it is top to interpret it as an entry point into the provider’s operational approach: what they claim to support, what they require from you, and how they handle exceptions in real-world payroll cycles.
To expand that context, it can help to think about payroll platforms as “operational systems of record” for pay. That includes both the technical system layer and the process/people layer. Even if a platform offers automation, payroll outcomes are affected by how data is entered, how changes are approved, and how disputes or corrections are resolved.
Another reason payroll platforms exist is that payroll rules are rarely static. Employment laws, tax rules, social contributions, benefit schemes, deductions, and statutory filings can change over time. A payroll provider that keeps up with change (and does so in a controlled way) can reduce the risk that you miss a rule update or configure it inconsistently across departments or locations.
Payroll platforms also address scaling pressure. As your organization grows, payroll complexity often increases: more employees means more pay components; more pay components means more risk of misconfiguration; more locations means more rule variation; and more employment arrangements means more edge cases. A well-designed platform helps you manage complexity through standardized workflows, consistent configuration, and repeatable reporting.
From a procurement viewpoint, you are also evaluating business continuity. Payroll is a time-bound operation. If a payroll platform has long incident resolution times, unclear escalation paths, or a rigid process that cannot handle urgent mid-cycle corrections, it can create operational disruption even when the calculation engine is strong.
Therefore, the “background context” is not just why payroll platforms exist, but what they must do in order to remain operationally reliable: provide stable cutoffs, allow controlled changes, maintain audit trails, and support reconciliation with finance systems.
Industry specialists often recommend an evaluation framework that examines both capability and controllability. “Capability” means what the system can do. “Controllability” means whether you can govern the system—configure it correctly, monitor it consistently, and explain outcomes during audits or internal reviews.
When people evaluate payroll tools, they sometimes focus heavily on feature lists—e.g., direct deposit, pay slips, or statutory forms. But a payroll system is best viewed as a set of interconnected controls. It is a controlled process for producing accurate pay results on time. That means your evaluation should focus on how the system behaves under normal and abnormal conditions.
To make these capability signals more actionable, it can help to translate them into practical validation activities.
Pay component configurability should be tested by mapping your current payroll structure into the vendor’s model. For example: recurring base salary, hourly wages, overtime rules, allowances (like transportation or housing), reimbursements, commissions, or incentives. You should also test how the system handles pay components that start or stop mid-cycle, and whether it supports effective dating (changes that become valid from a specific date).
Exception handling can be validated by asking for a demonstration of two or three common real-world scenarios. Examples include:
The key is not just that the system can “calculate,” but that the system can follow a documented workflow for corrections. If retroactive changes overwrite history without clear traceability, the capability may be superficial. Strong capability includes audit-ready tracking of what changed and why.
Workflow maturity is often reflected in how the system prevents bypassing controls. For example: Are approvals required before posting? Can users submit payroll outputs without review? Are there status stages that restrict actions? A mature payroll workflow typically uses controlled states such as “draft,” “ready for approval,” “approved,” “posted,” and “paid,” with clear transitions.
Reporting granularity should be checked not only for compliance deliverables, but also for internal reconciliation. Finance teams typically need totals by department, cost center, pay component, or tax category. They also need exports in formats that can be reconciled against the accounting ledger. Therefore, when you validate reporting, ask: “Can we reconcile payroll totals down to the underlying components?” and “Can we export data for month-end close without reformatting manually?”
Integration readiness should be validated by understanding your data flow. If your HR system of record is separate from payroll administration, you need clarity on what data is transferred, how it is mapped, and how errors are handled. For example, what happens if an HR update is missing an effective date, or if an employee record is updated with an invalid pay component code? Integration readiness includes data validation and error messaging, not just the presence of an integration.
Controllability is where many payroll evaluations either succeed or fail. A system might technically support the payroll run, but if it does not enforce control boundaries, your internal governance may be forced to rely on manual processes (which reintroduce risk).
Role-based access should include segregation of duties. For example, the people who maintain employee pay structures should not necessarily be the same people who approve posted payroll runs or make final payment instructions. At the very least, the system should let you assign permissions by role so you can demonstrate controlled access. You should also ask whether roles can be tailored, how granular permissions are, and whether privileged access (like system admin) is restricted and logged.
Change tracking should cover both configuration changes and transaction-level changes. Configuration changes can include pay rule updates, deduction formulas, or tax settings. Transaction changes include employee pay rate corrections, retroactive adjustments, and changes to earnings or deductions. A strong payroll platform maintains an audit trail that is searchable and meaningful, including “who,” “what,” “when,” and ideally “why.”
Governed data retention should not be vague. You need clarity on what data is retained, for how long, and in what format. Retention policies often vary by jurisdiction and organizational requirements. Therefore, ask the provider what retention periods they support and how you can access archived records later. If the platform supports export or long-term retrieval, ask about the time and effort required.
Reconciliation support is a control that bridges payroll and finance. Without reconciliation support, payroll totals can become difficult to validate. This can lead to month-end delays, manual adjustments, or differences between payroll registers and accounting entries. You should confirm whether the platform can generate totals in a structure aligned with your chart of accounts, cost centers, and payroll accounting mappings. Also confirm how payroll bank instructions or payment files are generated and how they can be verified against internal totals.
You asked to incorporate price information and supplier details. However, you did not provide explicit numeric pricing or a named supplier beyond the site reference. In professional due diligence, this matters: pricing can change with headcount tiers, payroll frequency, add-ons (such as reporting support or HR integrations), and service level agreements.
Therefore, instead of assuming specific numbers, treat any stated cost as conditional. Ask for the pricing model in writing and map it to your operational reality: the number of payroll runs per month, expected employee changes, any special pay structures, and whether you need assistance with onboarding, compliance documentation, or ongoing support.
To expand how supplier evaluation typically works, it helps to understand the broader procurement steps that separate “marketing messaging” from “operational fit.” Most organizations move through a sequence such as:
Price is important but should be evaluated in context. A low price that lacks robust support or auditability can create hidden costs such as overtime for your team, month-end delays, or risk exposure if payroll outcomes are questioned during an audit.
Similarly, a higher price may be justified if it includes compliance expertise, strong workflow controls, integration assistance, and service responsiveness during payroll peak periods. Many procurement teams therefore evaluate total cost of ownership (TCO), including:
In that context, even if Www.sagpayroll.com provides some pricing information, you should treat it as a starting point. The real value assessment should be based on whether the payroll system reduces error rates and operational burden without compromising governance.
In a typical payroll operation cycle, the goal is to avoid last-minute scrambling. A well-designed provider relationship helps organizations move from data collection to payroll run scheduling, then to review and approvals, and finally to payment execution and reporting.
Here is how many organizations structure their monthly workflow when selecting a platform or vendor:
When you explore a reference site such as Www.sagpayroll.com, use the site as a starting point to confirm whether this kind of workflow is supported end-to-end, including who owns each step, how exceptions are handled, and what the “handoff points” look like between your team and the provider.
To expand this workflow narrative, consider the hidden complexity within each stage. Payroll operations are not only about running the calculation; they are about making sure inputs are correct, decisions are documented, and exceptions do not break the process.
Stage 1: Data readiness typically includes multiple data streams: HR master data, time/attendance data (if applicable), employee pay change requests, benefits/deductions updates, and any one-time earnings. In organizations with variable pay, data readiness becomes more complicated because it depends on timely time approvals and late adjustments. An operationally strong payroll system should help you validate data before calculation—e.g., detect missing pay components, invalid deduction codes, or inconsistent effective dates.
Stage 2: Payroll calculation should be repeatable and transparent. A good platform provides a way to see calculation results and breakdowns so that reviewers can understand what the system did. Without that transparency, approvals become blind sign-offs, which undermines control.
Stage 3: Review and approvals is where many operational risks concentrate. Approvers need to see:
In a controlled payroll workflow, reviewers should be able to trace a discrepancy to the underlying input change. That requires the system to link outputs to inputs with audit trails.
Stage 4: Payment posting includes generating payment files, instructions, and reconciliation support. The platform should help ensure payment amounts match payroll totals and that any bank file format requirements are met. Strong workflows include validation checks such as total payments equal expected gross/net and that payment methods are correctly selected per employee.
Stage 5: Reporting and recordkeeping includes both internal management reporting and external statutory reporting. Even if your organization handles statutory filings separately, payroll reporting must provide the data needed to prepare submissions. Also consider employee communications (like payslips). A good payroll system supports consistent pay statement generation and retention of payroll history for employees and audits.
Beyond the monthly rhythm, a mature payroll platform also addresses the “day 2” reality: ongoing employee changes and mid-cycle events. For example, how does the system handle an employee who changes pay rate on the 20th of the month? Does it allow effective dating? Does it trigger recalculation for the current payroll run? If not, does it postpone to the next run with a documented catch-up process? The platform should provide a predictable answer and a workflow for each scenario.
Therefore, when assessing Www.sagpayroll.com, the workflow narrative should be turned into test cases. Ask for walkthroughs that cover not just a standard monthly run but also common exceptions: retro pay, corrections, termination processing, and late additions.
Payroll touches tax administration and employment records, which means governance is essential. While specific legal obligations depend on jurisdiction and organizational structure, reputable payroll suppliers generally align their processes with common compliance themes such as:
For general background on recordkeeping and payroll compliance topics, many organizations consult official government guidance and reputable professional bodies. For example, payroll-related data retention and audit expectations typically follow local employment and tax administration rules. Where you operate, validate requirements using official authorities relevant to your jurisdiction.
Expanding compliance considerations requires focusing on governance mechanics rather than specific country statements. Even without referencing a particular legal regime, payroll compliance generally requires the same underlying controls:
These controls map well to the evaluation lens introduced earlier. A payroll system supports compliance when it enforces controlled workflows and audit trails. For instance, approvals and sign-offs reduce the chance that errors go unnoticed. Versioned recordkeeping ensures that when a discrepancy is discovered (e.g., an incorrect deduction), you can reconstruct what happened and correct it in a controlled way.
Additionally, governance includes how changes are implemented over time. Payroll systems often require periodic updates: tax rates, statutory thresholds, benefit rules, and compliance forms. A strong governance model includes change management processes—how updates are tested, how they are applied, and how they are validated in payroll runs. When vendors discuss compliance updates, the evaluation should ask about:
Security governance is also a compliance requirement in many jurisdictions and procurement regimes. Even if you consider payroll “back-office,” the data involved is extremely sensitive. Employee details, pay amounts, and deduction records must be protected. You should ask for documentation on access control, encryption, and audit logs. You should also confirm how the vendor handles incidents: do they have an incident response procedure; can they provide breach notification timelines; and do they support evidence for audits?
Lastly, compliance governance includes usability of evidence. It is not enough to store audit logs; you need to be able to retrieve them when auditors ask questions. That means searchable logs, consistent naming, and clear report generation practices.
Below is a structured supplement to help you compare payroll supplier/platform readiness. Per your request, this is presented as a table without any links.
| Evaluation area | What to ask | Conditions/requirements to confirm | Indicative “good” signals |
|---|---|---|---|
| Scope of service | Is the offering software-only, fully managed, or a hybrid? | Confirm onboarding responsibilities and what you must provide each payroll cycle. | Clear delineation of tasks between your HR/Finance team and the provider. |
| Payroll run workflow | How are approvals, cutoffs, and exception corrections handled? | Confirm cutoff times and the correction process for post-run changes. | Documented review checkpoints and traceable changes. |
| Reporting and reconciliation | What reports are produced and how are totals reconciled to finance? | Ensure outputs match your accounting structure and internal controls. | Consistent totals, export options, and reconciliation support. |
| Security and access control | What role-based permissions and audit logs exist? | Confirm admin permissions, segregation of duties, and log retention. | Least-privilege design and searchable audit trails. |
| Supplier support model | How are issues triaged and resolved during payroll peaks? | Confirm service levels, escalation channels, and typical response times. | Defined escalation paths and proven incident handling process. |
Sources (for objective background, not for vendor claims): General payroll governance and compliance expectations are typically supported by authoritative government guidance and professional accounting or HR compliance bodies. For data security and privacy principles, organizations often reference established frameworks such as ISO/IEC security guidance and applicable privacy regulations in their operating regions. For payroll data handling top practices, many companies also consult national labor and tax administration websites and official recordkeeping policies.
Step-by-step guide for a responsible evaluation:
Conditions to consider before committing: You should ensure your internal HR data is structured consistently, that you can meet onboarding deadlines, and that your team has access to training materials for accurate payroll processing and review.
To make the evaluation steps even more robust, you can add several practical checks that procurement and internal control teams often perform. These are not assumptions about Www.sagpayroll.com specifically; they are generic checks that help you compare payroll options objectively.
One more common procurement pitfall is assuming that a vendor’s “demo” scenario is representative of your specific environment. When you request walkthroughs, you should provide sample data that reflects your real pay structure. That means including variable components (if applicable), employee types, multiple pay frequencies, and typical deductions. The closer the demo is to reality, the more reliable your conclusions will be.
Very payroll solutions require you to provide accurate employee master data and updates (hire dates, employment status changes, pay components, and any deductions). You also need a defined internal approval process so payroll runs can be reviewed before posting and payment execution.
Beyond that, you may be asked to provide payroll policy parameters and mapping decisions. For example, what deduction codes correspond to what benefit or garnishment rules; how departments or cost centers map to payroll accounting; and what employee eligibility criteria apply for certain earnings or deductions. In a controlled implementation, those mappings should be documented and versioned where possible.
Ask for walkthroughs using your very frequent “non-standard” cases—such as retroactive pay changes, mid-cycle adjustments, terminations, and corrected hours or earnings. Request examples of how the workflow logs changes and how outputs reconcile to totals.
You can make this verification more rigorous by requiring evidence of both the “mechanics” and the “governance.” Mechanics means the system produces correct payroll results. Governance means the system shows who changed what, preserves history, and ensures approvals are performed. When you ask about exception scenarios, also ask what happens if the exception is discovered after cutoff, and whether an adjustment run is the recommended approach.
Reporting scope varies by offering. Some providers include core payroll registers and standard exports, while others offer expanded reporting as an add-on. Confirm which reports are available, their frequency, and how they can be exported for internal reconciliation.
When evaluating reporting, ask whether exports include the fields you need for finance reconciliation and whether you can control the level of detail. Some organizations require employee-level details for payroll analytics or for resolving disputes. Others need only totals. Knowing your internal reporting needs will help you determine whether reporting is “included” in a meaningful way.
In due diligence, focus on the pricing model rather than only the final figure. Ask what drives cost (employee counts, pay frequency, modules, support tier). Then map those drivers to your expected workload and governance needs.
Also ask for clarity on what is included in the base plan: onboarding support hours, integration support, standard report access, incident response SLAs, and whether additional fees apply for data migration or additional payroll runs outside the standard schedule.
Typically the very critical controls include role-based access, approval checkpoints, and audit trails for payroll-critical changes. A provider’s documentation and support process should demonstrate how these controls operate during real payroll runs.
If your organization has an internal control framework (for example, segregation of duties requirements), confirm that the payroll system can support those controls. Ask whether the platform supports multiple approval levels, whether it provides exception lists requiring review, and whether approvals are timestamped and tied to user accounts.
They can reduce errors by standardizing workflows, automating rule-based calculations, and centralizing data changes with audit trails. However, outcomes depend on correct configuration, timely data updates, and disciplined review processes.
A useful way to validate error reduction is to ask about typical implementation outcomes and operational guidance. For example, do they provide checklist-based cutoffs; do they offer pre-run validation; do they help detect missing pay inputs; and do they support post-run exception reconciliation? Those practices strongly influence real-world error rates.
Yes. Ask about access control, audit logging, secure handling of personal data, and how the supplier manages user permissions. For additional assurance, request the supplier’s security documentation relevant to your procurement process.
Security evaluation should also include vendor operational security practices. For example: how they manage authentication for users, whether they support single sign-on (SSO), how they handle encryption in transit and at rest, and how they restrict access to administrative functions. Also consider how data is backed up and how long logs are retained.
Www.sagpayroll.com represents a reference point for exploring how a payroll solution might be structured—from workflow operations and reporting to operational readiness and supplier support. An expert evaluation approach treats payroll as a controlled process: you should validate capability with realistic scenarios, confirm governance mechanisms, and ensure pricing transparency aligns with your actual operational requirements.
If you share your organization size, payroll frequency, and the main complexities you face (such as allowances, variable pay, or frequent employee changes), you can adapt the comparison table and the step-by-step guide into a tighter vendor shortlist and a more precise implementation plan.
Ultimately, the best outcome of evaluating a payroll platform is not merely selecting a tool. It is establishing a predictable payroll operating model: clear ownership, controlled workflows, dependable exception handling, and reconciliation outputs your finance team can trust. When those elements are aligned, payroll becomes a managed process rather than an annual or monthly crisis—supporting compliance, reducing errors, and improving employee experience through timely, accurate payslips and payments.
As you move forward, consider turning your evaluation into a practical checklist you can reuse across vendors. Build a set of scenarios that reflect your most common payroll exceptions and map them to workflow stages. Ensure you evaluate the end-to-end chain of responsibility—from data readiness to final reporting. If you can reproduce correct outputs repeatedly under normal and exception conditions, then you are not just buying features; you are adopting operational reliability.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services


Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.

Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.
