This guide explains how a payroll platform like Www.sagpayroll.com supports compliant payroll operations for organizations. It objectively outlines what payroll systems typically cover—run preparation, tax and deductions handling, employee master data, audit readiness, and controls—then adds a practical comparison table and implementation checklist so decision-makers can evaluate requirements without guessing.
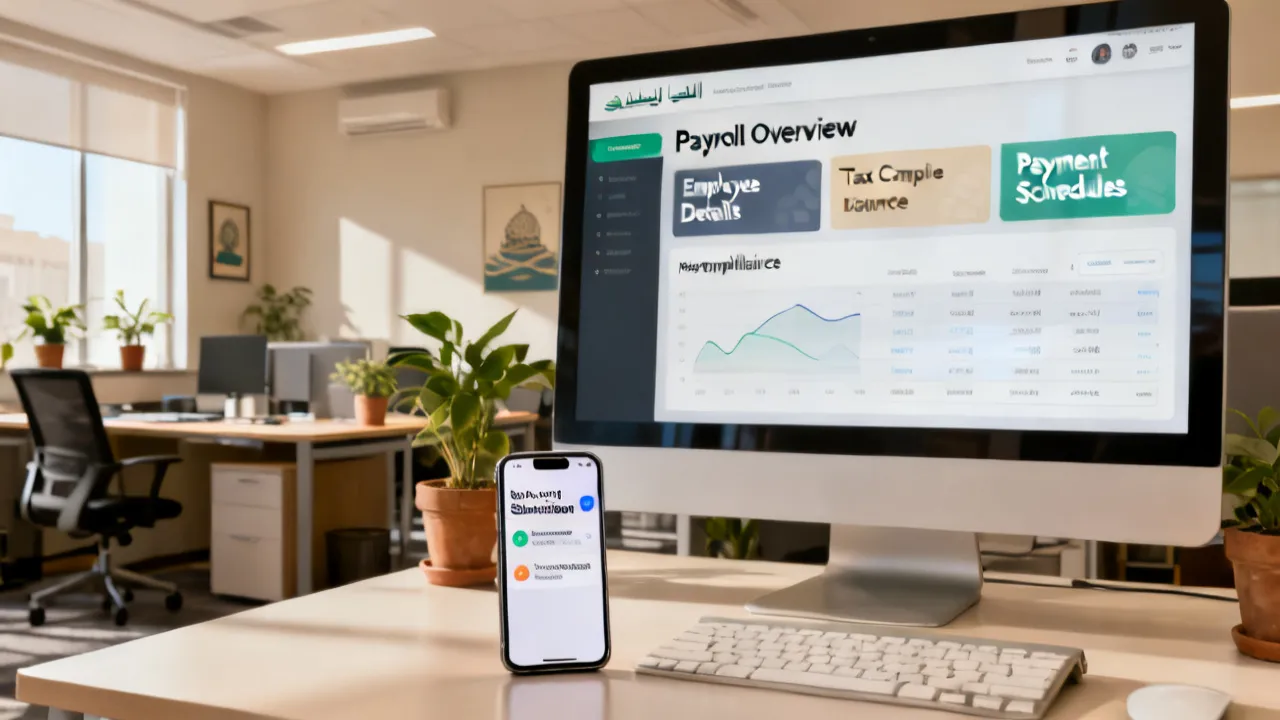
Payroll is not just a monthly payment cycle—it is a controlled process that must remain accurate, traceable, and defensible. When organizations evaluate a payroll service such as Www.sagpayroll.com, the focus should be on whether the platform can support end-to-end payroll compliance workflows: structured data management, controlled payroll runs, clear reporting, and reliable employee records that can be audited when needed.
In practice, payroll platforms are judged by how consistently they can transform employee input (hours, allowances, deductions, status changes) into payroll outcomes (payslips, summaries, and statutory reporting artifacts), while enforcing role-based controls and maintaining a clear trail of changes. A payroll run is not simply “a calculation”; it is the culmination of data readiness, rules configuration, governance approvals, and output production. Every step can introduce risk, and compliance requires that risk be managed systematically.
Consider the operational reality most companies face: HR teams update employment details and compensation arrangements; timekeeping systems deliver hours worked; finance teams reconcile totals to the general ledger; and employees expect timely, correct pay with understandable payslips. If the payroll system is weak in even one link—data entry validation, cut-off discipline, version control over pay rules, or the retention of evidence—then payroll quality becomes inconsistent. Over time this inconsistency can surface as underpayment, overpayment, incorrect deductions, missed filings, or inability to respond effectively during internal or external audits.
From an audit standpoint, payroll should behave like an evidence-producing workflow. That means the organization must be able to answer questions such as: Which employees were included in payroll run X? What pay elements and rates were used at that time? Who approved payroll inputs? If corrections were made, what triggered them, what changed, and how was the impact documented? An audit-ready payroll system supports this line of inquiry not through manual explanations, but through structured logs, reproducible calculations, and organized archival of run outputs.
Therefore, when assessing Www.sagpayroll.com (or any payroll solution), it is helpful to frame the evaluation around measurable operational capabilities: does the platform support controlled “pay runs” as repeatable processes? Does it maintain accurate employee master data and ensure the payroll uses the correct data version? Does it preserve an audit trail of changes and approvals? Does it generate reporting artifacts in formats that finance and compliance teams can readily use? If these elements are present and well-governed, payroll becomes a reliable business function rather than a recurring source of stress.
Payroll compliance is the sum of many smaller requirements that organizations must meet across time. While exact obligations vary by industry and jurisdiction, very payroll programs revolve around consistent principles. Compliance is best understood as an operational discipline: the organization establishes rules, ensures correct application, retains evidence, and responds to exceptions in a controlled way.
While specific legal and regulatory requirements vary widely, payroll compliance frameworks usually include these core categories:
From an industry perspective, a strong payroll solution treats payroll as a repeatable workflow rather than a one-off calculation. That distinction becomes crucial during audits, when organizations must show that payroll outcomes followed documented processes and verifiable inputs. When payroll is treated as a repeatable workflow, the organization can confidently improve controls—without rewriting operations from scratch each pay period.
Compliance, however, is not only about avoiding fines. It is also about maintaining employee trust. When employees can receive correct payslips and understand the reasons behind changes in their pay, morale improves and HR reduces time spent on disputes. A payroll platform that supports transparent calculations and traceability supports both compliance and employee experience.
When exploring Www.sagpayroll.com, decision-makers typically look for how the platform integrates with day-to-day HR and finance operations. A professional payroll environment often aligns with these operational checkpoints:
Even without assuming specific features, these are the capabilities that evaluate very payroll platforms: accuracy, process control, reporting clarity, and administrative usability.
To ensure Www.sagpayroll.com (or any solution) fits your workflow, it’s useful to map the “journey” of data and decisions. Data journey questions include: Where do pay elements originate? How are they validated? How do retro changes propagate? Decision journey questions include: Who decides to process a payroll run? Who approves exceptions? What is the process when an employee’s termination date changes after payroll cut-off?
When the platform supports these journeys, it helps prevent the most common operational problems: mismatched data, inconsistent approvals, unclear responsibility, and late-stage fixes that break reconciliation. A payroll system should not merely compute; it should coordinate.
Payroll vendors and service pages can differ widely in how they describe capabilities. To compare services objectively—especially when you’re evaluating Www.sagpayroll.com—use a framework based on operational outcomes rather than promotional claims.
Here are practical evaluation dimensions that experienced HR/finance leaders commonly apply. Each dimension should be tested with questions, demonstrations, and—where possible—structured trials:
Approach the evaluation like you would a finance control review: identify risks, confirm controls, then validate outputs through testing. Avoid relying solely on “feature lists.” Instead, ask for examples and proof: run a scenario where an employee’s bank details are corrected mid-cycle; then show how the system prevents accidental reprocessing or misapplication of changes.
A marketing-heavy evaluation often fails because it doesn’t require the vendor to demonstrate the operational “how.” The goal of your evaluation should be to verify that the platform supports repeatable controls under realistic conditions. This is particularly important for compliance, where the organization must show not just results, but also how those results were produced.
One practical strategy is to write your evaluation as a set of “control questions.” For example: “Who can edit pay rates after cut-off?” “How do we lock a payroll run once approved?” “Can we generate an audit report showing exactly which pay elements were used and which rules applied?” Then ask the vendor to respond with demonstrations or documents that map to each control question.
Your request mentions price information, but no specific price values were provided. Instead of guessing, the responsible approach is to evaluate total cost factors that typically influence payroll pricing models. When you obtain figures from Www.sagpayroll.com or a related sales conversation, ask for itemized components and clear assumptions.
Common cost drivers include:
Procurement teams generally benefit from requesting a written quote that includes what is included and what requires additional fees. This reduces the risk of budget surprises after go-live. It also helps ensure the final deliverable matches the expected compliance workflow.
To assess costs responsibly, ask the vendor to clarify assumptions and boundaries. For example:
In many payroll projects, the most expensive outcomes come not from the subscription itself, but from rework—when a vendor solution doesn’t support a critical compliance workflow and the organization must compensate with manual steps. A strong approach is to price the solution based on the operational outcomes you need. If you require audit-ready exports or role-based approvals, treat those requirements as must-haves and confirm how they are delivered and maintained.
Industry practitioners usually recommend implementing payroll systems with disciplined governance. A practical rollout reduces rework during early pay periods and strengthens confidence among HR and finance teams.
Key implementation practices include:
This is where a platform such as Www.sagpayroll.com should prove its value: it should support your process rather than create ambiguity. Implementation success is less about “going live” and more about “becoming dependable.” You should be able to answer, on demand, how any payroll figure was produced.
A mature implementation typically uses staged approaches:
During implementation, document your internal procedures. A payroll platform may automate many steps, but compliance also depends on the organization’s process documentation: who approves, what evidence is retained, and how exceptions are handled. A good system helps you capture evidence; it doesn’t replace governance entirely.
The table below is a supplement to the main narrative. It provides a structured comparison method, including a source column, a step-by-step guide, and the conditions/requirements typically expected during evaluation and implementation. (No links are included in the table.)
| Aspect | Source (What to Reference) | Step-by-Step Guide | Conditions / Requirements |
|---|---|---|---|
| Payroll capability fit | Vendor documentation, product configuration guides, and your internal payroll policy documents |
1) Map your current payroll workflow to system features 2) Identify where calculations occur and who approves them 3) Confirm the handling of exceptions (corrections and retro changes) |
Clear definition of payroll inputs (allowances/deductions) Agreed governance for payroll run approvals |
| Data readiness | Employee master data templates, HR records, and payroll input catalogs |
1) Perform a data audit for completeness and consistency 2) Standardize naming and identifiers 3) Validate data migration outcomes using sample employees |
Data quality thresholds (e.g., required fields) Defined owner for data correction |
| Controls and audit trail | Security standards, internal control framework, and audit evidence requirements |
1) Verify role permissions and change approvals 2) Test whether prior run outputs can be reproduced or explained 3) Document how audit evidence is exported or retained |
Documented evidence retention expectations Access control aligned with segregation of duties |
| Reporting and reconciliation | Finance reconciliation procedures and reporting templates |
1) Identify required reports for HR and finance 2) Validate that totals match accounting reconciliation fields 3) Run parallel outputs during a controlled trial period |
A reconciliation checklist agreed by HR and finance Defined acceptance criteria for report accuracy |
| Operational readiness | Implementation plan, training materials, and support SLAs (service-level agreements) |
1) Conduct role-based training sessions 2) Run dress rehearsals for the payroll calendar 3) Confirm escalation paths for issues during cut-off periods |
Training attendance confirmation Support coverage during initial payroll cycles |
To avoid costly rework, confirm the following items before committing to a payroll platform (including evaluations tied to Www.sagpayroll.com):
Confirming these items early ensures your project avoids the most common “implementation surprises.” These surprises often occur when a system works well in demonstrations but fails to support critical workflows under real operational timelines. A compliance-first mindset requires early validation of exceptions and controls.
From an industry specialist’s viewpoint, payroll projects usually succeed or fail due to a few predictable areas. The goal is not to “buy software,” but to establish a dependable control system around payroll data and decisions.
Payroll failure points are frequently less about incorrect computations and more about insufficient governance. Even when calculations are correct, the organization may still fail compliance expectations if it cannot prove the process used. Therefore, the prevention strategy must address both operational accuracy and evidence creation.
When employee master data is incomplete or changes are made by multiple teams without a single source of truth, payroll outcomes can become unreliable. The prevention method is simple but strict: define ownership and standardize update procedures.
To reduce data mismatches, you should address questions such as:
Organizations sometimes attempt to solve data mismatches with additional spreadsheet reconciliations. While that might temporarily reduce errors, it can weaken controls by adding manual steps that are difficult to audit. Instead, a payroll platform should be configured to validate required fields and enforce controlled updates. Additionally, define a single ownership path so that the organization can trace data lineage.
Another practical measure is to implement data quality checks before each payroll run. A system can flag missing bank details, missing tax configurations, or inconsistent employment status. These checks should be part of cut-off procedures rather than performed ad hoc.
Many organizations begin with spreadsheets to “fix” payroll errors. Over time, this can weaken controls. A payroll platform should enable controlled corrections with an audit trail, not encourage manual overrides that are hard to reconcile.
Manual corrections create multiple risks:
Instead of spreadsheets, use system-supported correction workflows. For example, retro pay should follow defined adjustment procedures that record the reason, the effective date, and who authorized the correction. If spreadsheets are needed for temporary transition, they should be minimized and documented, and any final figures should be reconciled back to system outputs with clear evidence.
A strong approach is to define an escalation path. When payroll errors are detected, the organization should have a documented method: identify root cause, determine whether the fix should be an adjustment, reversal, or correction run, and then approve it using established controls.
Payroll operations require calendar discipline. If approvals or input deadlines are repeatedly missed, payroll administrators spend time chasing last-minute adjustments, increasing the probability of mistakes. A good solution should support governance and cut-off workflows.
Late cut-offs often happen for understandable reasons—HR might receive information late, or leadership may request exceptions close to processing dates. But compliance requires that exceptions be handled intentionally rather than through informal late changes. The prevention strategy includes:
Additionally, if the payroll platform supports “approval stages,” use them. Approvals should be tied to business logic: for instance, approving time inputs is different from approving pay rule changes. A system that collapses approvals into one stage often fails the control objective.
Even if payroll calculations are correct, unclear reporting can stall finance reconciliation. Validate reports early—during a structured trial—so finance knows exactly what to trust and how to reconcile totals.
Reconciliation usually depends on consistent breakdowns. Finance often needs:
When outputs are confusing, finance teams may revert to manual cross-checks, which reintroduces risk. A compliance-first payroll solution provides outputs that are structured, consistent, and explainable. During evaluation of Www.sagpayroll.com (or any payroll platform), insist on sample reports and test them with your own reconciliation templates.
One effective approach is to create a reconciliation checklist for a typical run and a typical exception run. Test whether each report field needed by finance exists and matches expected categories. Where differences appear, address them during configuration rather than during month-end.
Www.sagpayroll.com appears to be associated with payroll services and/or payroll platform capabilities. Organizations typically use payroll tools to manage employee data, calculate payroll outputs, generate payslips and summaries, and maintain records that support governance and reporting workflows. In practice, such platforms help organizations coordinate HR inputs and produce outputs for employees, finance reconciliation, and statutory reporting.
Use a controls-based approach: verify role permissions, approval workflows, the audit trail for changes, exception handling (retro pay, corrections), and reporting outputs that help reconcile and evidence payroll runs. Focus on operational proof rather than marketing statements. Ask for demonstrations of specific scenarios that reflect your compliance needs—especially scenarios involving corrections, mid-cycle status changes, and data updates after cut-off.
Yes. Very payroll implementations require standardized employee master data (e.g., identifiers, employment status, compensation elements) and a defined catalog of allowances and deductions. The exact fields depend on your organization’s payroll structure and operating model. In addition to basic data, organizations also typically need payroll rule configurations: how overtime is calculated, how deductions are applied, how tax settings map to employee categories, and how effective dates behave for retro adjustments.
Stability typically depends on governance and training. Plan a pilot or parallel run if possible, enforce payroll cut-off timelines, and ensure HR/finance ownership for approvals and data corrections is clearly assigned. Stability also depends on how well exception processes are defined and used; many payroll instabilities originate from unclear processes for handling late or incorrect inputs.
Request an itemized quote covering employee volume, included modules, onboarding and data migration scope, support coverage, and any ongoing fees. Confirm assumptions in writing so budgeting reflects operational reality. Also ask about costs related to compliance outputs and reporting customization, integration maintenance, and change management for future pay rule updates.
Yes, common risks include data migration errors, incomplete configuration, and unclear cut-off/approval behaviors. The mitigation is to run structured testing scenarios and establish clear escalation paths during early cycles. A stabilization period with enhanced support and clearly defined incident handling can reduce the impact of early errors and help the organization build confidence in the new workflow.
When researching payroll controls and audit readiness, it is useful to consult authoritative guidance from established bodies. For example:
Because the provided prompt does not include specific jurisdictional compliance requirements or a verified numeric performance claim, this guide avoids unverified statistics and focuses on repeatable, control-oriented evaluation practices. For the final compliance requirements relevant to your organization, consult local legal and statutory guidance and align with internal audit expectations.
Evaluating a payroll service connected to Www.sagpayroll.com should be grounded in process control, reporting clarity, and audit readiness—not only in feature lists. By comparing solutions through structured steps, confirming conditions and requirements early, and testing edge cases during implementation, organizations can build a payroll operation that remains accurate, traceable, and resilient across pay cycles.
Ultimately, payroll compliance is achieved through repeatable workflows: controlled input management, governed payroll runs, evidence-rich outputs, and disciplined exception handling. When you treat payroll as a compliance process rather than a periodic task, you reduce risk, protect employee trust, and strengthen the organization’s ability to respond to audits and reporting obligations with confidence.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services


Smart Strategies to Slash Costs on Your Roof Replacement Endeavor
Opening Remarks: Smart budgeting doesn't mean cutting corners on quality. This guide will delve into cost-effective approaches for roof replacement that maintain high standards.

Unlocking the Secrets of Preschool: Your Ultimate Guide to Early Childhood Education Programs
The significance of early childhood education programs is paramount in shaping the foundational stages of a young child's life. These educational experiences aim to furnish children with a diverse skill set before they face the structured environment of elementary education. Such programs offer a dynamic and engaging atmosphere where children's natural curiosity leads to the broadening of their thought processes. Moreover, they focus on rectifying behavioral patterns and fostering positive principles and routines.
Enhance Your Smile: Essential Gum Care Tips After Teeth Replacement
After getting new dental implants, it's crucial to look after your gums to aid recovery, shield against infection, and enhance the durability and function of the implants. This discussion delves into the key methods and top tips for gum care that are vital to keep your gums robust and healthy after your procedure.
Unlock the Secrets to Championing Fair Pay: A Guide to Fighting for Competitive Nurse Salaries at Your Hospital
To effectively navigate the intricacies of nurse compensation in healthcare institutions, a thorough understanding goes beyond the basics. Strategic advocacy is essential, honoring nursing as a critical profession while also deeply comprehending the economic aspects of healthcare. This article lays out systematic methods to advocate for fair remuneration for nurses, aimed at closing the divide between managerial policies and the realities nurses face daily.
Protect Your Golden Nest Egg: Smart Strategies and Essential Precautions for Securing Your Gold Investments
Investing in gold requires more than just purchase; diligent protection and a strategic mindset are crucial. A secure gold investment is built on thoughtful planning, alert risk management, and the capacity to adapt to changes. We'll explore various ways to protect these investments from the diverse challenges they face.
Unlock Higher Earnings: Master the Art of Leveraging Your Nursing Expertise for a Hefty Pay Raise!
Unraveling the complexity of the payment landscape in nursing isn't for the faint-hearted, yet it's a manageable task with a strategy in place, enhancing one’s prospects for improved salary through skill and knowledge. This delicate dance of upholding patient care while seeking just rewards is a path all nurses must walk. Grasping the elaborate character of the nursing role and what propels one's income forward is crucial. Within this paper, we dissect insightful methods to maximize the impact of your nursing qualifications.
