This guide helps you evaluate Digio Livelo by explaining how the rewards mechanism works, what to check before joining, and what “good fit” looks like for different lifestyles. Objectively, Digio and Livelo are typically discussed in the context of Brazilian loyalty programs, where partners and spending habits influence point accumulation and redemption options.
If you’re considering Digio Livelo, the very important step is to understand how the rewards structure interacts with your routine spending. Before choosing any plan or partner, confirm three things: (1) how points are earned (rates and qualifying purchases), (2) how points can be redeemed (availability, transfer rules, and limitations), and (3) what costs or conditions apply (annual fees, interest rates, membership requirements, and eligibility windows). Doing this upfront helps you avoid common disappointments—such as expecting accelerated point earning for categories that don’t qualify.
From an industry-expert perspective, loyalty programs succeed or fail at the “fit” layer: they deliver value when the customer’s purchase categories, payment behavior, and redemption preferences align with the program’s rules. For many consumers, the top outcome comes from matching the program to realistic usage patterns—e.g., consistent monthly spend, predictable bill payments, and redemption goals that match the program’s catalog and transfer mechanics.
However, “fit” isn’t only about your spending. It’s also about your patience and your planning style. If you prefer instant benefits, but a program requires points accumulation before you can redeem anything meaningful, then the short-term value may feel lower. If you redeem occasionally, but the program uses expiration or inactivity rules, then value can evaporate. If you’re the type who always pays in full, you’ll likely experience a cleaner rewards outcome. If you carry a revolving balance, interest and fees can dilute or completely negate the points value. All of these realities are why you should treat Digio Livelo as a system of rules you can model, not as a single headline offer.
Also consider that loyalty programs change. Terms evolve, partner categories shift, and redemption catalogs rotate. A plan that looks great today can become less attractive later if earn multipliers end or if the best redemptions become more expensive. That doesn’t necessarily mean the program is bad—it means you should periodically reassess the “fit” over time. The goal is to create a sustainable reward strategy rather than a one-time bet.
In Brazil, “Digio” is commonly associated with a digital financial product brand, while “Livelo” is frequently discussed as a loyalty ecosystem that aggregates point-based benefits through partners. When people mention Digio Livelo, they typically mean a rewards arrangement where card usage or financial interactions can be tied to earning points that can later be converted into benefits inside the Livelo environment.
Because loyalty programs evolve, the exact mechanics can change over time. Therefore, the objective approach is to treat the offer as a system of rules—not a single promise. Evaluate the earn/transfer/redemption chain end to end, and verify the current terms directly in the official product page and the program’s rules document at the moment you sign up.
In practice, there are often multiple layers in play. One layer is the financial product itself (for example, a card or account that supports point earning). Another layer is the loyalty platform (Livelo), which provides the catalog, redemption mechanics, and points accounting. A third layer is the partner network that funds promotions and offers inventory. When you understand that chain, it becomes much easier to troubleshoot issues like “I didn’t get points” or “Why can’t I redeem for the option I expected?” In many cases, the answer is not “the program doesn’t work,” but rather that the transaction was excluded, points were pending, redemption stock was limited, or a category cap was reached.
It’s also worth noting that people sometimes use “Digio Livelo” to refer to different variants of offers (e.g., promotions that apply only to certain customers, promotional earn rates for a limited time, or specific ways points are transferred). Without the exact plan name and the date you joined, it’s easy for conversations to mix apples and oranges. If you’re comparing experiences from other customers, always ask: What was the exact offer? When did they join? Which transactions qualified for their points? That context matters because your experience will be governed by the terms active at your enrollment and the transactions you actually make.
Many customers focus on the headline “points” concept, but in practice the effective value depends on:
In expert reviews of loyalty mechanics, the biggest “value leakage” usually comes from assuming that every expense behaves the same. If your spending mix differs from what the program rewards top, your point accumulation may be slower than expected. For example, if the best earn rate is associated with travel partners but you spend mostly on groceries and utilities, then the headline rate won’t reflect your real earning.
To make the earn rate actionable, you should separate the earn rate into components: (a) what kinds of transactions qualify, (b) what payment channel qualifies (online vs. in-store, eligible merchant types, or payment rails), and (c) whether the earn rate is constant or promotional and time-limited. Some programs offer multipliers only for a short onboarding window or only during certain campaigns (for example, seasonal “double points” periods). If you plan around those promotions incorrectly, you’ll feel like the program underdelivered—when in reality you simply missed the campaign window.
Another important factor is whether earn rates apply to the full amount of a transaction or only to the portion above a threshold. Some programs treat taxes, shipping, or certain fees differently. If the program excludes certain elements, the “points per R$” you experience could be lower than what a simplified marketing example implies.
Also watch for exclusions that aren’t always obvious. Some loyalty systems exclude cash-like transactions (e.g., cash advances), certain fees, balance transfers, or transactions that are coded under a category that doesn’t align with the partner structure. If you frequently use your card for actions that might be coded differently than normal purchases (like bill pay through certain channels), your earn results may vary.
Even when points are earned successfully, redemption governs whether the value feels “worth it.” Consider:
Objectively, loyalty ecosystems like Livelo often provide multiple pathways to convert points into benefits. However, the top path is the one that matches your preferences and timing. A program can be “generous” on paper yet offer poor practical value if the very desirable redemptions require significantly more points than you’re comfortable spending.
When evaluating redemption, it helps to think in terms of opportunity cost. Suppose you earn points faster than you can redeem. In that scenario, the program’s real benefit might be lower because you aren’t capturing value quickly. Alternatively, if you can redeem only occasionally (perhaps because availability is limited or because the best offers are seasonal), your expected annual value should be discounted by how likely you are to redeem in a timely manner.
Another redemptions-related issue is “effective value.” The official catalog may present points in ways that make them look equivalent, but in practice, value differs widely. For instance, a fixed-number “discount voucher” might provide a certain nominal percentage off, but the real consumer benefit depends on the price you would have paid otherwise and whether the reward is flexible enough to fit your shopping needs.
To estimate effective value, compare what you can redeem for at the time you plan to redeem. If you can redeem for travel with attractive availability and a favorable point-to-price conversion, the program can be very rewarding. If, by contrast, the options you want are either out of stock, restricted by region, or require a far higher points amount than alternatives, then your value per point might be lower.
Also pay attention to redemption mechanics such as partial redemptions, minimum point requirements, and whether you can combine points with cash. Some loyalty systems allow “points + money” redemption, which can improve practicality. Others require full point redemption for certain items, which can reduce flexibility if your points balance is near but not at the required threshold.
Finally, redemption isn’t only about what’s available in the catalog. It’s also about the experience quality and friction. If redeeming requires complex steps, multiple authentication phases, or long wait times, then even a good reward can feel less valuable. The friction cost is real—especially if you’re redeeming for time-sensitive needs like travel during peak seasons.
To evaluate Digio Livelo responsibly, you should review the costs that can offset rewards value. These can include:
From an industry standpoint, the “conditions/requirements” layer is where very risk concentrates. The correct approach is to model your expected usage and compare it to the total cost of ownership under the terms applicable to your profile.
“Total cost of ownership” goes beyond a simple annual fee comparison. Consider whether there are: (a) charges for certain transactions (e.g., specific merchant categories might carry additional fees), (b) charges tied to account inactivity, (c) fees for foreign transactions, and (d) potential costs arising from how you manage the account (like paying late). Even if the loyalty points are excellent, a fee structure that doesn’t match your behavior can reduce net value.
Interest rates can be the largest hidden variable. Many people sign up for rewards cards expecting to pay in full, but life happens: cashflow issues, unexpected expenses, or delayed income can cause them to carry balances. If the account includes a meaningful interest rate, then even a short period of revolving debt can erase months of rewards. A rational approach is to decide in advance whether you can reliably pay the statement in full. If you can’t, then a loyalty program tied to that card might not be worth it even if the points offer looks attractive.
Also watch for “conditions” that can limit eligibility for points earning. Some programs require a minimum number of transactions, a specific enrollment action, or a maintained relationship in good standing. If you forget to enroll, fail a required step, or make a transaction during a period when the program had a different configuration, you might lose earn eligibility for that transaction.
Finally, consider the difference between promotional value and baseline value. Promotions can be generous, but they are also time-limited. If you evaluate the program based on a promo-only earn rate but plan your spending after the promo ends, your realized value will likely be lower than expected. A better strategy is to evaluate baseline earn rates and then treat promotions as an upside rather than a core assumption.
Think of rewards as a portfolio that should match your monthly behavior. The following profile checks help you decide objectively:
Conversely, if your spending is irregular, you frequently carry balances, or you don’t plan to redeem points on a realistic timeline, the program may provide less practical benefit.
To make this “fit” assessment more concrete, you can ask yourself a set of lifestyle questions. For example: Do you spend more on categories that the program rewards heavily? Do you make most purchases at merchants that participate in campaigns? Do you typically shop online, where some programs might credit points faster or at a different posting rate? Do you prefer experiences that can have limited availability, or do you prefer “always available” redemptions like bill credits?
Another lifestyle variable is your time horizon. Some people think in quarterly goals (“I want a reward every three to four months”), while others treat points as an annual accumulation. If Digio Livelo points have expiration rules, then the time horizon becomes crucial. Even if you can earn points steadily, if you cannot redeem or convert them before the expiration window, you could lose value.
Also evaluate your willingness to engage with the program. Some programs require you to track points, check redemption availability, and occasionally book partners. If you prefer “set-and-forget” value, you may want to prioritize redemption options that are simpler and less constrained. If the program offers better value but demands more engagement, then it might still be worth it, but you should be honest about your willingness to participate.
Finally, consider “friction and switching.” If you already have a card or loyalty structure that works for you, switching just to chase rewards can cause temporary disruptions. Sometimes the best rewards strategy is not necessarily switching every card, but optimizing where you concentrate your spend. A good fit is one that strengthens your current system rather than requiring you to overhaul everything at once.
When loyalty systems mention suppliers, partners, or merchants, they’re referring to the network that makes rewards possible. For Digio Livelo, this can involve multiple categories—retail, travel, services—where partners participate in point-earning campaigns or redemption offerings.
In real-world terms, the partner ecosystem matters because it determines:
To evaluate partner impact, compare the program’s current partner list and category rules to your existing shopping routines. The more overlap, the stronger the practical fit.
“Network effects” in loyalty programs are subtle but important. The more partners the program attracts, the more frequently you can find earning opportunities that match your real spending. When partners align well, you don’t need to change your behavior much to get value. But if partners are concentrated in categories you don’t use, then the program value becomes theoretical.
Also note that partner participation can be dynamic. Promotions can appear and disappear, and redemption availability can change. Even the same partner category can have different terms at different times. That’s why it’s useful to treat your evaluation as “current conditions now,” and to re-check periodically if the program is central to your rewards plan.
If you want a more robust approach, map your last 1–2 months of card transactions into categories and compare them to the program’s qualifying categories and partner campaigns. You don’t need perfect accuracy; you need enough to see whether the program rewards your actual behavior.
Additionally, consider whether the partner ecosystem is consistent across different channels. Some partners may only count for points on certain platforms (in-store vs. online). If you use one channel heavily, a mismatch can reduce your value even if the partner list looks strong.
Use the framework below to compare the Digio Livelo proposition to your personal spending pattern.
| Evaluation step | What to check | Practical condition |
|---|---|---|
| 1. Confirm eligibility | Account status requirements, region or plan eligibility, and whether points require specific enrollment | Choose only offers that clearly match your current circumstances |
| 2. Identify qualifying purchases | Which merchant categories or transaction types earn points, and whether there are caps | Match qualifying categories to your typical month-to-month spend |
| 3. Verify earning mechanics | Earn rates, posting timelines, and any promotional multipliers | Model points using conservative assumptions if promotions are time-limited |
| 4. Assess total cost | Fees and interest implications; confirm whether costs offset rewards | Reward value should exceed all fixed costs under your realistic behavior |
| 5. Review redemption rules | Point minimums, redemption options, and expiration or inactivity policies | Make sure the rewards you want are reachable with your expected point balance |
| 6. Test your redemption preference | Check whether the highest-value redemption is aligned with what you actually want | If your preferred benefits are hard to obtain, the plan’s “effective value” falls |
| 7. Decide with discipline | Set payment goals (pay in full if possible) and redemption timing | Rewards should be treated as an enhancement, not a reason to carry balances |
To make this process even more disciplined, you can add two extra “diagnostic checks” that many people skip:
| Additional diagnostic | What to check | Practical condition |
|---|---|---|
| 8. Rate stability | Whether earn rates are stable or change frequently; identify which parts are promotional | If rates are volatile, evaluate baseline value, not peak campaigns |
| 9. Points behavior | How points convert or transfer; whether points can be reversed due to returns or cancellations | If points reverse often, model your net points after typical returns |
Some consumers experience points “surprises” because returns happen or because an order is canceled. If a transaction is reversed, points may be deducted as well. So if you routinely make returns or place orders that you cancel often, your net points accumulation might be lower than your gross spend would suggest. Accounting for returns is especially important if you shop frequently online.
Loyalty-linked financial products operate under multiple constraints. From a systems perspective, reward programs must manage liability (how many rewards they promise), fraud risk (unauthorized transactions), and cost of partner participation (which merchants subsidize point value). This is why the terms often include eligibility rules, caps, and periodically updated categories.
For customers, the takeaway is simple: an offer like Digio Livelo should be interpreted as a rules-based plan where value depends on compliance with program conditions and accurate expectations about redeemability. This is not just “marketing.” It is the operational reality that keeps the program sustainable for the broader participant base.
Risk management also explains why caps and exclusions exist. If a program rewards everything at the same rate with no limitations, it becomes too expensive. Partner subsidies are not unlimited; they depend on merchant agreements and expected incremental sales. That means loyalty programs usually direct the best rates toward transactions that drive specific outcomes—like recurring spend, travel bookings, or specific partner merchants.
Fraud risk introduces additional layers. Programs may monitor for suspicious behaviors like unusual transaction patterns, attempts to game point conversions, or repeated redemption cycles that seem automated. While most normal customers will never face these systems directly, risk controls can indirectly affect you—for example, by causing points to be delayed or by requiring verification for certain redemptions.
From the customer viewpoint, the best defense is documentation and awareness. Keep track of the date and details of transactions that you expect to earn points. If points don’t post within the stated time, you’ll be ready to follow the program’s support workflow. Many loyalty disappointments are actually “process issues” rather than “value issues.” If you respond quickly and provide the right details, you can often resolve missing points.
Also recognize that loyalty systems may change categories and redemption offers for business reasons. If you anchor your finances and expectations on a category that later becomes excluded or capped, you might feel betrayed. But from a professional risk lens, these updates are expected and sometimes necessary. That’s why it’s rational to periodically re-check the terms and partner lists.
The prompt you provided does not include a specific city or country for localization, so this article does not reference local landmarks or regional expressions. If you share your location, I can tailor the evaluation checklist to nearby merchant categories and typical redemption availability patterns in your area.
Even without exact localization, you can still adapt the framework to your region by thinking in terms of the kinds of merchants you use most (supermarkets, pharmacies, transportation, utilities providers, online marketplaces). The goal is to match program earning categories to the merchants you already patronize.
If you live in a region where certain types of redemption (for example, specific travel routes or experiences) are less available, you should adjust your redemption modeling accordingly. A loyalty program can be equally “fair” across regions in its rules but still deliver different practical value because partners serve different markets. That is why verifying redemption availability locally matters.
Digio Livelo is commonly used to describe a rewards relationship where financial activity associated with Digio can help you accumulate points that connect to Livelo’s loyalty environment. The exact details depend on the specific product and current program rules.
In plain terms, think of it as a chain: you perform eligible transactions through the Digio-branded financial product, points accrue under those rules, and then those points are used inside the Livelo ecosystem to access rewards. If any step in that chain fails—because the transaction is excluded, because points don’t post yet, or because redemption rules prevent the option you want—the overall experience can be different from what you expected.
Compare your monthly spending categories to the program’s qualifying transactions, then estimate how many points you can reasonably earn. Finally, verify whether the redemptions you want are achievable with those points while also accounting for any applicable fees.
A practical method is to build a mini spreadsheet. List your typical monthly spend by category, apply an earn assumption for each category (using conservative numbers if you’re unsure), subtract expected costs, and then map your expected monthly points balance to a redemption you realistically want. If your net value looks positive and you can actually redeem in time, it’s likely a good fit.
Also, incorporate payment discipline into your worthiness test. If you can pay in full consistently, points are an enhancement. If you might carry a balance, the expected value can turn negative quickly. In that situation, even a strong earn rate might not be enough to compensate for interest costs.
Not necessarily. Many loyalty programs differentiate earn rates by merchant category, transaction type, or promotional campaigns. Check the current earn rules for your plan and confirm whether any transaction types are excluded or capped.
To avoid confusion, check for four categories of differences: (1) which merchant codes qualify, (2) whether rates differ by channel (online vs. in-store), (3) whether rates are tiered by spend level or volume, and (4) whether some transactions are excluded or earn at a lower baseline rate. Many people incorrectly assume that all card swipes behave identically; in loyalty ecosystems, they rarely do.
Often, loyalty programs include expiration or inactivity rules. For objective decision-making, review the official terms that apply to your account at the time you join, and confirm how points behave if you stop earning for a period.
When points expiration exists, your “value window” becomes important. If you redeem once per year, you need to ensure points remain active across that period. If the program requires activity to prevent expiration, you might need at least one qualifying transaction during the relevant timeframe.
Also verify whether points expire uniformly or whether specific point types (for example, points earned through promotions) have shorter validity windows. Some ecosystems separate standard points from promotional points. If promotional points expire faster, you might need to redeem those first.
Look for monthly or annual fees, interest rates if you carry a balance, and requirements that determine whether you stay eligible for earn/redemption benefits. If you revolve debt, the financial cost can outweigh the reward value.
Beyond fees and interest, pay attention to conditions such as minimum spend requirements for waived annual fees, eligibility for certain redemption offers, or account status requirements. If rewards depend on “good standing,” then if you miss payments or violate terms, points benefits could be reduced or frozen.
Also watch for conditions tied to enrollment. Some programs require you to actively link the loyalty account to the financial product or to confirm participation. Missing these steps might prevent points from being credited for transactions performed before the enrollment is effective.
Redemption routes depend on the partner ecosystem and the specific benefit catalog available in the program at that time. Evaluate redemption options that match your goals—travel, shopping, or services—rather than assuming a single top-use case.
In practice, some redemptions are more limited than others. Travel partners can have inventory constraints by destination, date, and availability. Shopping rewards might depend on brand stock. Experiences can be restricted by location and season. Services can require appointment scheduling. For best results, align redemption choices with your flexibility. If your schedule is strict, prefer rewards with more predictable availability.
Point posting timelines vary by program rules and transaction processing. If redemption timing matters, review the guidance for when points are credited and use conservative planning if there are known delays.
A good strategy is to assume a delay between transaction date and points availability, especially around holiday periods or when merchants take longer to settle. If you plan redemptions for an event, don’t rely on “points will appear quickly.” Instead, check the typical posting timeline and build in a buffer.
Some programs impose caps on promotional earn rates or limit eligible categories. Confirm the presence of any caps, and model your month with your typical spending volume.
Caps can be monthly, quarterly, or tied to specific campaign periods. If your spend in a rewarded category exceeds the cap, the additional spend may earn at a lower baseline rate or not qualify for the promo multiplier. Understanding caps helps you avoid overestimating points.
Yes. The effective value differs based on spending mix, payment discipline (paying in full versus carrying balances), redemption preferences, and whether you engage with partner categories that offer favorable earn mechanics.
A customer who regularly shops at rewarded categories and redeems strategically typically experiences higher value. A customer who rarely redeems, or who redeems for options with lower point efficiency, might see much less value. Even within the same program, individual outcomes can vary significantly.
Use a “total value” comparison: expected points earned (conservatively), realistic redemption value for your preferred rewards, and total costs under your behavior. Avoid comparing only headline promotional rates.
To stay objective, compare net outcomes rather than gross offers. If one program gives more points but has higher fees, stricter exclusions, or harder redemption access, it may be worse in net value. Another program might give fewer points but have lower friction, better redemption availability, or fewer exclusions in your common spending categories. The best comparison method is to estimate your net value under each program using the same assumptions about your spending and redemption timing.
To keep the evaluation objective, you can compute a simple “expected rewards value” model:
This method won’t require dramatic assumptions, and it produces a decision grounded in your real behavior rather than in optimistic marketing narratives.
To strengthen the model further, you can add two conservative adjustments:
Even without exact numbers, this “model mindset” protects you from the biggest trap in loyalty evaluation: treating marketing examples as if they are your personal outcomes. Your outcomes will depend on your transaction mix, on your ability to redeem, and on timing.
When assessing loyalty-linked financial products, the very dependable information usually comes from:
Because you didn’t provide specific prices or a named supplier entity beyond the keywords, this article intentionally avoids unverified figures. For accurate totals, consult the official Digio and Livelo documentation tied to your exact plan.
For a more robust verification process, you can also cross-check the following items inside the official rules: (a) how points are credited for each transaction type, (b) how points are adjusted for returns and cancellations, (c) the precise redemption options and whether they vary by region, and (d) the point expiration and inactivity rules. These details are often the difference between an impressive offer on paper and a frustrating experience in practice.
Digio Livelo can be a solid rewards option when your spending categories align with qualifying rules and when redemption goals match the catalog’s practical availability. The smartest approach is to treat the offer as a system: verify earn mechanics, calculate total costs, review redemption and expiration conditions, and then decide based on your own usage pattern rather than on headline claims.
If you do the verification properly, you’re not just “hoping” the program works—you’re building a predictable rewards routine. And that predictability is what turns loyalty points from a marketing concept into real value.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
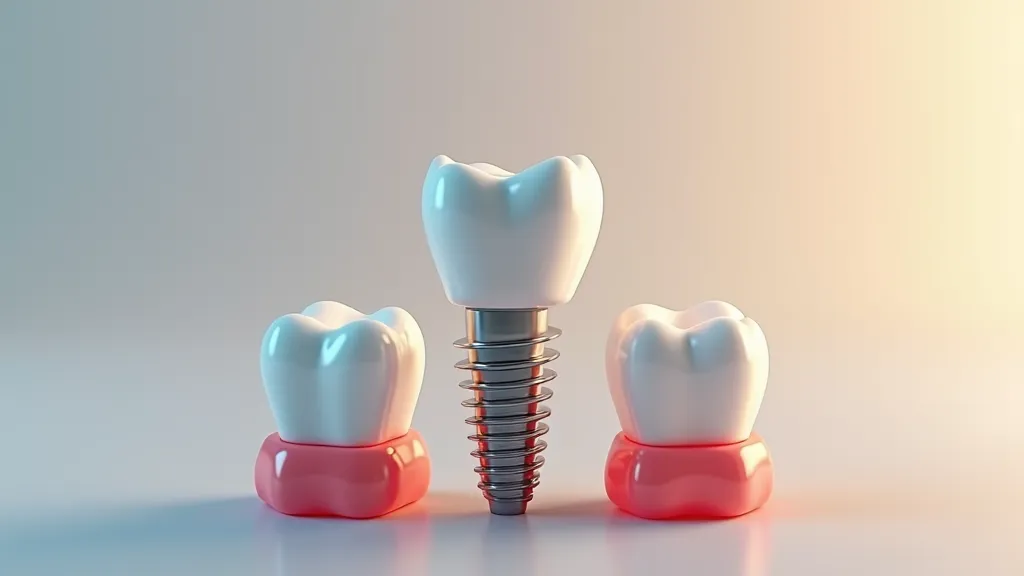
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Understanding 01047554402 Supplier Leads and Pricing
This guide explains how to evaluate supplier leads tied to 01047554402, interpret practical pricing signals, and reduce sourcing risk. Objectively, the keywords relate to supplier identification, lead validation, and quotation comparison practices used across procurement and trade channels. You’ll learn what to verify, how to document requirements, and when to escalate for clarification.
Digio Livelo: How to Evaluate a Rewards Offer
This guide helps you evaluate Digio Livelo by explaining how the rewards mechanism works, what to check before joining, and what “good fit” looks like for different lifestyles. Objectively, Digio and Livelo are typically discussed in the context of Brazilian loyalty programs, where partners and spending habits influence point accumulation and redemption options.
Understanding 01047554402 Supplier Leads and Pricing
This guide explains how to evaluate supplier leads tied to 01047554402, interpret practical pricing signals, and reduce sourcing risk. Objectively, the keywords relate to supplier identification, lead validation, and quotation comparison practices used across procurement and trade channels. You’ll learn what to verify, how to document requirements, and when to escalate for clarification.